
Is Record Production Altering The Investment Case For Cenovus Energy (TSX:CVE)?
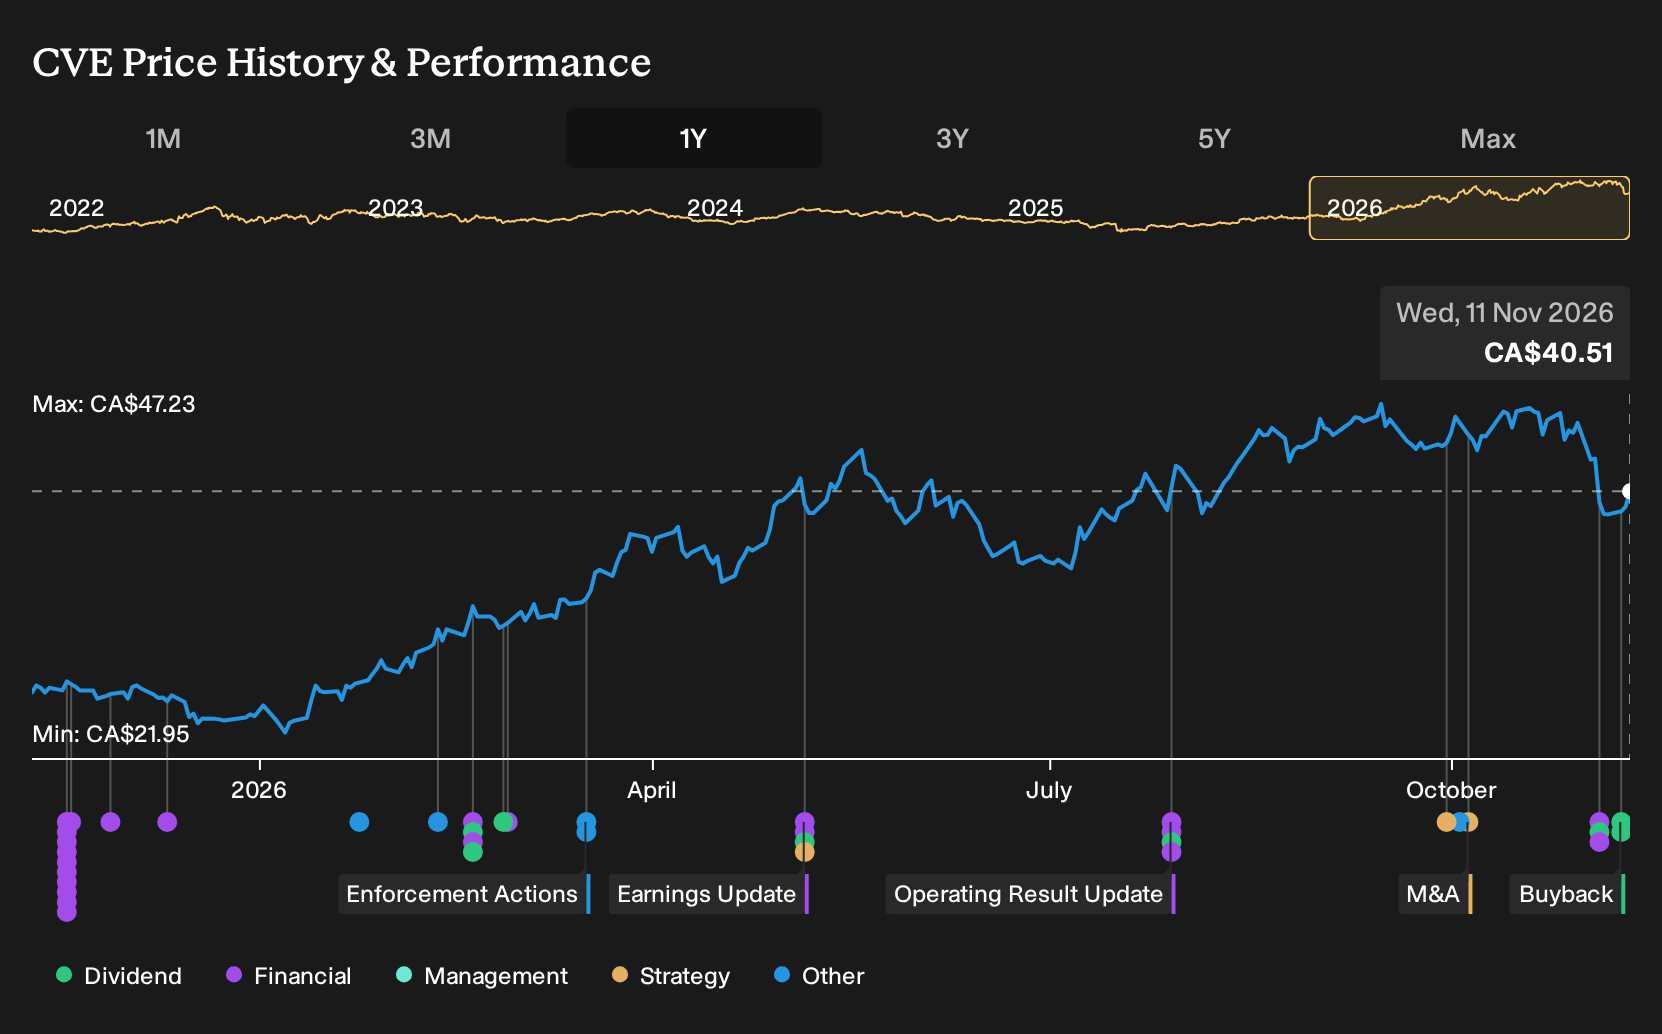
- Cenovus Energy reported third quarter 2026 sales of C$15,984 million and net income of C$3,360 million, confirmed a C$0.22 quarterly dividend, and authorized a new share repurchase program of up to 126,482,982 shares, or 7% of its share capital, with all repurchased shares to be cancelled.
- The combination of record upstream production above 1,000,000 BOE/d, higher earnings per share, and continued capital returns through dividends and buybacks highlights how Cenovus Energy is focusing on operational delivery while directly shrinking its share count.
- This analysis examines how Cenovus Energy's record production and new buyback authorization may reshape the earlier investment narrative around integration.
Scan other energy producers putting excess cash to work through buybacks and dividends with a curated set of 5 high quality undervalued stocks that share similar capital return themes to Cenovus Energy.
Cenovus Energy Investment Narrative Recap
Cenovus Energy may appeal to investors who believe its integrated oil sands and refining model can continue turning high production and large projects like Narrows Lake and West White Rose into steady cash, even as Canadian regulation and carbon costs evolve. The analyst consensus narrative on Simply Wall St focuses on that integration and project delivery as the core story.
The latest quarter puts the operating focus on sustaining production above 1,000,000 BOE/d, managing condensate costs, and keeping refineries running efficiently while net debt trends lower. In the short term, execution on turnarounds and the Athabasca asset build-out appears more important than the buyback itself, while regulatory and tax pressure remain among the clearest business risks.
The new normal course issuer bid to repurchase up to 126,482,982 shares, or 7% of share capital, fits into that framework as a capital allocation decision that relies on strong recent earnings and lower net debt. Investors now have a clearer view of how Cenovus Energy may split cash between the C$0.22 dividend, the planned Athabasca expansion and balance sheet goals.
In terms of potential catalysts, the buyback touches on several moving parts. Execution on the acquisition of another Alberta oil producer, completion of the heavy maintenance cycle and capturing Athabasca synergies will influence how much excess cash remains to use this authorization. If taxes, royalties or condensate costs move higher, the practical pace of repurchases could be the most sensitive element.
Cenovus Energy's current earnings are CA$6.7b, with analysts forecasting revenue growth of 1.7% per year and projecting CA$56.7b of revenue and CA$6.9b of earnings by 2029, which implies an earnings increase of about CA$0.2b from today.
Discover how Cenovus Energy's fair value indicates a 30% potential upside to its current price, which could materialize more quickly than many investors anticipate.
Exploring Other Perspectives
One big swing factor that bullish analysts keep coming back to is capital intensity rather than regulation. Before this buyback, the most optimistic forecasts already pencilled in revenue of about C$58.0b and earnings near C$8.2b by 2029 for Cenovus Energy. You now have fresh information that could push those views in either direction.
Explore 3 other Cenovus Energy fair value estimates, including one that suggests as much as 214% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cenovus Energy research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cenovus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cenovus Energy's overall financial health at a glance.
Looking for more investment ideas beyond Cenovus Energy?
Once you have formed a view on Cenovus Energy, it can help to widen the lens and compare it with other opportunities that share different risk and return profiles. The Simply Wall St Screener can surface stocks that match what you care about most, whether that is valuation, balance sheet strength, or future potential.
- If you are hunting for quality at a reasonable price, start with a focused set of undervalued opportunities using the 5 high quality undervalued stocks.
- For readers who care most about durable finances over everything else, filter for businesses with stronger balance sheets through the list of solid balance sheet and fundamentals (5 results).
- If you want to get ahead of the crowd, scan for lesser known opportunities with solid fundamentals using the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com