
Record Backlog Could Be A Game Changer For Finning International Stock (TSX:FTT)
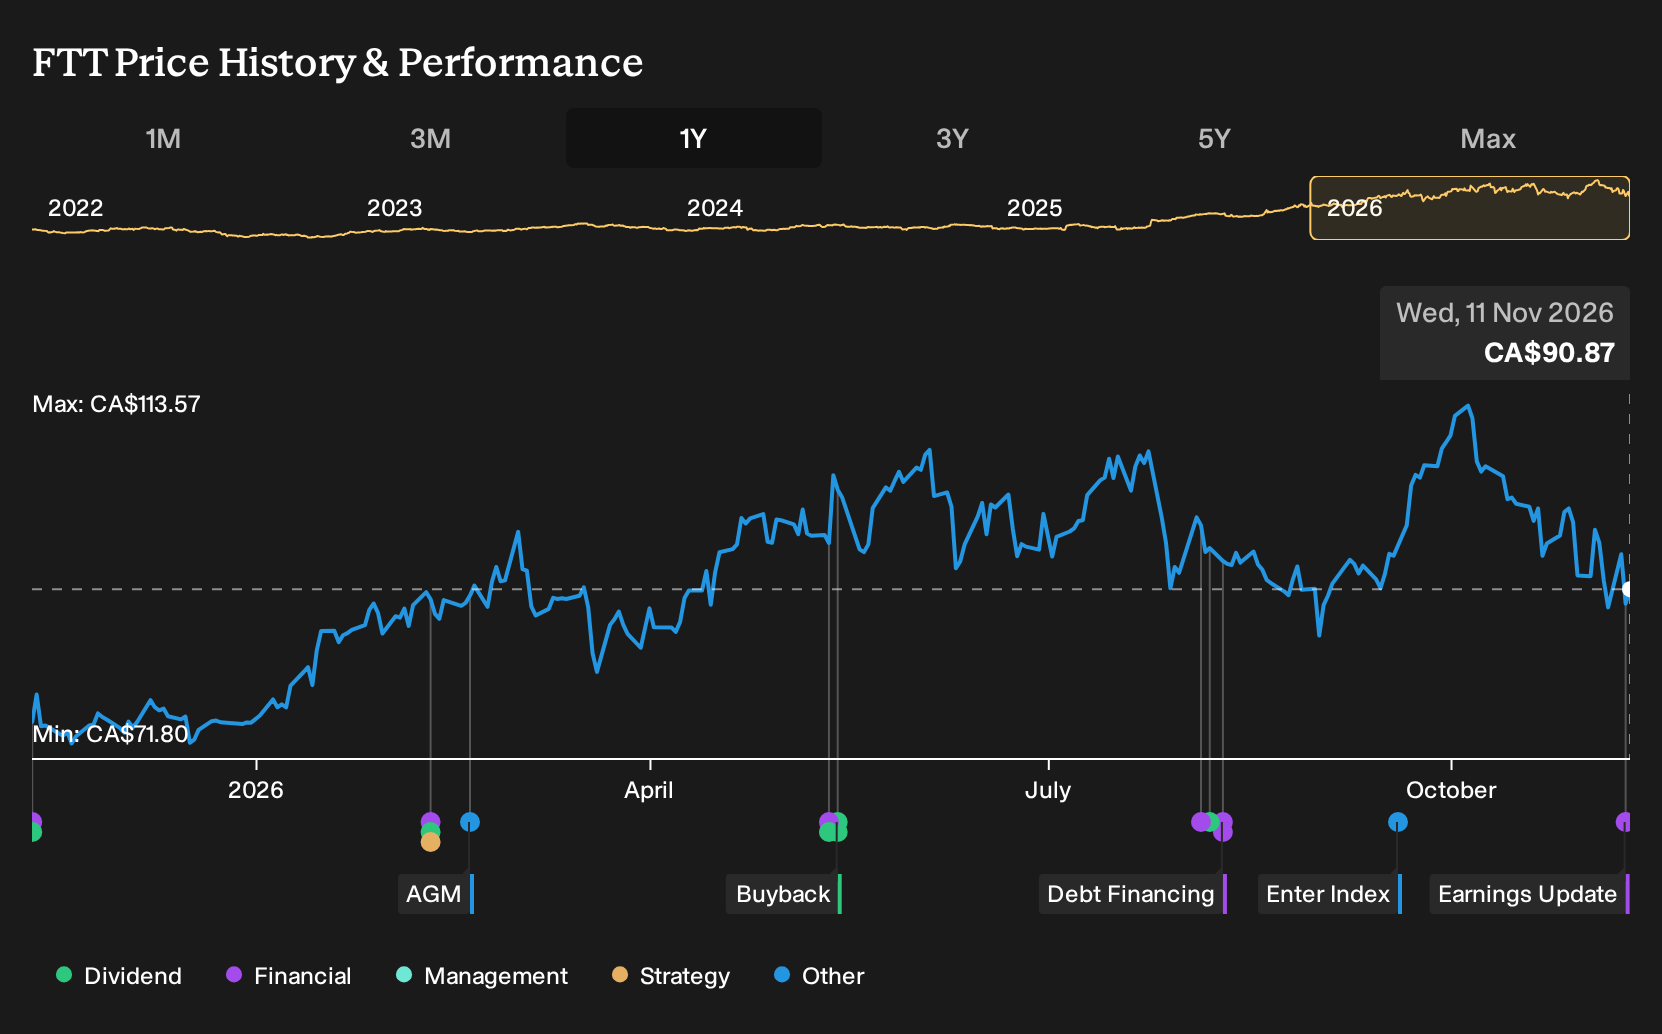
- Finning International reported third quarter 2026 revenue of C$3.036b and net income of C$155 million, with record equipment backlog and continued dividends and share repurchases.
- The mix of higher product support and mining related equipment orders, along with a large data center power contract, underscores how diversified demand is shaping Finning International's order book and capacity needs.
- The focus will now be on how this record backlog reshapes Finning International's investment narrative and longer term earnings profile.
Finning International Investment Narrative Recap
To own Finning International, you need to be comfortable with a business built around heavy equipment cycles, a large installed base and recurring product support. The analyst consensus Narrative on Simply Wall St leans heavily on that mix plus the record C$4.1b equipment backlog. The latest quarter shows revenue and earnings per share roughly in line with that story, so the near term thesis around backlog conversion remains intact.
The near term swing factor is whether Finning International can turn that order book into cash without further squeezing margins. South American labor costs, a mix tilted toward lower margin new equipment and ramp up spending for technicians all sit on the other side of the scale. The quarterly figures do not materially change that risk reward balance.
The most relevant piece of recent news is the record C$4.1b equipment backlog, supported by a large Canadian data center backup power order that is expected to be delivered by the end of 2027. That pipeline aligns with the mining, power and rental demand that analysts have highlighted as key drivers for the business in the analyst consensus Narrative on Simply Wall St.
For you as a shareholder, the central question is execution. Turning that mining and power backlog into high quality product support revenue while margins are under pressure in South America will likely define the next phase. If the mix shifts further toward lower margin equipment or Chilean support work slows more than expected, the backlog can still feel heavy rather than helpful.
Finning International's current analyst narrative points to revenue of CA$13.0b and earnings of CA$833.2m by 2029, based on forecast annual revenue growth of 5.3% and an earnings increase of about CA$283.2m from CA$550.0m today.
Uncover why Finning International's fair value indicates a 34% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value views for Finning International, yet they already stretch from about C$122 to C$169 per share. That very wide band, built on pre Q3 forecasts, sits next to concerns about persistent South American margin pressure and Chilean mining support moderation. Opinions clearly diverge, so it makes sense to review several community viewpoints before leaning on any single narrative.
Explore another Finning International fair value estimate, including one that suggests as much as 86% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Finning International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Finning International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Finning International's overall financial health at a glance.
Looking for more investment ideas beyond Finning International?
If Finning International has sharpened your thinking about industrials and capital cycles, it can be useful to compare it with other listed businesses that share some of the financial traits you care about most. The Simply Wall St Screener helps you quickly filter for companies that fit those preferences.
- If resilience matters most to you, start with a set of companies that score well on financial strength using the 9 resilient stocks with low risk scores.
- For investors focused on value, compare Finning International with a broader pool of under-the-radar opportunities by scanning our 7 high quality undiscovered gems.
- If you want a mix of balance sheet quality and solid fundamentals, narrow your watchlist using a curated list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com