
Paramount Resources (TSX:POU) Q3 Loss Puts Its Undervalued Narrative To The Test
Why Paramount Resources Stock Is In Focus After Q3 Earnings
Paramount Resources (TSX:POU) is back on investors’ radar after its latest earnings release, where higher reported revenue came alongside a significantly larger quarterly net loss and a continued loss over the first nine months of 2026.
The Q3 update has arrived after a strong run for Paramount Resources, with the share price up 36.76% year to date to CA$32.96 and contributing to a 43.99% total shareholder return over the past year, even as the latest results highlight higher losses and a fresh dividend declaration. This may be reshaping how investors weigh growth potential against risk.
Scan how Paramount Resources compares with other Canadian energy plays that combine strong balance sheets and fundamentals using our hand picked list of solid balance sheet and fundamentals (5 results) today.
Paramount Resources now trades below the average analyst price target even after a strong run. Is that discount compensation for real earnings risk, or is the market leaning too hard into caution as the valuation math comes together next?
Most Popular Narrative: 15.5% Undervalued
On the analyst consensus Narrative on Simply Wall St, Paramount Resources screens as undervalued, with a fair value of CA$39 against the last close at CA$32.96. The framework behind that gap matters for anyone watching this Q3 move.
The multi decade project runway at Willesden Green, Sinclair, Northeast Alberta thermal and multilateral heavy oil, and Northeast BC shale gas, including management’s view that Willesden Green can support a long production plateau, points to a lengthy period where Paramount Resources can deploy capital into known projects, which can support revenue and earnings visibility.
The shift toward a manufacturing style development model for Duvernay and Montney assets, with Willesden Green designed for a long production plateau and supported by wells that have exceeded internal type curves, creates scope for more predictable volumes and operating costs, which can support net margins.
See why 1 investors see Paramount Resources as 15% undervalued.
Result: Fair Value of CA$39 (UNDERVALUED)
Still, the Paramount Resources story can break if the intensive build out collides with weaker commodity prices, or if Canada specific regulation cuts into project economics.
Find out about the key risks to this Paramount Resources narrative.
Another Take On Paramount Resources Valuation
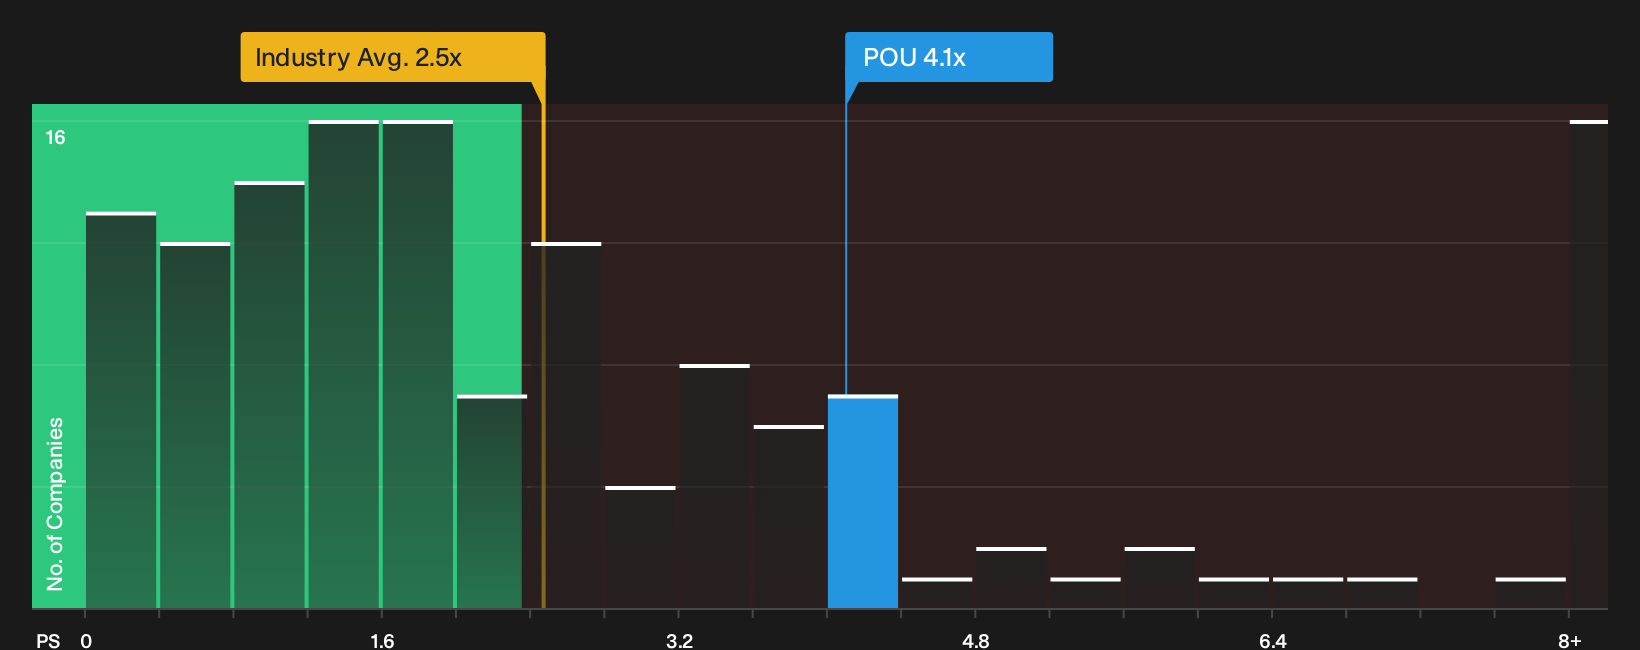
Analysts on Simply Wall St frame Paramount Resources as undervalued against a CA$39 fair value, yet the market is assigning a rich P/S of 4.1x. That is higher than Canadian oil and gas peers at 2.5x and above a fair ratio of 2.7x, which lifts valuation risk if sentiment cools.
If the share price eventually drifts toward that lower fair ratio, today’s premium could matter far more than the current discount to analyst targets, especially for anyone thinking about adding fresh capital at these levels. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Paramount Resources so far. If you want to move quickly and reach your own view, start by weighing its 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Paramount Resources?
You have fresh context on Paramount Resources now, so this is the moment to widen the lens and line up a few other candidates on your watchlist.
- Pressure test your value thesis across a broader opportunity set and see which businesses screen as attractively priced with strong fundamentals through the 5 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by focusing on payout reliability and income potential using the hand picked 3 dividend fortresses.
- Tilt toward resilience by filtering for companies with sturdier finances and cleaner balance sheets via the curated 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com