
Celestica Stock Gains Attention After Raised AI Revenue Guidance
- Celestica reported third quarter revenue of US$5.83b, raised its 2026 sales outlook to US$21b and issued an initial US$40b revenue target for next year. The adjusted operating margin was 8.5%, supported by the Connectivity & Cloud Solutions segment tied to AI and data center hardware.
- The business is deepening its role as a manufacturing and hardware partner for hyperscalers and defense customers, with concentrated exposure in AI data center racks, networking platforms and mission critical aerospace and military electronics that rely on long lead time, high reliability production.
- We will look at how Celestica's investment narrative evolves as raised AI driven guidance reshapes expectations for growth, mix and risk.
Scan beyond Celestica and compare its AI hardware story with a curated list of other infrastructure plays through the 53 AI infrastructure stocks.
Celestica Investment Narrative Recap
To own Celestica, you need to be comfortable with a very focused AI hardware and defense manufacturing story that leans on a handful of large customers and program ramps. The recent revenue and margin update tightens the near term catalyst around execution in Connectivity & Cloud Solutions, where AI racks and networking platforms remain the core swing factor for operating performance.
That same focus sharpens the main risk. Customer concentration, heavier capital spending and the ongoing patent dispute all sit in the foreground if AI hardware orders slow or shift. The analyst consensus Narrative on Simply Wall St highlights these pressures as key points that could challenge the current AI led outlook.
The clearest announcement that ties into this is management’s guidance for about 85% revenue growth in Connectivity & Cloud Solutions in 2026, supported by AI and data center programs. You are essentially judging whether Celestica can convert that AI pipeline into sustained, high reliability production without hitting bottlenecks in capacity, supply chain or yields.
That projected CCS ramp also interacts directly with risk. Capital intensity is already elevated, with about US$1b of 2026 capex tied to AI infrastructure and an indicative US$1.5b flagged for 2027, so any resizing or delay in those multibillion dollar OpenAI or AMD related racks would challenge free cash flow and the margin profile the business is working toward.
Celestica's narrative projects $55.4b revenue and $3.8b earnings by 2029. This implies analysts are assuming 52.6% yearly revenue growth and an earnings increase of about $2.7b from $1.1b today.
Uncover why Celestica's fair value indicates a 98% potential upside to its current price that could narrow quickly.
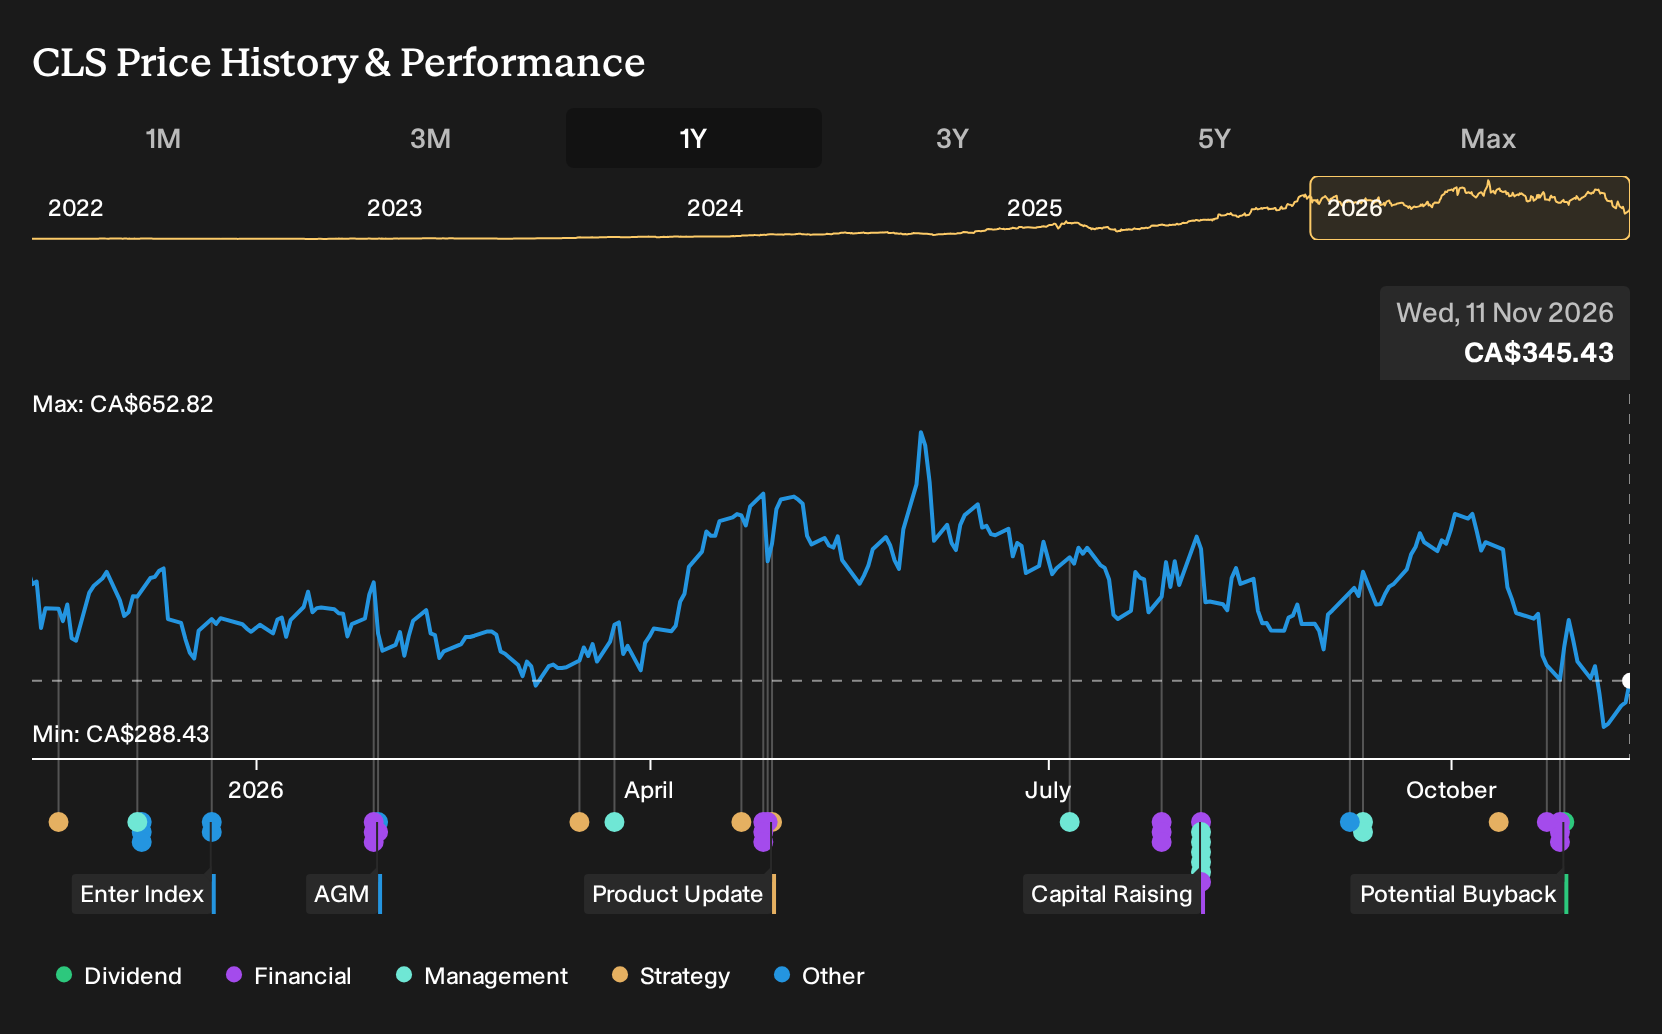
Exploring Other Perspectives
One optimistic twist in the alternate Celestica narrative is the focus on a much larger AI hardware ramp, where the most bullish analysts were modelling revenue of about US$74.2b and earnings of US$5.1b by 2029, compared with US$55.4b and US$3.8b in the baseline. Those views all pre date this latest guidance, so you should expect opinions to move around as fresh data lands and explore how different forecasts fit your own expectations.
Explore 2 other Celestica fair value estimates, including one that suggests as much as 515% potential increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Celestica research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Celestica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Celestica's overall financial health at a glance.
Looking For More Investment Ideas Beyond Celestica?
Once you have a handle on Celestica and its AI hardware story, it can be useful to widen the lens and compare it with other opportunities that fit different risk and return profiles using the Simply Wall St Screener.
- If you want potential value with a margin of safety, start with a 5 high quality undervalued stocks that combine solid fundamentals with attractive pricing.
- For investors who care most about balance sheet strength, scan through a list of solid balance sheet and fundamentals (5 results) that can help underpin resilience in tougher conditions.
- If you prefer lower volatility and steadier business profiles, narrow your search to a 9 resilient stocks with low risk scores that may suit a more defensive approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com