
NextNav (NN) Earnings Beat Puts Its 3D PNT Valuation Story Back In Focus
NextNav (NN) drew fresh attention after its Q3 2026 earnings on 10 November, pairing better than expected headline results with new technical milestones, partnerships and ongoing FCC engagement around its positioning technology.
That after hours jump on the Q3 beat came against a tougher backdrop, with the 30 day share price return down 28.21% and the 90 day share price return down 56.69%. However, the 3 year total shareholder return of 74.95% shows longer term holders have still seen gains even as recent momentum has faded.
Compare NextNav's regulatory and 5G positioning story with other niche plays by scanning our hand picked 19 high quality undiscovered gems that pair strong fundamentals with under the radar narratives.
NextNav now sits in an odd spot. The technology story just got louder while the share price over the past quarter moved sharply the other way. So is a strong platform being mispriced or fairly discounted for the risks ahead?
Most Popular Narrative: 75% Undervalued
On the analyst consensus Narrative on Simply Wall St, NextNav carries a fair value of about $33.67 compared with the last close at $8.45, which frames a wide gap between the current quote and the implied long term potential behind its 3D PNT story.
Progress at the FCC toward an NPRM on 5G based 3D PNT in the lower 900 megahertz band, combined with a congressional push to free more spectrum, sets the stage for commercial rights that can unlock new service revenues and crystallize spectrum value on the balance sheet, supporting higher earnings and asset valuations.
Find out how 4 investors see NextNav as 75% undervalued.
The Narrative itself leans on an 8.79% discount rate and still bakes in analyst forecasts that revenue declines at about 11.5% a year and that NextNav remains loss making over the next three years. Yet it arrives at a fair value that is roughly 4x the current share price. Analysts also assume profit margins eventually align with a 12.0% software sector level and apply a very large future P/E multiple to bridge today’s loss position to those distant earnings, which is a key reason the implied upside screens so big. The result is a valuation story that depends heavily on successful FCC outcomes, broader 5G deployment of TerraPoiNT and Pinnacle, and the ability to turn licensed spectrum and pilots into recurring contracts over time.
Result: Fair Value of $33.67 (UNDERVALUED)
Still, this hinges on regulators and customers showing up in time, since extended FCC delays or limited uptake beyond trials could leave NextNav’s 3D PNT thesis stuck in neutral.
Find out about the key risks to this NextNav narrative.
Another View: NextNav On Book Value
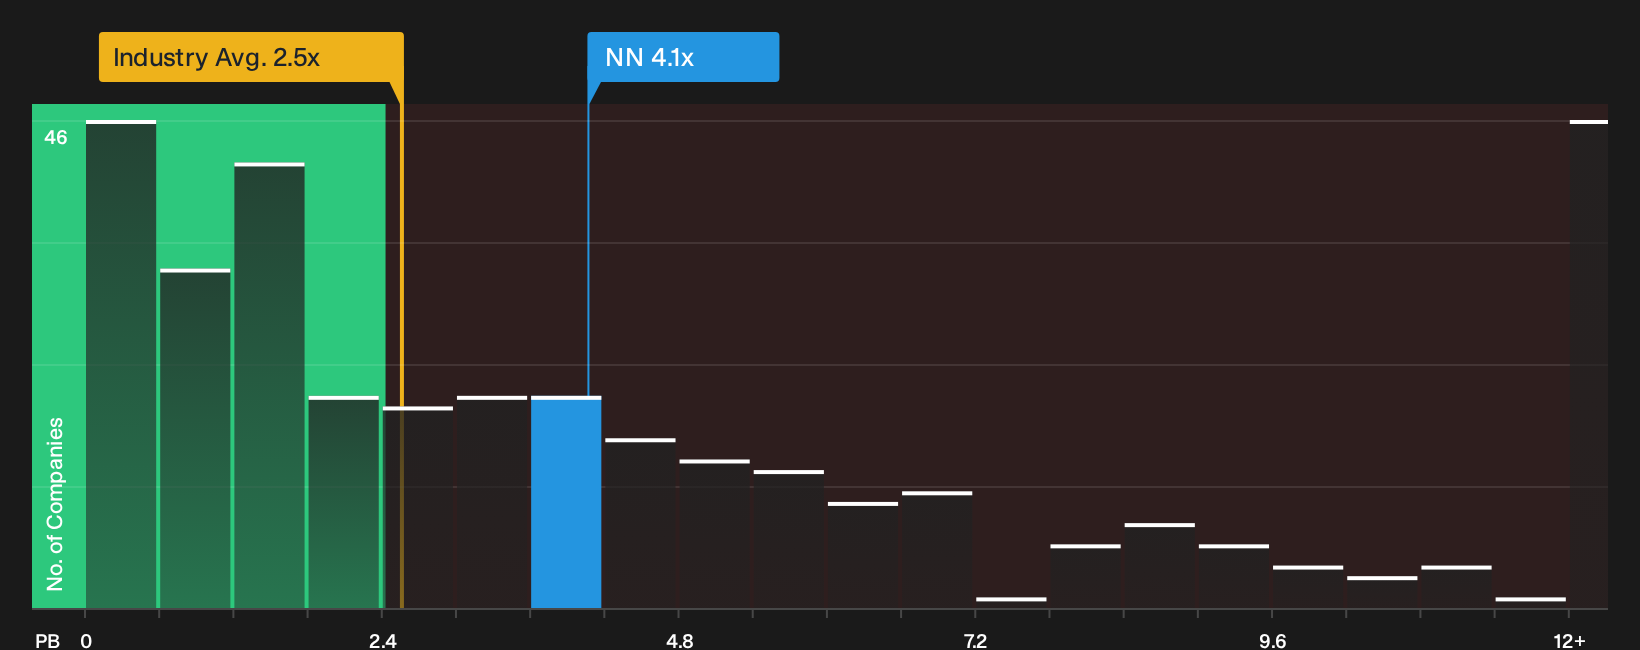
The first story paints NextNav as roughly 75% undervalued against a $33.67 fair value. A simple P/B check tells a different story. At about 4.1x book value versus 2.5x for the wider US software group and 4x for peers, the stock screens expensive on this metric, especially with shrinking revenue and ongoing losses. So which signal do you trust when the story and the balance sheet are pulling in opposite directions?
To see how that premium to book filters through the rest of the metrics and what it could mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around NextNav leaves you on the fence, move fast and stress test the thesis against the underlying numbers. To frame that decision with the clearest red flags in one place, start with our breakdown of 4 important warning signs
Looking for more NextNav-sized ideas?
Do not stop at a single ticker. Broaden your watchlist with focused stock ideas that line up with the kind of edge you want in your portfolio.
- Target potential mispricings by scanning a curated pool of quality businesses that look cheap on fundamentals through the 32 high quality undervalued stocks.
- Tilt your holdings toward resilience by checking out a list of solid balance sheet and fundamentals (24 results) that can help steady overall portfolio risk.
- Hunt for early stage opportunities by reviewing a tightly filtered 12 elite penny stocks with strong financials list before others start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com