
Is HNI (HNI) A Bargain As Strong Q3 Results And Guidance Lift Attention?
Why HNI stock is back in focus
HNI (HNI) has jumped onto investor watchlists after third quarter results showed sales of US$1,592.9 million and net income of US$90 million, paired with fresh guidance and an updated dividend.
HNI’s latest earnings and dividend update come after a steady climb in the share price this year, with a year-to-date share price return of 15.12% and a one-year total shareholder return of 27.96%. This points to momentum that has been building rather than fading.
Scan beyond HNI’s post-earnings momentum and compare it with a curated 32 high quality undervalued stocks that pairs solid fundamentals with potential upside.
Bulls point to HNI’s sharp jump in quarterly sales and earnings, while bears flag a share price that has already moved and mixed nine month profits. Which side does the current valuation lean toward?
Most Popular Narrative: 34% Undervalued
HNI’s analyst consensus Narrative on Simply Wall St pegs fair value at about $73.88 per share versus the last close of $49.02. That gap reflects a view that the market is not fully crediting the earnings power behind the recent acquisition and efficiency work.
Expanded efficiency programs that now include Steelcase related savings and broader network optimization, with cumulative benefits expected to exceed US$150 million when mature, are building on earlier Mexico and KII initiatives and can further lift operating margins and non GAAP EPS.
Residential Building Products continues to operate as a high margin platform that is gaining share in remodel and retrofit channels and serving builders more effectively, which can support mid to high teens segment margins and provide a stable earnings base even when new construction is soft.
See why 19 investors see HNI as 34% undervalued.
Result: Fair Value of $73.88 (UNDERVALUED)
Still, the HNI narrative could be tested if hybrid and remote work cap office refresh demand, or if pricing pressure and input costs squeeze margins harder than expected.
Find out about the key risks to this HNI narrative.
Another View on HNI’s valuation
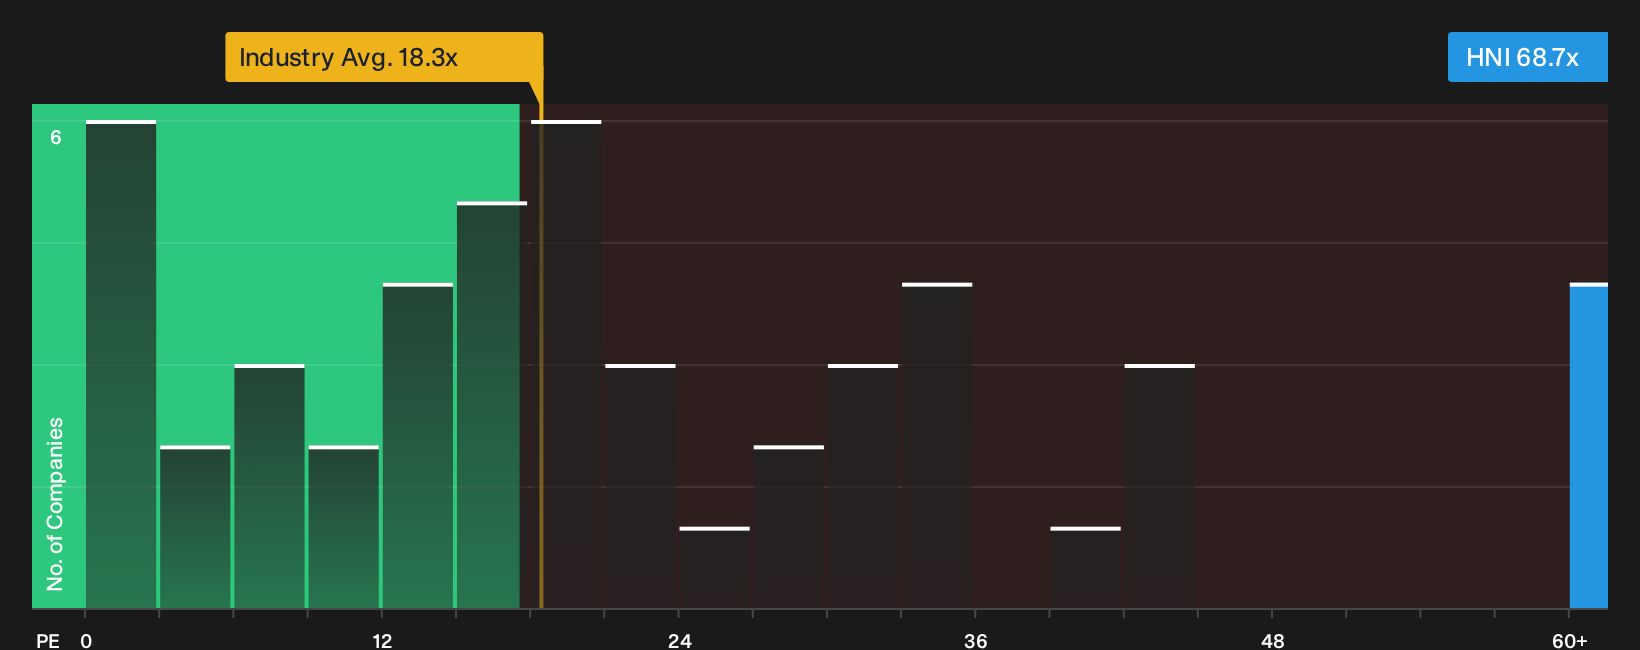
The first fair value story around HNI leans on future earnings power and cash flows. A quick check against the current P/E ratio paints a very different picture. The stock trades on 68.7x earnings versus 18.3x for the US Commercial Services industry and 15.6x for peers, with a fair ratio estimate of 47x. That kind of gap lifts the risk that even good news is already reflected in the multiple. If earnings delivery stutters at all, how much room is there for the valuation to slip back toward that fair ratio level?
See what the numbers say about this price in more detail by digging into our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around HNI’s valuation and operating outlook can feel confusing, so it is important to quickly review the underlying numbers yourself and stress test your thesis against both the 3 key rewards and 5 important warning signs.
Looking for more HNI investment ideas?
If HNI has your attention, do not stop here. Broaden your watchlist with a few focused sets of companies that match different goals and risk levels.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (24 results) that filters for financial strength upfront.
- Hunt for mispriced opportunities by reviewing a focused 32 high quality undervalued stocks that blends quality metrics with potential upside.
- Prioritize income and stability by checking a hand picked 6 dividend fortresses that zeroes in on higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com