
Did Earnings Guidance Just Shift UMH Properties (UMH) Investment Narrative?
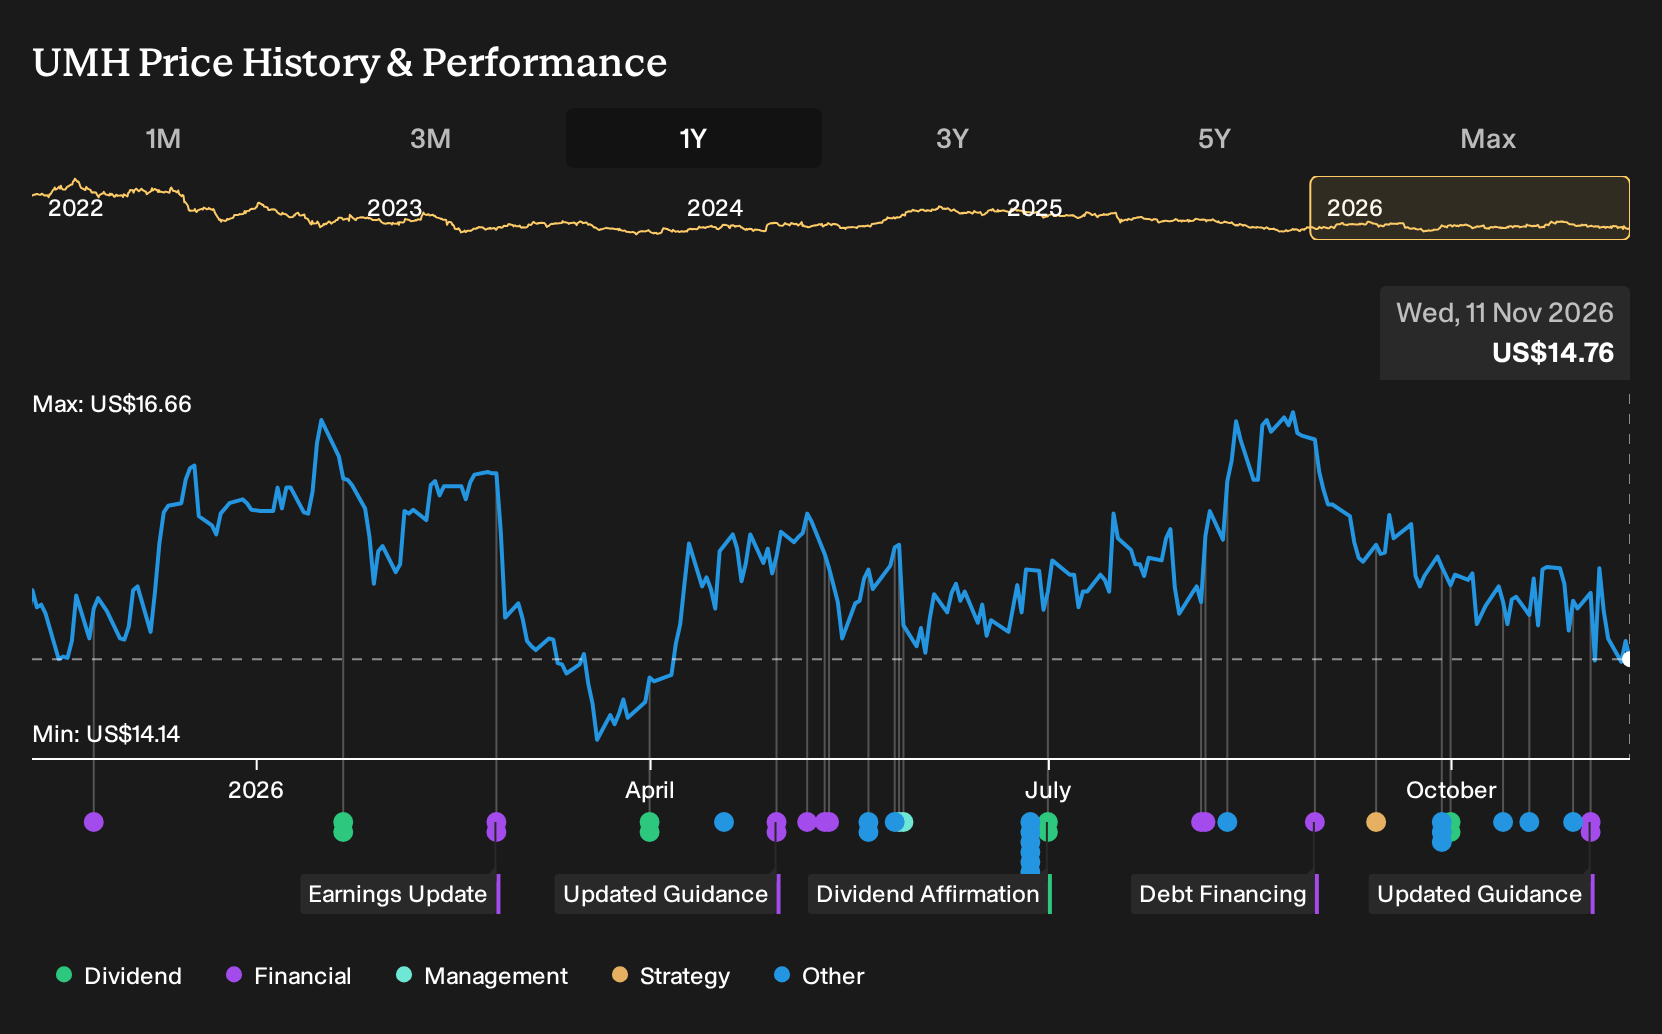
- UMH Properties reported third quarter 2026 revenue of US$74.14 million and net income of US$3.19 million, and issued full year 2026 diluted earnings guidance of US$0.05 to US$0.09 per share.
- The mix of higher revenue alongside lower quarterly profit and a relatively narrow earnings outlook highlights how community level costs and occupancy trends are pressuring UMH Properties' earnings quality.
- We will now assess how UMH Properties' new 2026 earnings guidance might reshape the earlier investment narrative around growth and valuation.
Scan how UMH Properties compares on earnings quality and capital strength by lining it up against a curated list of solid balance sheet and fundamentals (24 results).
UMH Properties Investment Narrative Recap
For UMH Properties, the big picture you would need to believe in is that its manufactured housing footprint, vacant sites and rental home platform can support consistent income growth while community level costs are kept in check. The third quarter 2026 result and the US$0.05 to US$0.09 earnings guidance frame a tighter earnings window, but do not rewrite that core idea.
The more immediate swing factor is whether management can slow expense growth and lift occupancy on existing and expansion sites without putting further stress on margins. The biggest risk right now is that operating costs, including interest, keep running ahead of net income, which the latest quarter’s lower profit makes harder to ignore.
The analyst consensus Narrative on Simply Wall St already highlighted two pressure points that link directly to this update: rising community expenses and activist scrutiny. UMH Properties’ third quarter 2026 figures show revenue of US$74.14 million but net income of US$3.19 million, with basic loss per share from continuing operations, which keeps the focus firmly on earnings quality.
That makes the new full year 2026 diluted earnings guidance especially important for how investors weigh near term catalysts such as infilling vacant sites against risks around cost inflation and dividend coverage. If you are watching this stock, the guidance range now sets a clear reference point for judging whether upcoming quarters show genuine progress on margins and cash generation.
UMH Properties' narrative references analyst expectations for revenue of US$342.0 million and earnings of US$13.7 million by 2029, based on assumed yearly revenue growth of 8.1% and an earnings increase of about US$3.0 million from current earnings of US$10.7 million.
Uncover why UMH Properties' fair value indicates a 28% potential upside to its current price and why that gap could narrow quickly.
Exploring Other Perspectives
The lowest-ranked analysts frame UMH Properties through an interest expense risk. They were assuming earnings of about US$4.2 million by 2029 on roughly US$347.0 million of revenue, well below consensus. That is a far more cautious story than the headline catalysts, and it may shift again once this fresh 2026 guidance is fully absorbed.
Explore 2 other UMH Properties fair value estimates, including one that suggests it could be worth just $18.50!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your UMH Properties research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for UMH Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMH Properties' overall financial health at a glance.
Looking for more investment ideas beyond UMH Properties?
Once you have formed a view on UMH Properties, it can help to place that thesis alongside other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you quickly compare potential holdings against the metrics you care about, rather than scrolling through endless tickers with no structure.
- If you want potential value with quality fundamentals, start by scanning a 32 high quality undervalued stocks that already balance solid cash generation with supportive balance sheets.
- For income focused ideas, you can concentrate on dependable payers through a curated 6 dividend fortresses that may offer higher yields with supporting fundamentals.
- When capital preservation is your first filter, narrow the field using a 30 resilient stocks with low risk scores so you can focus on businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com