
NewAmsterdam Pharma (NAMS) Could Be 59% Undervalued After Strong Q3 Results
How the latest earnings changed the NewAmsterdam Pharma story
NewAmsterdam Pharma (NasdaqGM:NAMS) has just released third quarter numbers that show sales of US$19.16 million and a smaller net loss of US$17.39 million, compared with the same period last year.
Those figures, together with updated nine month results and upcoming conference appearances in Boston and New York this week, give investors fresh information on how the biopharma player is funding and advancing its late stage pipeline.
The latest earnings update and conference schedule have landed against a tough backdrop for shareholders, with the share price at US$20.72 after a 1 day share price return of 8.03% but a year to date share price return that is down 41.14%. That shorter term bounce comes after a 90 day share price return that is down 22.31% and a 1 year total shareholder return that is down 45.91%, although investors who have held NewAmsterdam Pharma over longer periods still show a 3 year total shareholder return a little above a 2x gain.
Compare NewAmsterdam Pharma's earnings shift with other late stage developers by scanning our curated 19 high quality undiscovered gems for biopharma stocks with strong fundamentals that remain off most investors' radar.
NewAmsterdam Pharma now appears to be a more commercially active business, yet the share price is still down sharply this year. Does that gap between operating progress and market performance make the stock look attractively valued, or not?
Most Popular Narrative: 59% Undervalued
On the analyst consensus Narrative on Simply Wall St, NewAmsterdam Pharma screens as materially undervalued, with a fair value of about $50.92 against the last close at $20.72. This places significant importance on how its clinical story develops.
The main requirement for success is that PREVAIL delivers a clinically meaningful cardiovascular outcomes benefit that is consistent with the 21% exploratory MACE reduction seen in BROADWAY and the pooled BROADWAY and BROOKLYN data.
See why 2 investors see NewAmsterdam Pharma as 59% undervalued.
Result: Fair Value of $50.92 (UNDERVALUED)
Still, the NewAmsterdam Pharma story can break if PREVAIL fails to show a clear cardiovascular benefit, or if ongoing losses and equity issuance keep diluting shareholders.
Find out about the key risks to this NewAmsterdam Pharma narrative.
Another view on NewAmsterdam Pharma’s valuation
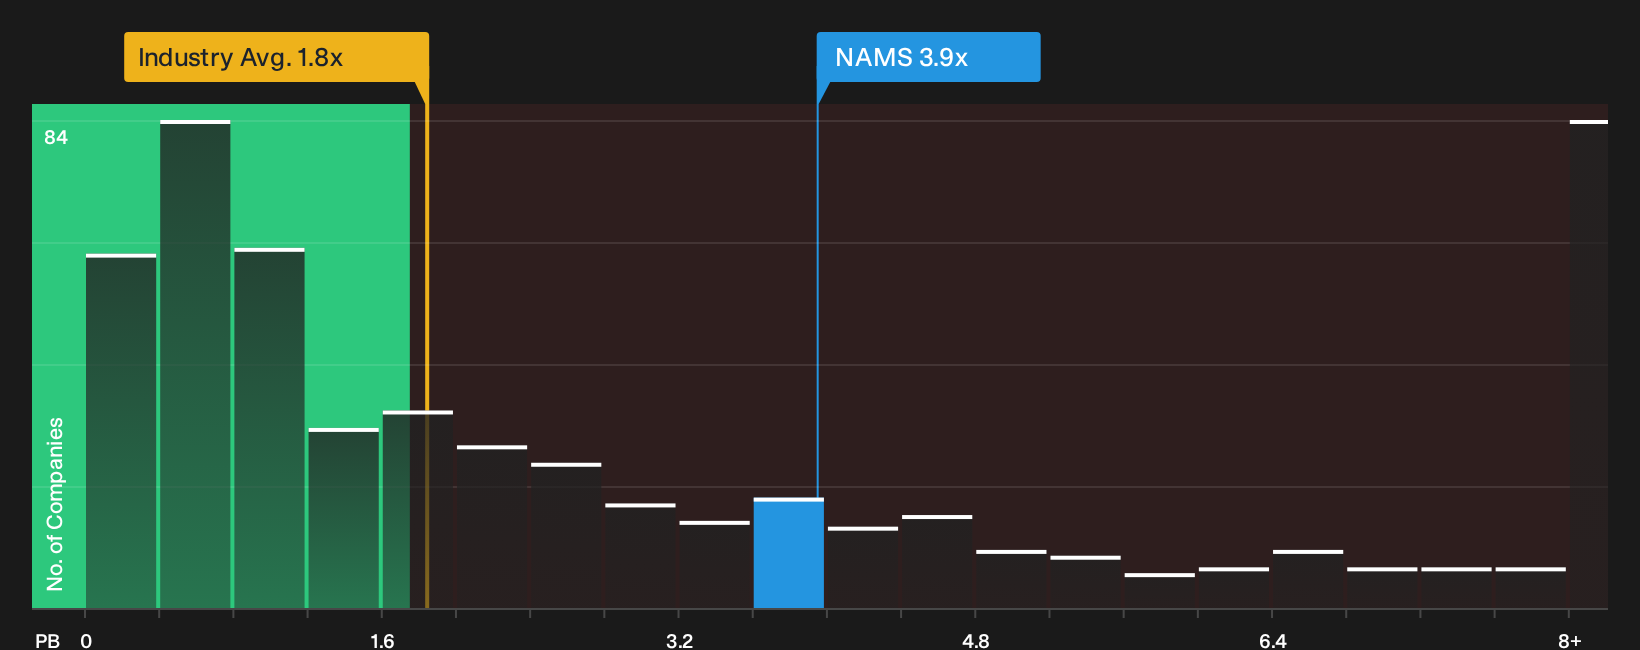
The narrative on NewAmsterdam Pharma leans heavily on future cash flows, yet the market is also putting a rich price on its balance sheet. The stock trades on a P/B of 3.9x compared with 1.8x for the wider US Biotechs group and about 3.8x for peers, which signals less margin for error if the pipeline stumbles.
That kind of premium P/B ratio means even small disappointments on trial data or funding could hit sentiment harder than on cheaper biotech stocks, so it is worth asking how confident you are that current expectations will hold up through the next few data readouts. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of sharp price moves and shifting expectations around NewAmsterdam Pharma leaves you on the fence, move quickly and check the underlying data yourself. Then evaluate the potential upside by reviewing the 3 key rewards.
Looking for more investment ideas beyond NewAmsterdam Pharma?
If NewAmsterdam Pharma has sharpened your focus, do not stop here. Broader research now could be the difference between catching opportunities early or watching them pass.
- Target stronger value potential by scanning stocks that score well on cash flow and balance sheet quality using our 32 high quality undervalued stocks.
- Reduce portfolio stress by focusing on businesses with steadier financial profiles through the 30 resilient stocks with low risk scores.
- Hunt for potential future leaders before they attract crowded attention by checking companies with robust fundamentals in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com