
BRP (TSX:DOO) Could Be 9% Undervalued After Its 1 Month Rebound
BRP (TSX:DOO) has drawn fresh attention after recent trading left the share price at CA$93.32. Investors are weighing that level against the company’s mixed short term returns and stronger performance over the past month.
Recent trading tells a mixed story for BRP, with the share price falling 0.3% on the day and slipping 0.5% over the past week, yet delivering a strong 23.4% 1 month share price return and a 3.9% 1 year total shareholder return. This suggests short term momentum has picked up even though longer term total shareholder returns over three and five years remain in decline.
Compare BRP's recent swing with other potential rebound candidates by scanning our hand picked list of 5 high quality undervalued stocks that pair stronger fundamentals with low expectations baked into the price.
BRP now trades at a sizeable discount to one estimate of fair value and below analyst targets after a sharp 1 month rebound. Is the market's caution still grounded in the fundamentals?
Most Popular Narrative: 8.7% Undervalued
On the analyst consensus Narrative on Simply Wall St, BRP screens as undervalued, with a fair value of CA$102.19 compared with the latest CA$93.32 close, using a 7.15% discount rate to bring future estimates back to today.
The current valuation implies the market is discounting BRP's raised FY27 guidance and positions in key powersports categories, which aligns with this narrative's view that the stock is undervalued and pricing in a cautious outlook.
See why 23 investors see BRP as 9% undervalued.
Result: Fair Value of CA$102.19 (UNDERVALUED)
Still, BRP’s tariff exposure and softer personal watercraft demand could pressure margins and unit volumes, which would challenge the current undervaluation narrative.
Find out about the key risks to this BRP narrative.
Another View on BRP’s Valuation
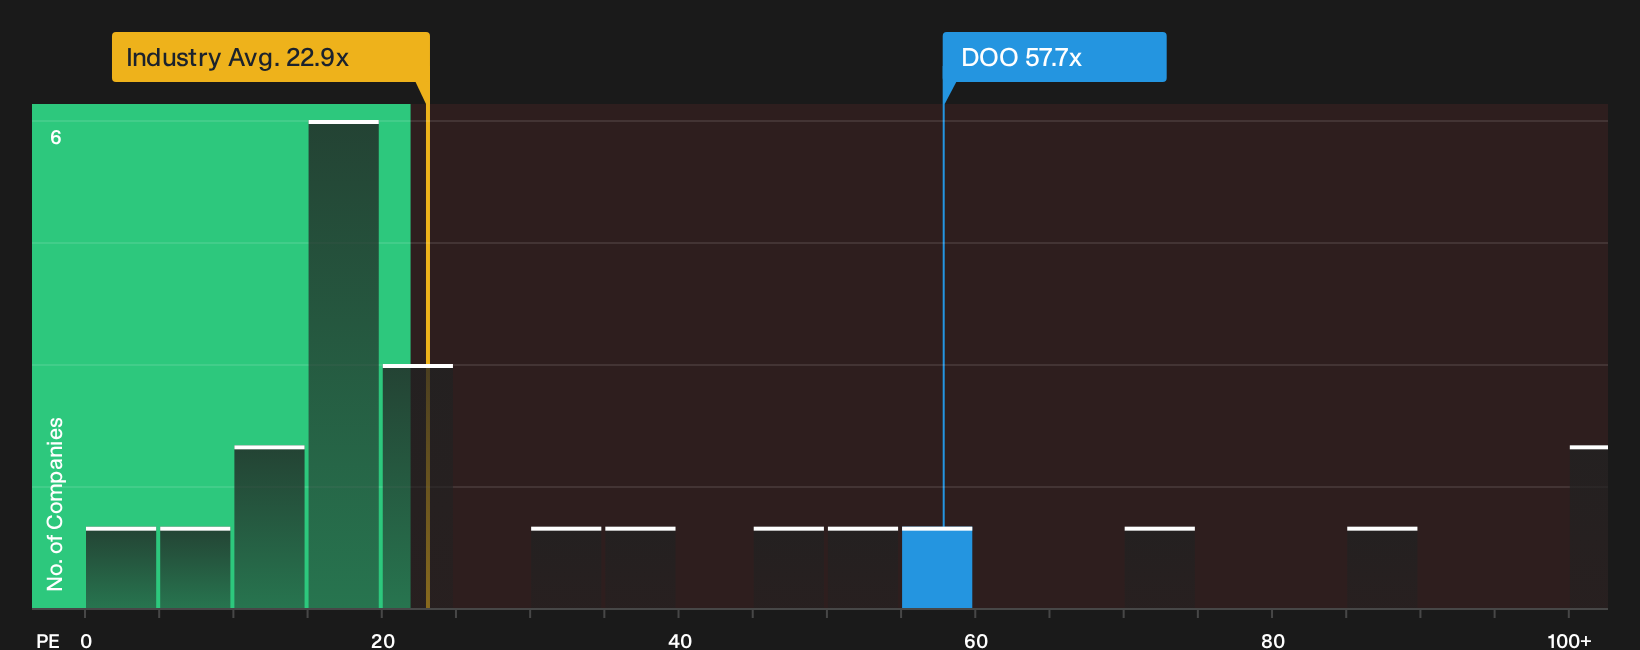
The first narrative leans on fair value and analyst targets to argue BRP looks undervalued at CA$93.32. A different lens tells a tougher story. On a P/E of 57.7x, the stock trades well above peers at 33.5x and the North American Leisure industry at 22.9x, and even above a fair ratio of 46.2x. That premium raises a simple question for you as an investor: Is this pricing in too much hope relative to current earnings quality and recent profit pressure, or is it justified by the growth narrative?
Before leaning too heavily on earnings based multiples for BRP, it can help to step back and ask whether the current P/E premium leaves much room for error. This is exactly the context provided in the See what the numbers say about this price — find out in our valuation breakdown..
To see how BRP’s valuation stacks up visually against its sector and peers on this measure, you can review the comparison in
Next Steps
Does the mixed tone around BRP leave you cautious or curious? Act while the data is fresh and form your own view by weighing its 2 key rewards and 3 important warning signs.
Looking for more ideas beyond BRP?
If BRP has sparked your interest, do not stop there. Broader context from other opportunities can sharpen your conviction and highlight gaps in your current portfolio.
- Target dependable compounding by reviewing income candidates in the 3 dividend fortresses.
- Hunt for quality businesses the market may be overlooking by scanning the 7 high quality undiscovered gems.
- Reduce portfolio stress by focusing on resilience first with the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com