
Home Depot (HD) Stock Looks Overvalued As Cash Flow Lags Expectations
Home Depot shares have seen mixed momentum, with a sharp 20.9% rise over the past month but a small decline over the past week. This puts fresh focus on whether the current market price lines up with the cash the business can generate. Investors now face a simple question: Do the stock's cash flows support where the market has taken it?
- Over the past 3 years, Home Depot has delivered a total return of 23.1%, which makes the link between its share price and its underlying cash generation more important for anyone thinking about what happens next.
- Recent political developments that supported housing related companies and pushed Home Depot sharply higher may shape expectations for future demand, which can feed directly into the timing and durability of the retailer's cash flows.
- Prefer to judge Home Depot on earnings? See why Home Depot's 24.6x P/E tells a different valuation story.
The issue now is whether the current US$351.31 share price is justified by Home Depot's cash flows when viewed through a Discounted Cash Flow (DCF) estimate of intrinsic value.
If you want more context around Home Depot and housing related stocks, it can help to compare its setup against 42 power grid technology and infrastructure stocks
Does Home Depot Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on the cash Home Depot can return to shareholders over time. Over the latest twelve months, the retailer generated roughly $15.2b in free cash flow, and the model extends that stream out with a 2 Stage Free Cash Flow to Equity framework that tapers growth gradually over the coming decade.
Those projections assume Home Depot keeps producing sizeable, positive free cash flow rather than swinging between gains and losses, which is consistent with a mature, cash generative retailer. Even so, the DCF output sits meaningfully below the current $351.31 share price. This suggests the recent rally has pushed expectations ahead of what these projected cash flows imply. Because the post election surge in housing related stocks has already lifted sentiment and the share price, the model points to a market that is pricing in a lot of good news on future demand. Find out what Home Depot could be worth using our Discounted Cash Flow (DCF) estimate.
The Home Depot Narrative: What Would Justify Today's Price?
Narratives link the valuation puzzle around Home Depot to specific assumptions about its future growth, margins and earnings that would need to hold for the shares to be worth materially more or less than today’s price, and they sit on Simply Wall St’s Community page. Rather than relying on a single multiple or model line, each one lays out the key drivers behind its fair value view so you can follow those assumptions against actual results over time.
One of the top narratives on Home Depot: 7% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"A key factor is whether Home Depot can translate its investments in Pro centric ecosystems, faster delivery, and AI enabled productivity into durable gains with professional customers…"
Discover why this Narrative puts Home Depot at 7% undervalued.
One more piece on Home Depot before you decide what to do
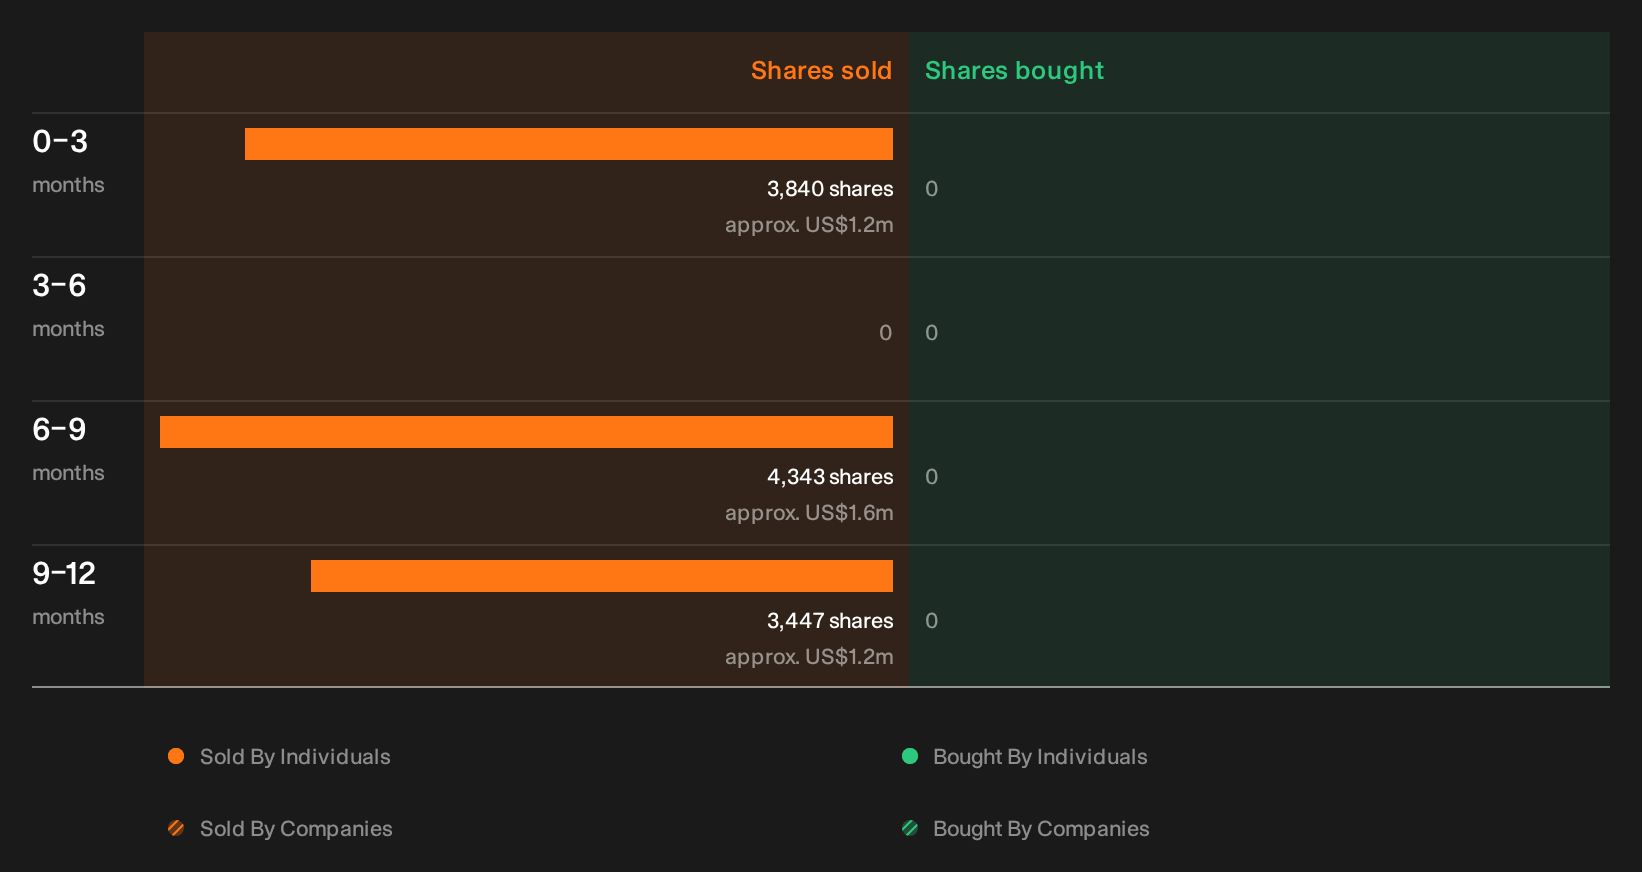
Before acting on any conclusion about Home Depot, it is worth checking that recent trades by key insiders line up with your expectations for alignment and timing. See the recent insider selling flagged for Home Depot.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com