
Why Did FLSmidth (CPSE:FLS) Shares Climb After Its Latest Update?
FLSmidth (CPSE:FLS) is back in focus after its Q3 2026 update, where management reported higher order intake, organic revenue growth of 6%, and an Adjusted EBITA margin of 16.3%.
The Q3 update has come alongside a sharp shift in sentiment, with FLSmidth’s share price up 22.4% over the past 90 days and 34.2% year to date, while total shareholder return sits at 41.3% for 1 year and 159.7% across 5 years. This points to momentum that has been building rather than fading.
Scan beyond FLSmidth and see how other industrial players with strong recent momentum and cash generation stack up in our hand picked list of 196 high quality undervalued stocks
FLSmidth’s valuation gap now looks more exposed, with the share price at DKK 604, an analyst target at DKK 668.75, and intrinsic estimates implying a roughly 31% discount. How much of the recent momentum is already reflected in the price?
Most Popular Narrative: 9% Undervalued
On the analyst consensus Narrative on Simply Wall St, FLSmidth screens as undervalued, with a fair value of DKK 660.42 versus the last close at DKK 604. The gap reflects a view that the current mining focused model and margin profile could support a higher valuation than the market is pricing in today.
The main thing that has to go right is continued execution in Services and Pumps, Cyclones & Valves so that strong order intake, margins and the turnaround in Products translate into sustained cash generation despite current working capital pressure.
The current valuation implies the market is cautious that FLSmidth’s improved margins, mining focus and sizeable share buyback can be maintained, which leaves room for upside if the company’s profitability and capital returns are sustained.
See why 9 investors see FLSmidth as 9% undervalued.
Result: Fair Value of DKK 660.42 (UNDERVALUED)
Still, the FLSmidth story depends on Products avoiding another slump and on today’s working capital drag on cash flow not becoming a more persistent constraint.
Find out about the key risks to this FLSmidth narrative.
Another Take On FLSmidth’s Valuation
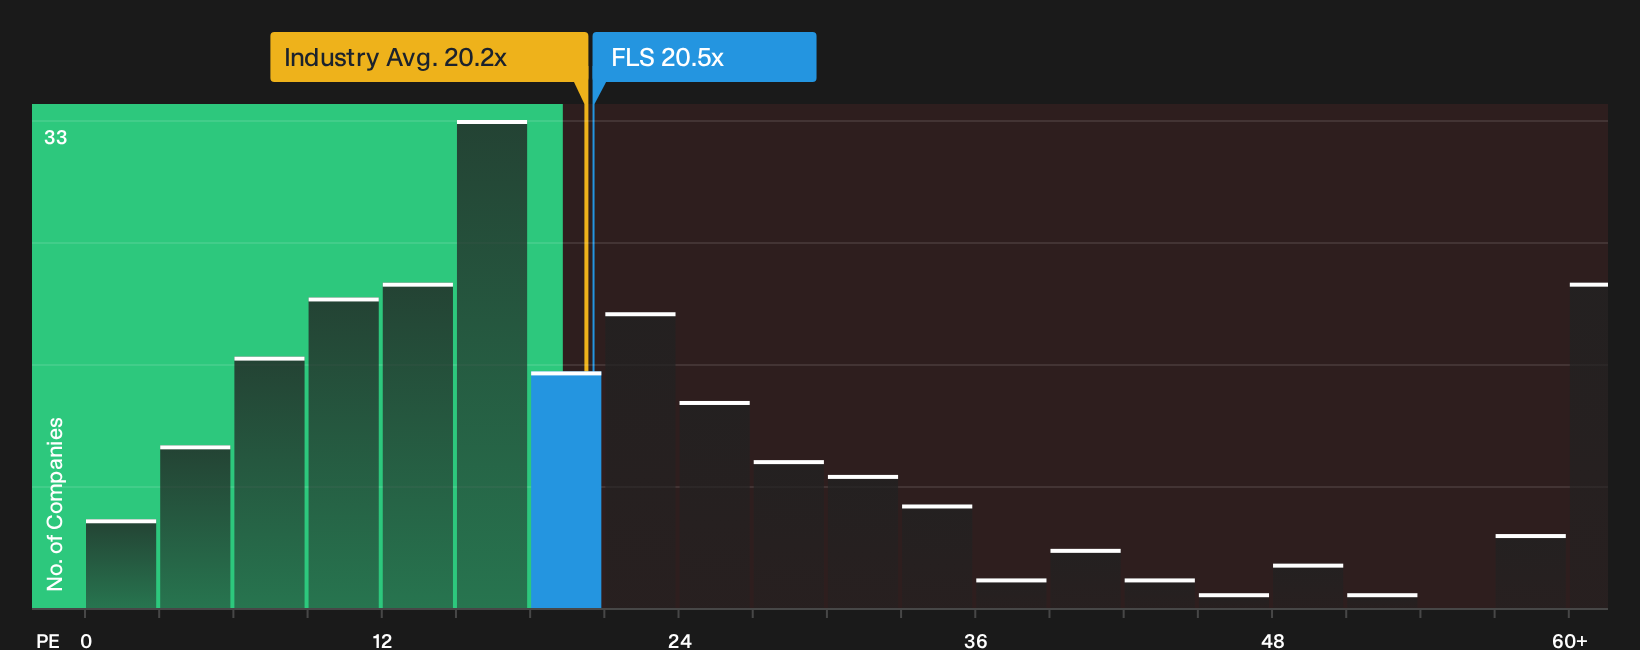
The earlier view leaned on future earnings and cash flows to argue FLSmidth looks cheap. Flip the lens to simple pricing metrics and the story looks less generous. On a P/E of 20.5x, the stock trades slightly above the European Machinery group at 20.2x and above its own fair ratio of 14.6x.
That gap suggests investors are already paying a premium versus peers and the level the market could move towards over time, which increases valuation risk if execution or cash conversion fall short of expectations. With one framework flagging undervaluation and the other pointing to a rich multiple, which signal do you trust more right now?
For a closer look at how this earnings multiple stacks up, and what it could mean if the share price gravitates toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this FLSmidth story looks promising, yet some pieces clearly worry investors, so move fast and test the numbers yourself. To see both sides laid out in one place, weigh up the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond FLSmidth?
Do not stop your research with FLSmidth. The strongest portfolios often come from consistently scanning for fresh ideas that fit clear rules on value, resilience, and income.
- Target potential mispricing by reviewing companies that screen as high quality yet unloved in our hand picked list of 196 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances in this curated list of solid balance sheet and fundamentals (194 results).
- Boost your income ideas by zeroing in on higher yielding payout candidates through our focused set of 216 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com