
Alnylam Pharmaceuticals (ALNY) Is Up 5.4% What’s Changed After Five Year Drug Data
- Alnylam Pharmaceuticals reported new five year HELIOS-B data showing continuous AMVUTTRA treatment was associated with lower all-cause mortality and recurrent cardiovascular events, preserved quality of life and stable cardiac biomarkers in transthyretin amyloidosis with cardiomyopathy.
- The same dataset, along with exercise testing and real world evidence, highlighted the clinical importance of earlier AMVUTTRA use and its role across both monotherapy and combination settings, which feeds directly into Alnylam Pharmaceuticals' ATTR franchise execution story.
- We will look at how Alnylam Pharmaceuticals' investment narrative is shaped by these long term AMVUTTRA outcomes in ATTR cardiomyopathy.
Alnylam Pharmaceuticals Investment Narrative Recap
For an investor to stay with Alnylam Pharmaceuticals, the thesis usually rests on AMVUTTRA anchoring a transthyretin franchise while the broader RNAi pipeline adds new revenue legs over time. The analyst consensus Narrative on Simply Wall St leans on that idea. The new five year HELIOS B data strengthens the operational story around AMVUTTRA, but the near term focus still sits on TTR franchise execution after the recent guidance cut.
The biggest swing factor right now is whether management can keep AMVUTTRA demand and pricing resilient enough to support the reiterated 2026 net product revenue range of US$4.7b to US$5.1b while funding heavy R&D. The main risk remains pressure on realized pricing and high spend if large cardiovascular programs like zilebesiran take longer to translate into meaningful sales.
The US$1.0b share repurchase authorization announced on 4 November 2026 is the announcement that most directly intersects with this AMVUTTRA update. Management plans to buy back about US$500m of stock by the end of 2026 and the rest during 2027, subject to market conditions. That capital return plan now sits alongside new long term ATTR cardiomyopathy data that supports the AMVUTTRA label and usage breadth.
For you, the link between the buyback and the clinical news is mainly about confidence in cash generation from the TTR franchise and the wider portfolio. Execution risk does not go away, particularly around net pricing and ongoing R&D intensity, but the combination of strong recent earnings, reiterated revenue guidance and a sizable repurchase program frames how management is choosing to balance investment in RNAi programs with shareholder returns.
Alnylam Pharmaceuticals' current analyst framework points to US$8.7b in revenue and US$1.9b in earnings by 2029. This outlook is built on 20.0% yearly revenue growth and an earnings decline of US$0.8b from US$2.7b today.
Uncover how Alnylam Pharmaceuticals' fair value indicates a 107% potential upside to its current price before the gap between story and valuation narrows.
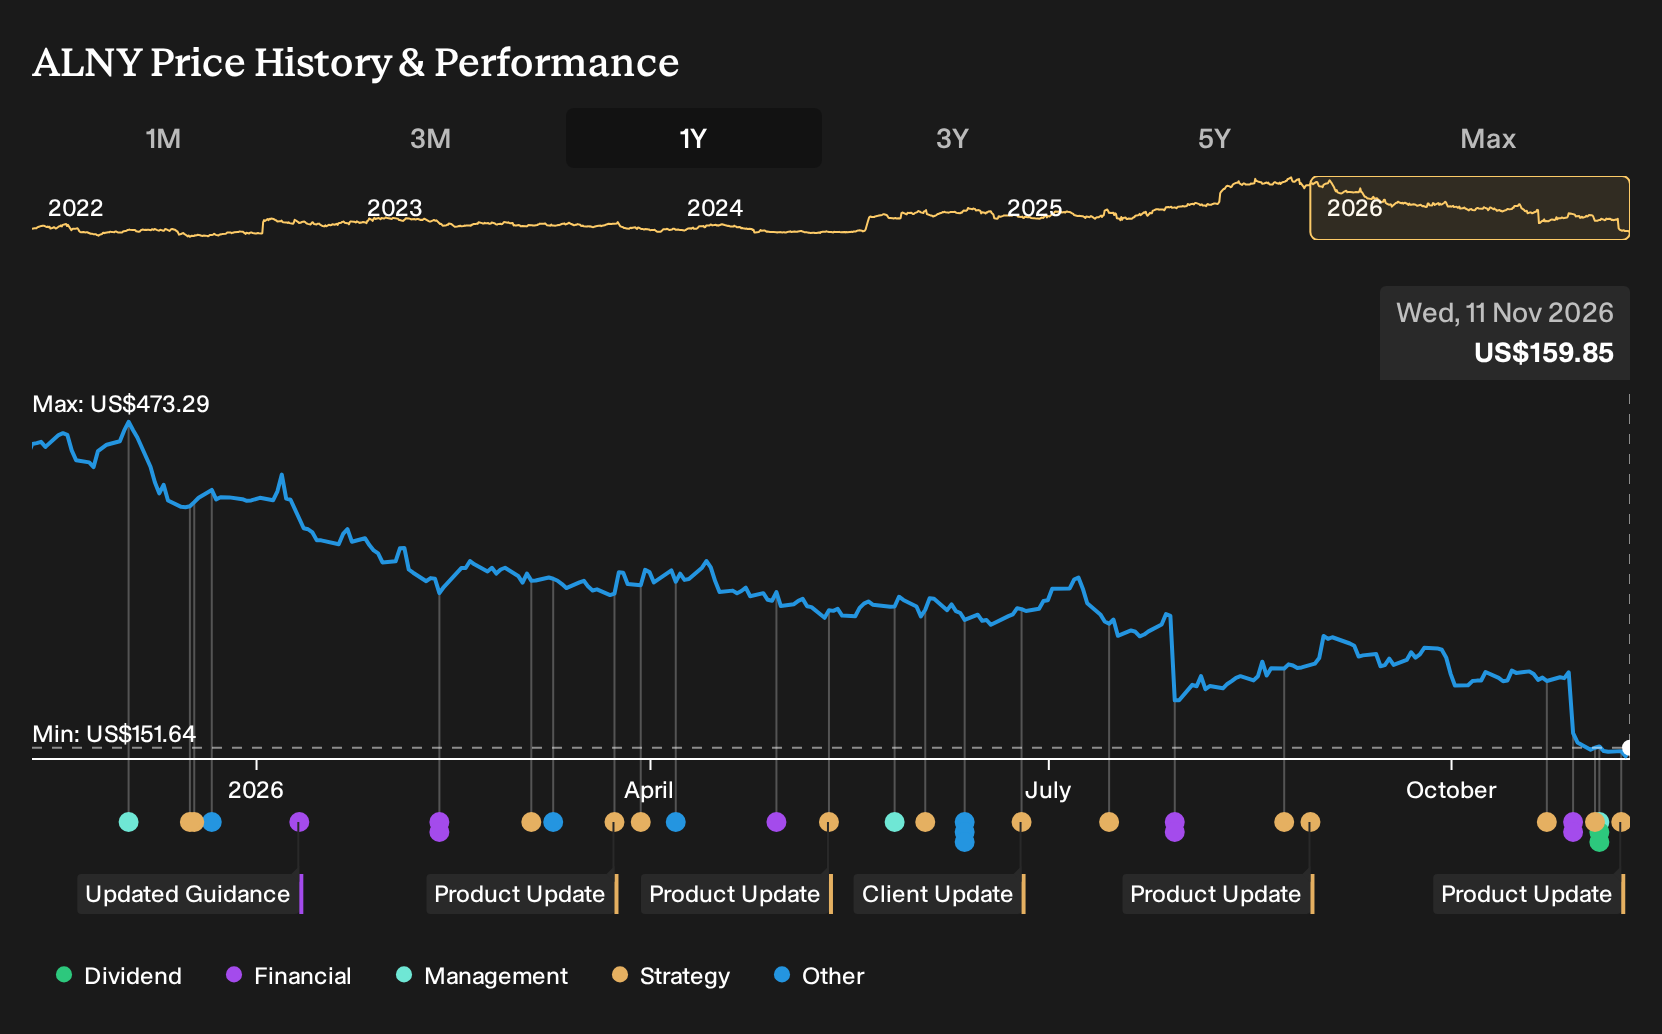
Exploring Other Perspectives
One alternate angle focuses on legal and execution risk rather than the AMVUTTRA data itself. The most cautious analysts already framed Alnylam Pharmaceuticals as fairly valued, assuming revenue of about US$7.0b and earnings near US$1.2b by 2029. Those expectations were set before this week’s HELIOS B update, so their storyline may shift.
Explore 4 other Alnylam Pharmaceuticals fair value estimates, including one that suggests it could be worth just $199.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alnylam Pharmaceuticals research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alnylam Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alnylam Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Alnylam Pharmaceuticals?
If the Alnylam Pharmaceuticals story has sharpened your view on risk, reward and timelines, it can help to compare it with other opportunities that match your preferred style of investing. The Simply Wall St Screener lets you filter for traits that matter to you, whether that is resilience, income or underappreciated potential.
- For investors who care most about financial strength and balance sheet resilience, review the list of solid balance sheet and fundamentals (24 results) and see which businesses fit that profile.
- If you prefer situations where expectations look modest relative to fundamentals, scan the 19 high quality undiscovered gems and see which stories the market may not be fully pricing in yet.
- For a more cautious approach that still targets equity returns, filter for companies in the 30 resilient stocks with low risk scores and see which stocks line up with your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com