
Is Firefly Aerospace (FLY) Too Expensive After Its 75% Jump?
Firefly Aerospace has seen its share price move sharply in recent sessions, which puts fresh attention on a simple question for investors who care about fundamentals. Does the current valuation rest on sales that can support this price, or has the stock moved ahead of what its revenue base can reasonably justify today?
- With a 75.4% gain over the past week, Firefly Aerospace stock has rapidly repriced and put its sales based valuation framework under much closer scrutiny.
- New long term contracts, including NASA lunar delivery work and a US$1.3b engine deal with AST SpaceMobile, can shape how investors think about future revenue scale and how much sales they are effectively paying for right now.
- There is a second opinion on Firefly Aerospace worth weighing. See what analysts think Firefly Aerospace's shares could be worth.
The issue now is whether the recent share price level for Firefly Aerospace is adequately backed by the sales it generates and the revenue it is expected to produce.
If you are weighing whether Firefly Aerospace's recent move is justified by its sales, it can help to compare that question across 32 high quality undervalued stocks.
Is Firefly Aerospace Getting Expensive on Sales?
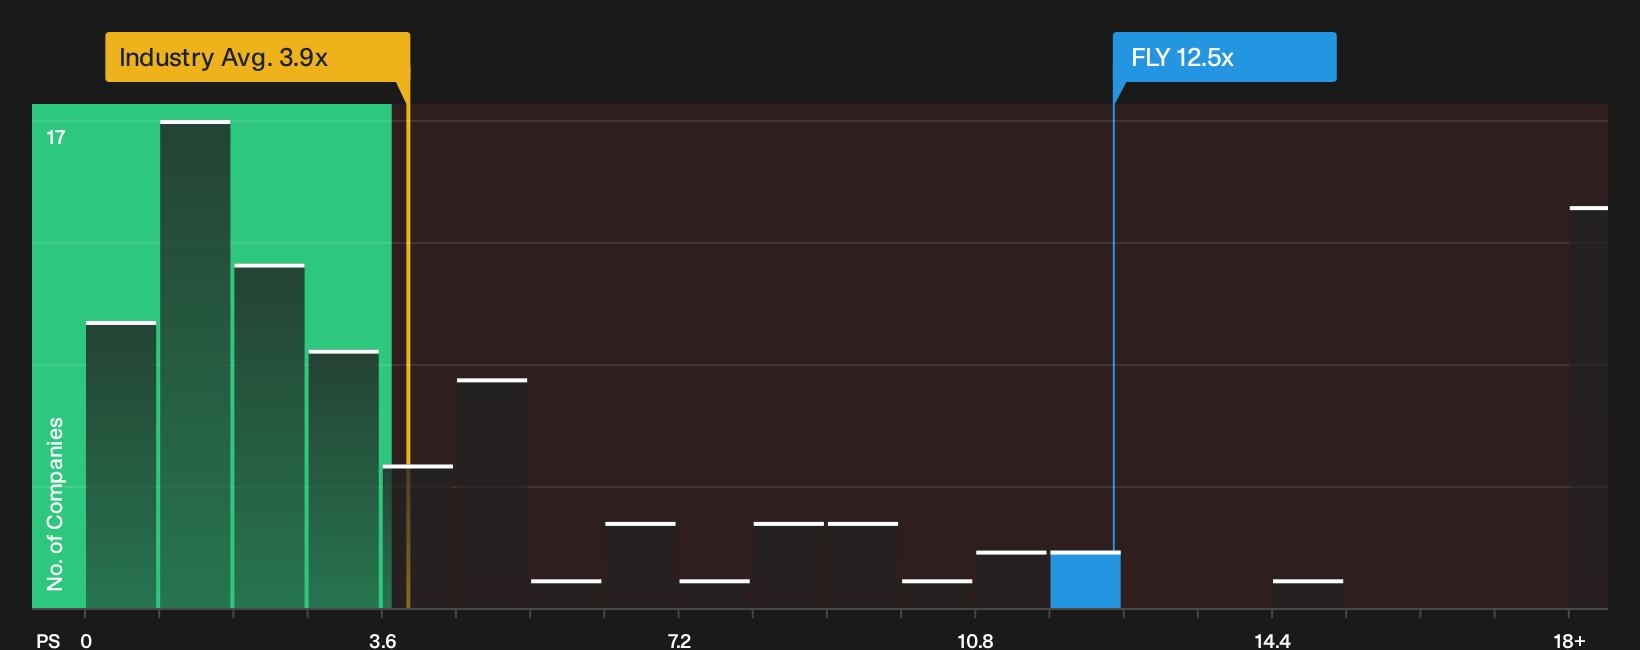
P/S is the cleanest way to look at Firefly Aerospace right now because losses mean earnings based ratios such as P/E do not give a clear signal. On this measure, the stock trades on a P/S of about 12.5x, which is well above the Aerospace & Defense industry average of roughly 3.9x and also higher than the peer group at about 2.5x.
That premium is larger than the tailored fair multiple implied by Firefly Aerospace's fundamentals, so on this framework the shares screen as overvalued on sales. Because the business has recently signed sizeable contracts like the US$1.3b AST SpaceMobile engine deal, the P/S ratio is effectively asking you to pay a much higher price per dollar of current revenue than the typical aerospace contractor. Explore the numbers behind Firefly Aerospace's P/S valuation.
The Firefly Aerospace Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Firefly Aerospace's valuation puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to end up worth materially more or less than today's market price, on the Community page. Instead of a single ratio or model output, each narrative lays out the assumptions that underpin its fair value view so you can later compare those inputs with actual results as they arrive.
Bulls see Firefly Aerospace turning its contract pipeline into something bigger, while bears focus on whether losses and dilution keep dominating the story.
Bull case: 41% undervalued
The bullish analyst Narrative on Simply Wall St leans on spacecraft, software and lunar work to argue Firefly Aerospace is being underappreciated.
"The new Cedar Park cleanroom that can support assembly and testing of up to 12 spacecraft at once gives Firefly Aerospace room to layer more Blue Ghost and Elytra missions…"
Discover why this Narrative puts Firefly Aerospace at 41% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St focuses on execution risk, funding needs and launch cadence to say Firefly Aerospace is closer to fully priced.
"While a record backlog and substantial liquidity provide Firefly Aerospace with visibility and funding for multiple programs, the continued rise in stock based compensation and guided share count increases…"
Explore why this Narrative puts Firefly Aerospace at roughly fairly valued.
One more Firefly Aerospace signal worth checking before you make a move
Before you lean too heavily on today’s Firefly Aerospace valuation, it can help to see how professional forecasters map out its revenue and profit profile a few years from now. Explore where analysts expect Firefly Aerospace to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com