
Should Mixed Earnings And 2027 Guidance Require Action From Scotts Miracle Gro Stock Investors?
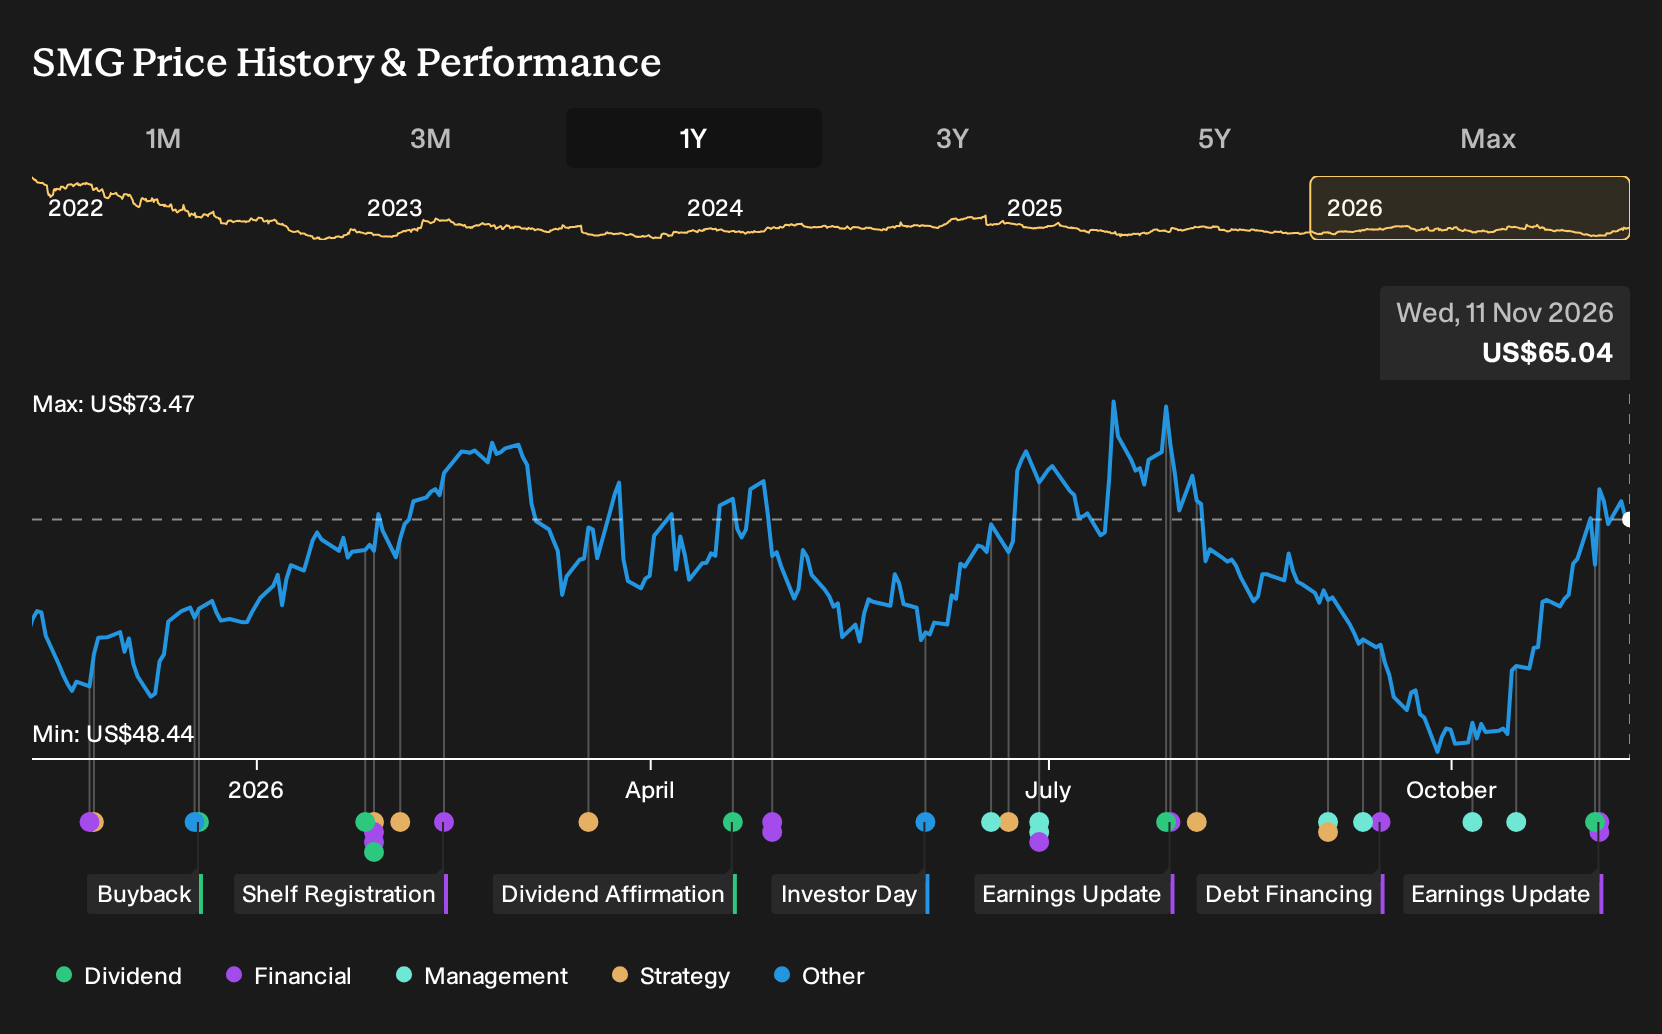
- Scotts Miracle-Gro reported fourth quarter 2026 sales of US$302.9 million and a net loss of US$121.9 million, alongside full year sales of US$3.29 billion and net income of US$103.9 million.
- The company paired these mixed results with fiscal 2027 guidance calling for 2% to 4% net sales growth, while its board affirmed a quarterly cash dividend of US$0.66 per share payable in December 2026.
- We will now look at how Scotts Miracle-Gro's new 2027 sales guidance could reshape the existing investment narrative around margins and growth.
Scan beyond Scotts Miracle-Gro and spot other income-focused opportunities by lining up its dividend story alongside our hand-picked 6 dividend fortresses.
Scotts Miracle-Gro Investment Narrative Recap
To own Scotts Miracle-Gro, you basically need to believe its lawn and garden brands can turn modest top line progress into healthier profitability despite cost and weather noise. The analyst consensus narrative on Simply Wall St leans on cost savings, tech upgrades and product mix to do that. The new 2% to 4% net sales growth outlook for fiscal 2027 signals steady, not dramatic, momentum.
The short term swing factor still looks like whether management can blunt the roughly US$100 million commodity headwind expected for 2027 through pricing and efficiencies. Weather driven demand and ongoing legal investigations remain the bigger risks, and this latest update does not meaningfully change that risk profile.
The clearest piece of recent news for that thesis is the fiscal 2027 guidance calling for 2% to 4% net sales growth. That range lines up with analysts expecting low single digit revenue growth and puts the focus squarely on execution in areas like supply chain technology, automation and SAP S/4HANA deployment to protect margins.
On the other side of the ledger, the board’s decision to affirm a US$0.66 quarterly dividend while reporting a fourth quarter loss and weaker earnings coverage keeps attention on cash generation, debt and dividend sustainability. For catalysts to matter, you want to see those cost programs, e commerce channels and product launches feed through to consistent free cash flow that supports both the payout and balance sheet repair.
Scotts Miracle-Gro's narrative projects US$3.5b revenue and US$301.4 million earnings by 2029. This implies 2.4% yearly revenue growth and an earnings increase of about US$106.5 million from the current US$194.9 million level.
Uncover how Scotts Miracle-Gro's fair value indicates a 15% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Black Kow acquisition as the real swing factor for Scotts Miracle-Gro, with their pre news models pointing to revenue of about US$3.6b and earnings near US$277.1 million by 2029. Those forecasts assume stronger product mix benefits, and this new guidance could either reinforce or challenge that view.
Explore 3 other Scotts Miracle-Gro fair value estimates, including one that suggests as much as 61% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Scotts Miracle-Gro research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Scotts Miracle-Gro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Scotts Miracle-Gro's overall financial health at a glance.
Looking for more investment ideas beyond Scotts Miracle-Gro?
If the Scotts Miracle-Gro story has sharpened your thinking, broaden your watchlist by lining it up against other stocks that fit different risk and return profiles using the Simply Wall St Screener.
- For investors hunting for potential mispricing, compare your thesis against a 32 high quality undervalued stocks that pair stronger fundamentals with what could be attractive entry points.
- If capital preservation sits high on your list, consider balancing Scotts Miracle-Gro with a 30 resilient stocks with low risk scores that score well on resilience and downside protection.
- To widen your opportunity set beyond widely followed tickers, scan a 19 high quality undiscovered gems that combine quality metrics with relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com