
How Strong Quarterly Earnings Will Impact Clorox Stock Investors
- Clorox reported first quarter results for the period ended September 30, 2026, with sales of US$1,905 million, net income of US$170 million and basic and diluted EPS from continuing operations of US$1.39, compared with US$1,429 million in sales, US$80 million in net income and EPS of US$0.65 a year earlier.
- Management has paired this earnings update with a planned CEO transition to Fabian Garcia in January 2027. This places fresh leadership with deep global consumer products experience over a business that is currently reporting higher quarterly sales and profitability than the prior year.
- We will now look at how Clorox's first quarter profitability reshapes its investment narrative and the balance between risk and potential reward.
Compare Clorox's earnings story and leadership change with a curated set of peers by scanning list of solid balance sheet and fundamentals (24 results).
Clorox Investment Narrative Recap
To own Clorox, you need to believe the business can keep turning brands in cleaning, health and household staples into steady cash generation even as consumers trade into value channels. The latest quarter’s higher sales and earnings give that story fresh support, but do not remove the pressure from sluggish category growth and value seeking shopping behavior.
The key short term swing factor remains how well Clorox manages cost inflation and executes on its ERP and productivity agenda. Rising input and supply chain costs guided at slightly over US$200 million for fiscal 2027 still look like the main risk to margins, financial flexibility and the already high dividend payout.
The CEO transition to Fabian Garcia from January 5, 2027 is the most relevant development for thinking about those catalysts. Garcia brings more than four decades of global consumer products experience across Unilever, Colgate Palmolive, Revlon and Procter & Gamble, which gives him deep exposure to categories similar to Clorox’s core franchises.
For you as a shareholder, the question is execution. Investors watching the analyst consensus Narrative on Simply Wall St may now focus on whether the new leadership team can drive ERP optimization, integration of GOJO and the wider health and hygiene platform, and SG&A productivity, while still addressing debt coverage, dividend sustainability and value seeking demand without eroding brand equity.
Clorox's current analyst storyline points to revenue of US$8.1b and earnings of US$789.0 million by 2029, based on a forecast 6.3% yearly revenue growth rate and an increase in earnings of about US$202.0 million from US$587.0 million today.
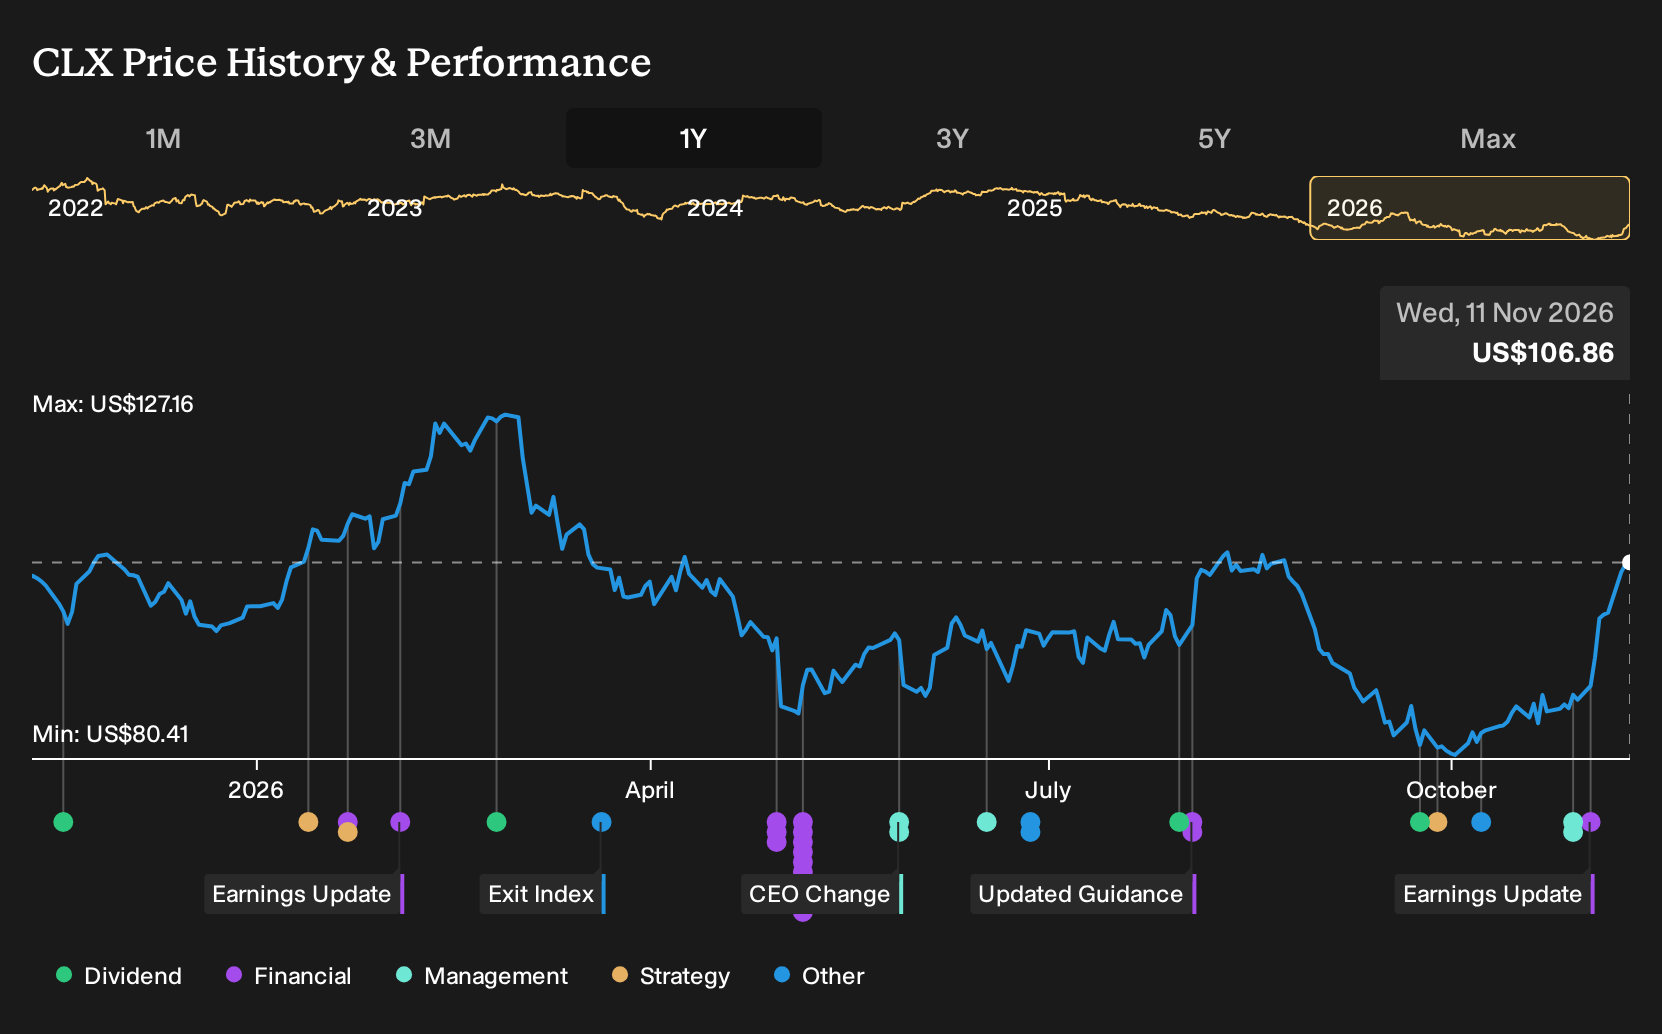
Uncover why Clorox's fair value indicates a 9% potential downside to its current price, highlighting a valuation gap that leaves little room for error.
Exploring Other Perspectives
Some of the lowest analysts lean heavily on free cash flow risk rather than earnings growth. Before this Clorox update, they were only penciling in about US$8.0b of revenue and US$745.1 million of earnings by 2029, which reflects a more cautious story you can compare against other viewpoints in the screener.
Explore 7 other Clorox fair value estimates, including one that suggests there may be as much as 28% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Clorox research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Clorox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Clorox's overall financial health at a glance.
Looking for more investment ideas beyond Clorox?
If you want to pressure test your view on Clorox against other opportunities, cast a wider net using the Simply Wall St Screener to see how different businesses stack up on quality, value and resilience.
- For investors who want income with a margin of safety, scan for dividend payers that combine yield with balance sheet support using the 6 dividend fortresses.
- If you are hunting for quality at a reasonable entry point, compare Clorox with a broader set of potentially mispriced opportunities through the 32 high quality undervalued stocks.
- When capital preservation ranks high on your priority list, focus on businesses with stronger financial footing and more robust fundamentals via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com