
Missed Pebblebrook Hotel Trust's 97% Run? What Holders Had To Believe
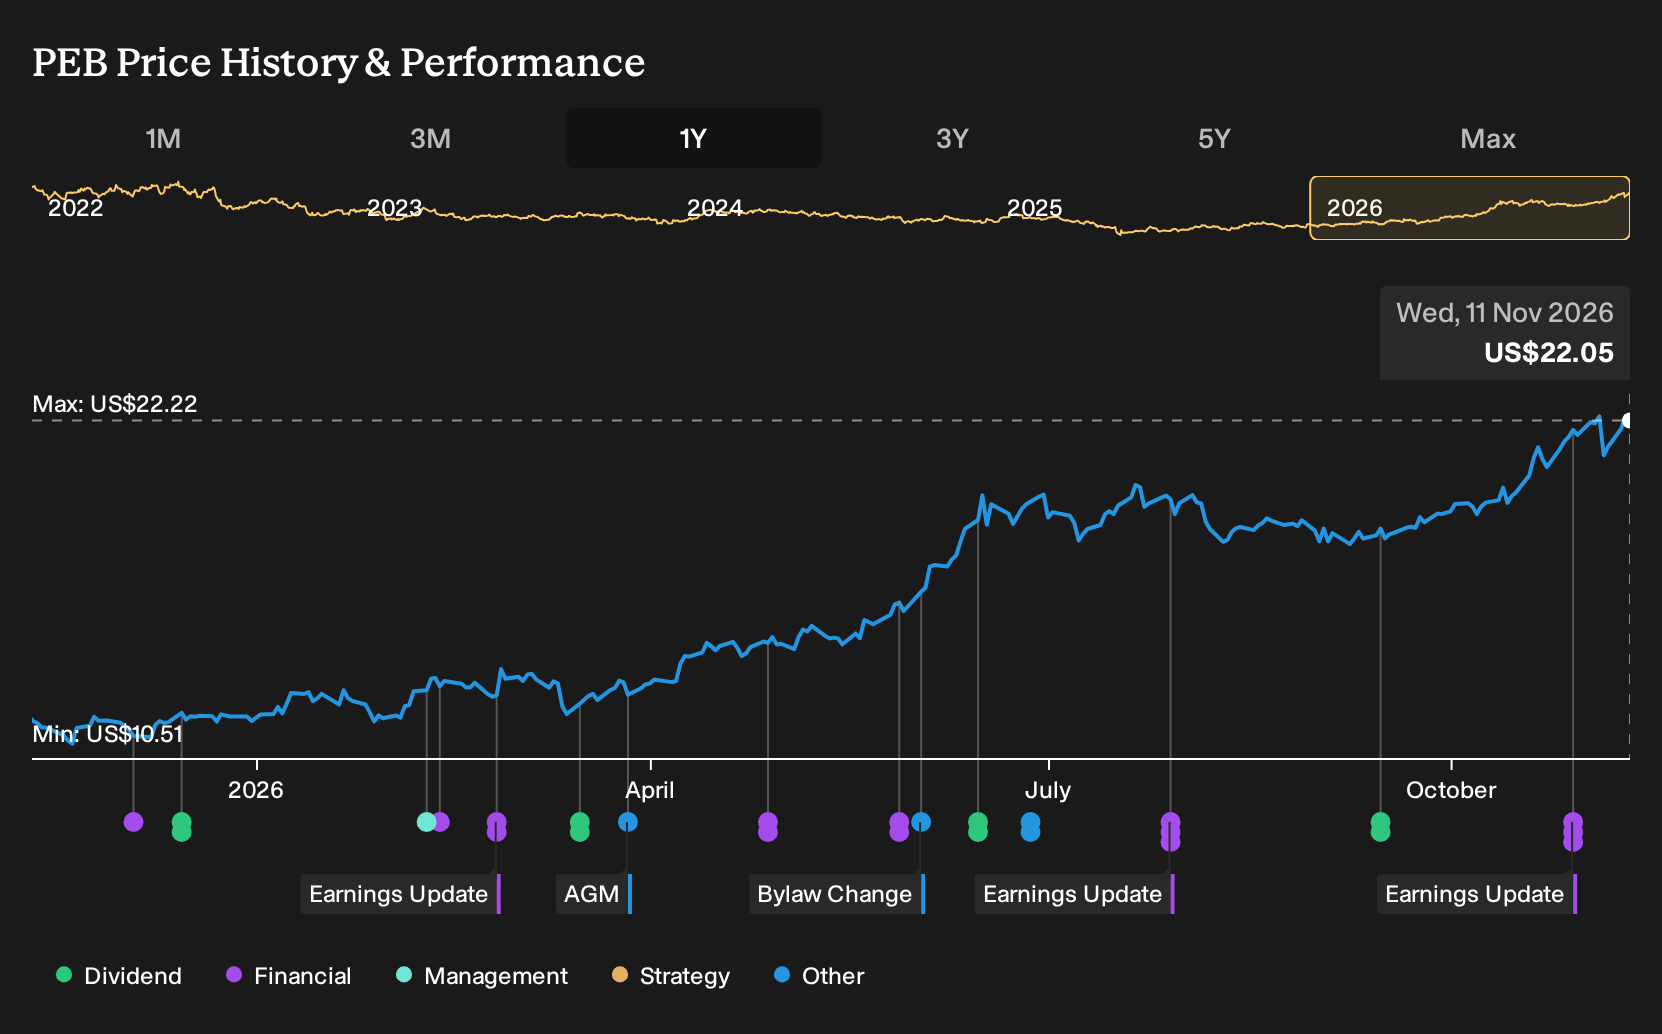
Pebblebrook Hotel Trust spent this past year in the headlines for selling underperforming hotels, posting mixed quarterly results, and lifting earnings guidance even as net margin in Q3 2026 sat at a loss of 15.7%. Holding Pebblebrook Hotel Trust over the past year would have returned 96.5%, including dividends. If you had been deciding on 11 November 2025, what would you have needed to believe about urban hotels, AI efficiencies, and REIT balance sheets to support that outcome?
If the move has made Pebblebrook Hotel Trust harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Argument You Would Have Been Weighing On Pebblebrook Hotel Trust
The shares cost US$11.32 at the start of the period. Anyone looking at Pebblebrook Hotel Trust then had to decide which story about urban hotels and technology sounded more convincing.
On the optimistic side, one narrative saw fair value at US$12.58, a price implied by assumptions that automation and AI could lift profit margin to 3.7% over three years and support a future P/E of 34.8x.
The cautious view put fair value at US$9, based on expectations that remote work and alternative lodging would restrain revenue growth to 1.8% and leave the shares trading on a future P/E of 25.6x.
What The Results Changed For Pebblebrook Hotel Trust
Pebblebrook Hotel Trust posted Q3 2026 revenue of US$402.7 million, slightly above Q3 2025, while the reported loss widened from US$43.4 million to US$63.1 million and net margin declined from 10.9% to 15.7% in the red. That challenged the profitability timing in the optimistic case, so the period cut both ways for investors weighing the two narratives.
The episode turned on whether higher urban demand and AI efficiencies would show up in cleaner earnings. For a different REIT, you would track revenue per available room, absolute profit and net margin in each filing against the upbeat story you are being sold.
What Pebblebrook Hotel Trust’s Price Already Assumes
Today Pebblebrook Hotel Trust trades at US$22.05. The bearish analyst Narrative on Simply Wall St argues its Fair Value sits below that level, because the current quote already bakes in a strong upswing in hotel earnings, cleaner profitability, and successful execution on asset sales and redevelopment.
Anyone paying today’s price is effectively assuming resilient resort demand, better urban RevPAR, and stable margins. The key question is how that stacks up against recent RevPAR softness, lowered net income guidance, and cost pressure flagged in the Narrative.
"The numbers suggest that Pebblebrook Hotel Trust's share price already reflects expectations for a strong multiyear upcycle in urban and resort earnings, along with successful execution on redevelopment and balance sheet plans. This leaves limited room for disappointment if these outcomes do not materialise in full."
The price and this Narrative do not agree. → Uncover what this Narrative says Pebblebrook Hotel Trust is actually worth
Looking Beyond Pebblebrook’s City Focus
If Pebblebrook Hotel Trust has you thinking about lodging, take one more step out. Urban rooms are only one way to rent experience.
Another landlord concentrates on large gaming and leisure complexes. It owns the real estate under casinos, hotels and attractions that rely on steady visitor traffic.
Instead of operating resorts, it collects rent through long lease agreements. Those contracts move operating risk to tenants while tying returns to negotiated terms.
The interesting angle is how those experiential assets behave when city hotels feel choppy. A different mix of guests and leases can change how your portfolio reacts.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 68% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com