
How Investors May Respond To Jabil (JBL) AI Revenue Expansion
- Recent commentary on Jabil highlights expectations for a sharp EPS increase in the upcoming quarter, supported by its growing exposure to AI infrastructure and Intelligent Infrastructure programs.
- The focus on higher value AI related and regulated industry work suggests Jabil is leaning into complex, stickier programs that can influence margins and long term revenue visibility.
- Next, the focus will be on how Jabil's anticipated AI driven earnings expansion could reshape the existing investment narrative around the stock.
Scan how Jabil's AI driven setup compares with other potential beneficiaries of the same theme by reviewing the hand picked list in 53 AI infrastructure stocks
Jabil Investment Narrative Recap
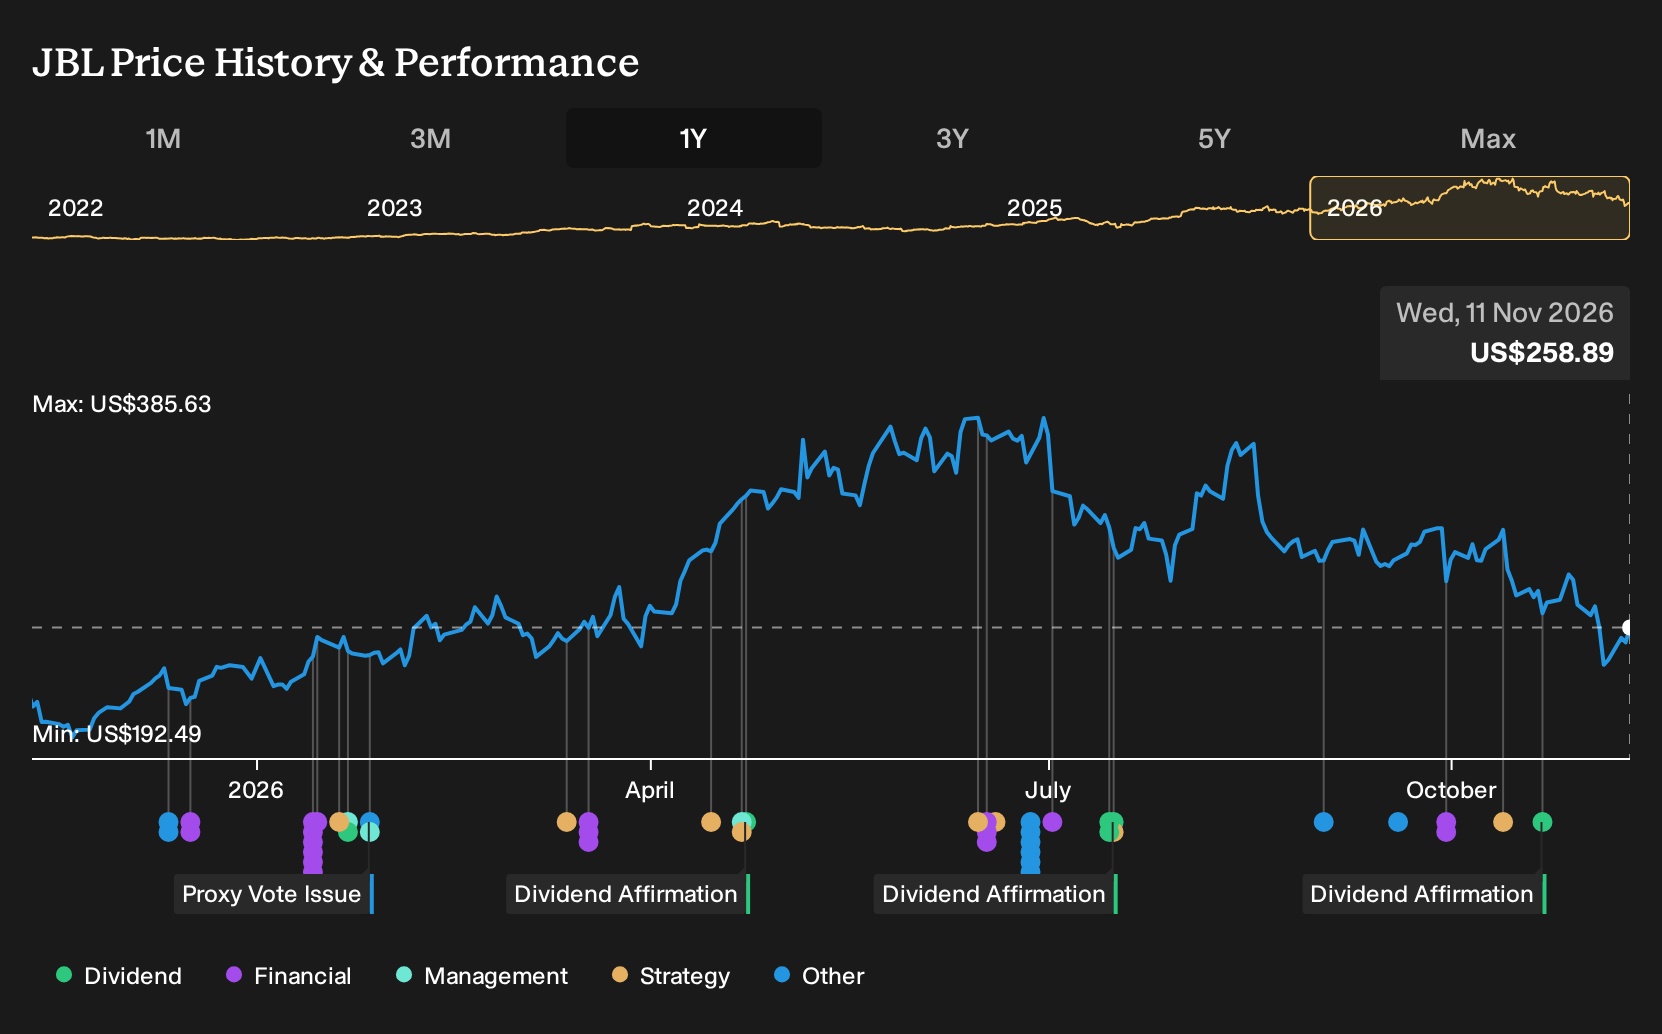
For an investor to own Jabil, the key belief is that the shift toward AI infrastructure and higher value regulated programs can remain the main earnings engine. The recent share price pullback, despite expectations for a sharp near term EPS jump, does not meaningfully change that operating story. The near term swing factor is still execution on large AI and Intelligent Infrastructure orders.
The biggest watchpoint remains supply and working capital. Tightness in components such as memory or high density PCBs could restrict what Jabil can ship, while inventory days above its 55 to 60 day target keep more cash locked on the balance sheet. If Connected Living softness persists, that could also lean against margin improvement.
The analyst consensus Narrative on Simply Wall St highlights AI related infrastructure programs as a central opportunity, with management guiding AI revenue from about US$9b in fiscal 2025 toward US$14.4b in 2026 and US$22.1b in 2027. That guided ramp, together with an expanded hyperscale customer set, is the announcement path that matters most when thinking about today’s stock move.
Those AI and Intelligent Infrastructure figures frame both the upside and the operational test. To keep that story intact, Jabil needs to translate the pipeline into shipments while handling component tightness, higher inventory and weakness in Connected Living and Robotics. If it continues to run an asset light model with net capex near 1.3% of revenue, that could support flexibility as conditions evolve.
What The Current Forecasts Assume For Jabil
Jabil's narrative projects US$57.4b revenue and US$2.3b earnings by 2029. This rests on analysts assuming 16.9% yearly revenue growth and an earnings increase of about US$1.3b from US$1.0b today.
Uncover how Jabil's fair value indicates a 64% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Jabil leans hard into AI demand risk. If cloud and data center customers trim build out plans, the more bearish analysts who were only modeling about US$53.9b of revenue and US$2.1b of earnings by 2029 already looked cautious. Those pre news estimates show how far opinions can spread. It helps to compare several narratives before deciding how this latest pullback and EPS setup might reshape your own view.
Explore 2 other Jabil fair value estimates, including one that suggests it could be worth just $425.00!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Jabil research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Jabil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jabil's overall financial health at a glance.
Looking For More Ideas Beyond Jabil?
If you want to put Jabil in context and widen your opportunity set, use the Simply Wall St Screener to compare it with other stocks that fit different risk and return profiles.
- For investors hunting for potential mispricing with quality filters in place, review a curated 32 high quality undervalued stocks that pass both cash flow and balance sheet checks.
- If dependable balance sheets matter most to you, start with a list of solid balance sheet and fundamentals (23 results) that already clears rigorous financial health criteria.
- When you want to focus on stability first and volatility second, consider a 30 resilient stocks with low risk scores that score well on resilience metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com