
Coty (COTY) Posted Stronger Profitability, Is The Recent Rally Already Priced In?
Coty earnings event and what changed for investors
Coty (COTY) just put fresh numbers on the table. First quarter sales came in at US$1,555.2 million, slightly below last year, while net income reached US$109.5 million and diluted EPS from continuing operations was US$0.12.
Against this earnings backdrop, Coty has seen a sharp swing in sentiment, with a 30 day share price return of 39.5% and a 90 day gain of 47.6%, even though the 5 year total shareholder return remains down 62.4%. This signals recent momentum building off a weak longer run.
Compare Coty’s post earnings swing with other defensives seeing renewed interest as investors rotate out of AI, using our hand picked 30 resilient stocks with low risk scores for context on lower risk opportunities.
The rally in Coty has been sharp, but the multi year record is still weak and the analyst target sits below the current price. Is most of the easy upside already realized, or does the valuation still leave room?
Most Popular Narrative: 37% Overvalued
Coty’s last close at $4.06 sits well above the analyst consensus Narrative fair value of about $2.97. This frames the recent rally as rich compared to modeled cash flows and earnings. The analyst consensus Narrative on Simply Wall St links that gap to execution risk around growth, margins, and licensing changes rather than to a missing data point in the market.
The current valuation and this narrative’s fairly valued, bullish stance together imply that the share price already reflects both the delivery of ongoing cost and deleveraging targets, and the risk that sales and margin pressure, legal actions, and the Gucci license exit could weigh on future results.
See why 9 investors see Coty as 37% overvalued.
Result: Fair Value of $2.97 (OVERVALUED)
Still, Coty’s recent like for like sales declines and the looming Gucci Beauty license exit could both challenge the bullish cost-cut and recovery story.
Find out about the key risks to this Coty narrative.
Another Angle On Coty’s Valuation
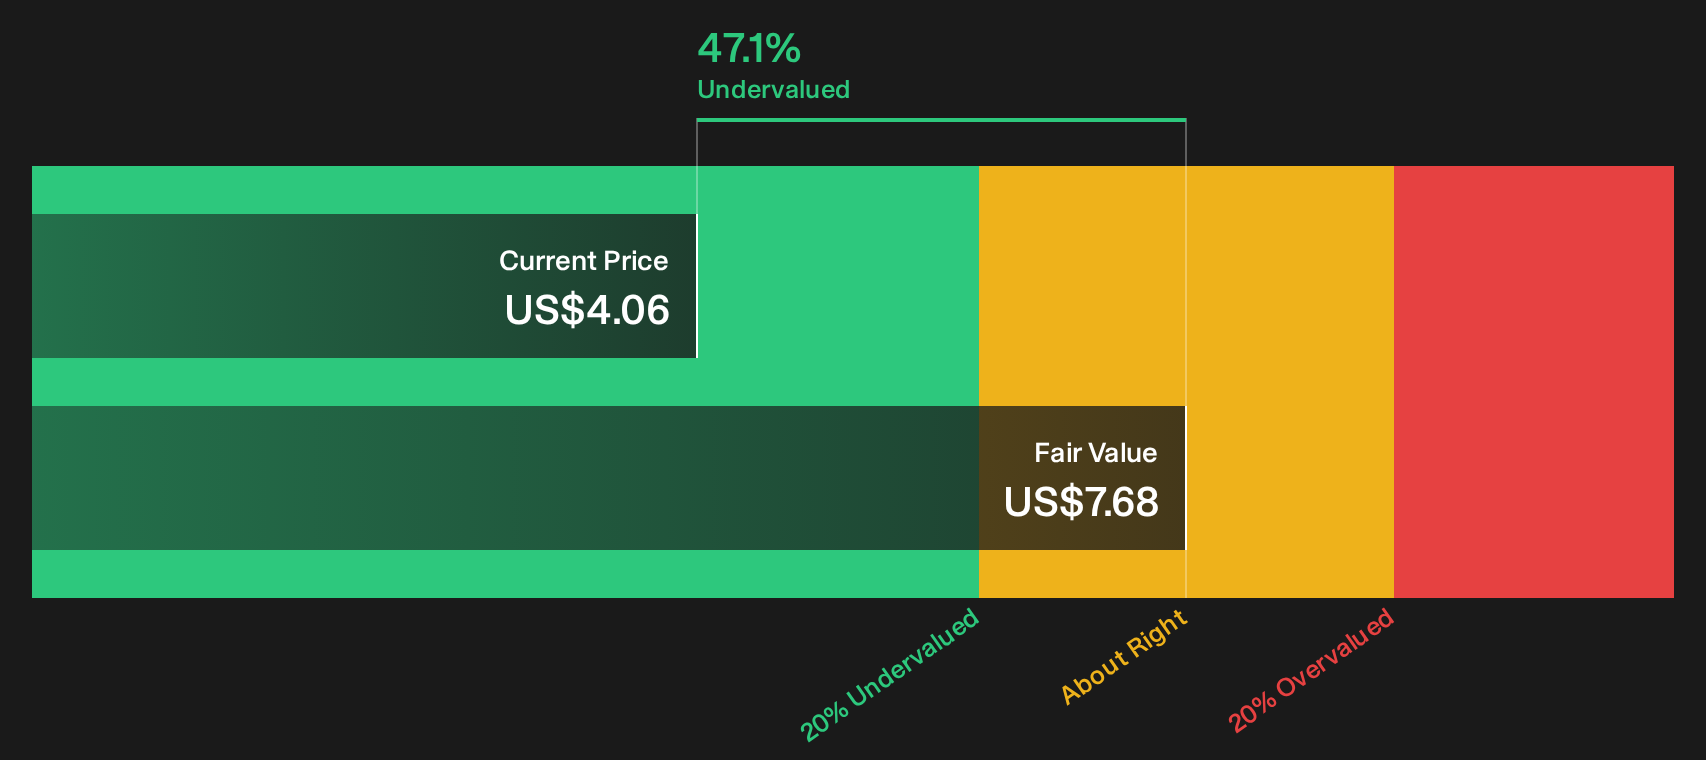
The narrative fair value pins Coty at about $2.97, well below the current $4.06 share price. Yet the SWS DCF model points to a future cash flow value around $7.68, which frames the stock as trading roughly 47% below that estimate. Which lens do you trust more?
To unpack how that gap arises and what assumptions sit behind it, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Coty is mixed, so this is the moment to look past the headlines, review the details yourself, and act before the crowd settles on a view. To see what investors are optimistic about and judge whether those positives offset the risks, check out the 3 key rewards.
Looking for more Coty-sized investment ideas?
If Coty has you rethinking your watchlist, this is the moment to broaden your radar. Fresh ideas now can shape your next few years.
- Target steady compounding by scanning companies with resilient balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispricings by reviewing a curated pool of 32 high quality undervalued stocks before the crowd takes notice.
- Stack potential income on top of capital returns by checking out a shortlist of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com