
Should Stronger Core Earnings Require Action From iA Financial (TSX:IAG) Investors?
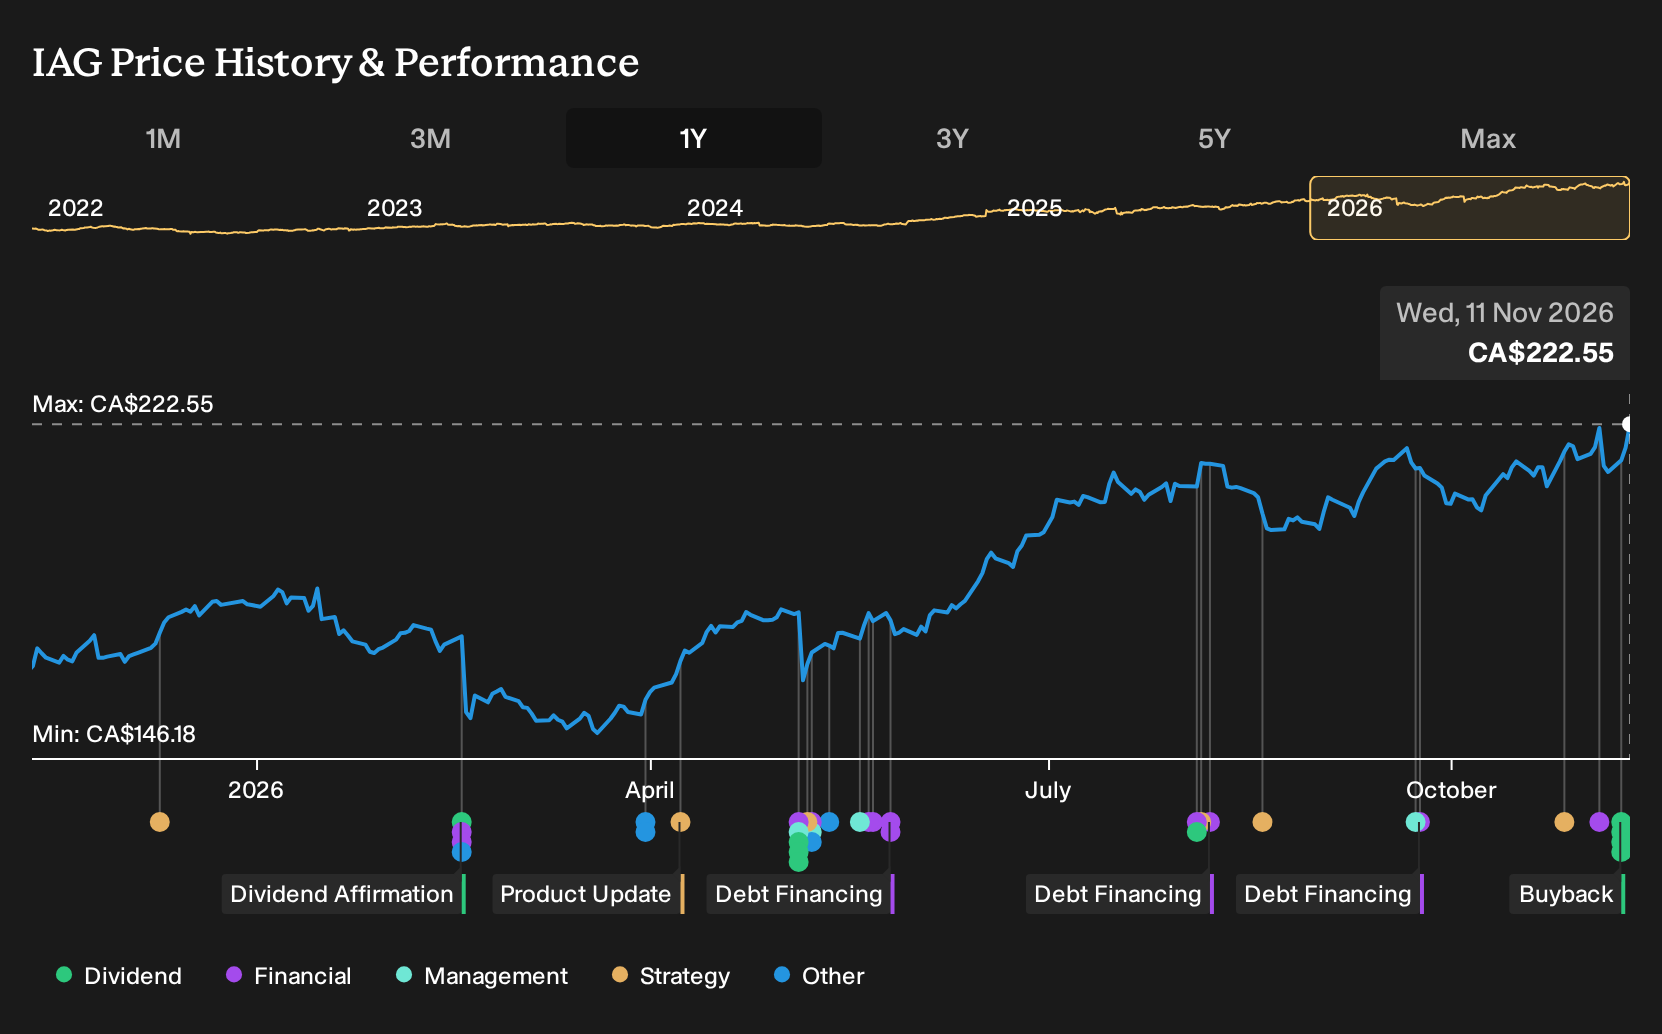
- iA Financial's board approved a higher quarterly common dividend of $1.18 per share and confirmed preferred and buyback plans, including a normal course issuer bid for up to 4,355,019 shares (5% of outstanding stock), with repurchases to be cancelled.
- The mix of stronger third quarter core earnings, a larger cash payout, and planned share cancellations highlights management's focus on wealth management scale, capital discipline, and more efficient use of excess equity.
- Next, we examine how iA Financial's investment narrative is affected by this stronger core earnings backdrop and richer dividend.
iA Financial Investment Narrative Recap
To own iA Financial, you need to be comfortable with a story built on wealth management scale, fee based revenue from segregated funds, and a diversified insurance base across Canada and the U.S. Core earnings in the quarter moved higher even as reported net income for both the third quarter and nine month periods was lower than a year ago, so execution quality matters.
The near term swing factor is whether wealth management growth and segregated fund momentum can offset softer U.S. life and dealer services trends, plus policy lapse pressure. The biggest risk remains earnings volatility in U.S. operations and exposure to market levels for assets under management, while the latest dividend and buyback moves look supportive but not transformational on their own.
The common dividend increase to CA$1.18 per share and the new normal course issuer bid for up to 4,355,019 shares tie directly into this earnings mix. Management is committing more cash to shareholders and planning to cancel repurchased stock, which can tighten the share count over time if execution stays on track.
That matters because the analyst consensus Narrative on Simply Wall St leans on ongoing earnings growth and some benefit from fewer shares outstanding. The updated capital return plan sits beside key operating catalysts such as segregated fund growth and digital investments, while the core risks in U.S. mortality, auto exposed dealer services, and regulatory changes still define the downside case that investors need to watch.
iA Financial's narrative projects CA$10.3b revenue and CA$1.6b earnings by 2029. This assumes 1.0% yearly revenue growth and an earnings increase of about CA$500m from CA$1.1b today.
Uncover why iA Financial's fair value indicates results that are roughly in line with its current price.
Exploring Other Perspectives
Simply Wall St Community users have produced 3 fair value estimates for iA Financial that span from CA$226.50 to CA$416.43, a wide gap that shows how far apart private investors can be. Set those opinions against the recent dividend hikes, buyback authorization, and softer reported earnings, then consider how each viewpoint handles both capital returns and operating risk.
Explore 2 other iA Financial fair value estimates, including one that suggests it could be worth just CA$226.50.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your iA Financial research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for iA Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate iA Financial's overall financial health at a glance.
Looking for more investment ideas beyond iA Financial?
Once you understand how iA Financial fits into your portfolio, it can help to scan a wider field of candidates with different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential upside without sacrificing balance sheet strength, consider companies filtered through our list of solid balance sheet and fundamentals (5 results) that can support disciplined capital returns over time.
- If you are focused on income, you can narrow the field to higher yielding opportunities by reviewing the 3 dividend fortresses that emphasises payouts backed by underlying fundamentals.
- Those hunting for mispriced opportunities with room for sentiment to catch up can cast a wider net using a 8 high quality undiscovered gems that highlights businesses with strong underlying metrics but less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com