
BNY (BNY) Stock Could Be Near Fair Value Following Investment Platform Expansion
Bank of New York Mellon Corporation has delivered very strong share price gains in recent years, which naturally puts the spotlight on what investors are paying for the returns it earns on its capital. With the stock now reflecting a long run of value creation, the open question is how well that current price ties back to the underlying economics of BNY's custodial and investment services franchise.
- Over the past 3 years the share price has climbed 250.7%, which makes the link between that move and the returns BNY is generating on its capital particularly important to understand.
- Recent news around plans to consolidate U.S. investment firms into BNY Investments Corporation and expand relationships such as the LiquidityDirect tie-in with trading platforms can influence expectations for how efficiently the group deploys client assets and its own balance sheet over time.
- What if you looked at Bank of New York Mellon through its earnings instead? See what Bank of New York Mellon's 16.3x P/E says about the price.
The issue now is whether the returns BNY earns on its capital are strong and durable enough to support where the stock trades today.
If you want a broader starting point for research around capital efficiency and valuation, apply the same approach to 32 high quality undervalued stocks.
Is Bank of New York Mellon Fairly Priced on Excess Returns?
The Excess Returns framework looks at what Bank of New York Mellon Corporation earns above its cost of equity on each dollar of shareholder capital. BNY is modeled with book value of $58.43 per share and a stable book value estimate of $65.45 per share, which points to a franchise that the model expects to keep compounding its equity base rather than just treading water.
Expected stable EPS of $10.72 per share, against a cost of equity of $6.10 per share and an excess return of $4.62 per share, implies that the model assumes BNY keeps generating returns above its required hurdle, with an average return on equity of 16.38%. With the Excess Returns projections putting the estimated intrinsic value broadly in line with the current share price of $152.69, the stock is priced as if those extra returns on capital continue. The planned consolidation into BNY Investments Corporation around 2027, along with moves like the LiquidityDirect link up with Tradeweb's ICD Portal, helps explain why the market is already treating BNY as a business that can keep putting its balance sheet and client assets to work efficiently. Find out what Bank of New York Mellon could be worth using our Excess Returns estimate.
The Bank of New York Mellon Narrative: What Would Justify Today's Price?
Narratives pick up where the valuation puzzle for Bank of New York Mellon Corporation leaves off, by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth far more or far less than it trades for today. Each one sets out a fair value as a thesis about how the business could develop, so you can see over time whether the story playing out still matches that original idea.
One of the top narratives on Bank of New York Mellon: 7% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Accelerated investment in digital platforms, including the AI supported platform operating model funded by roughly US$4b of annual engineering spend and hundreds of AI use cases…"
Discover why this Narrative puts Bank of New York Mellon at 7% undervalued.
One more Bank of New York Mellon Corporation signal worth putting on your checklist
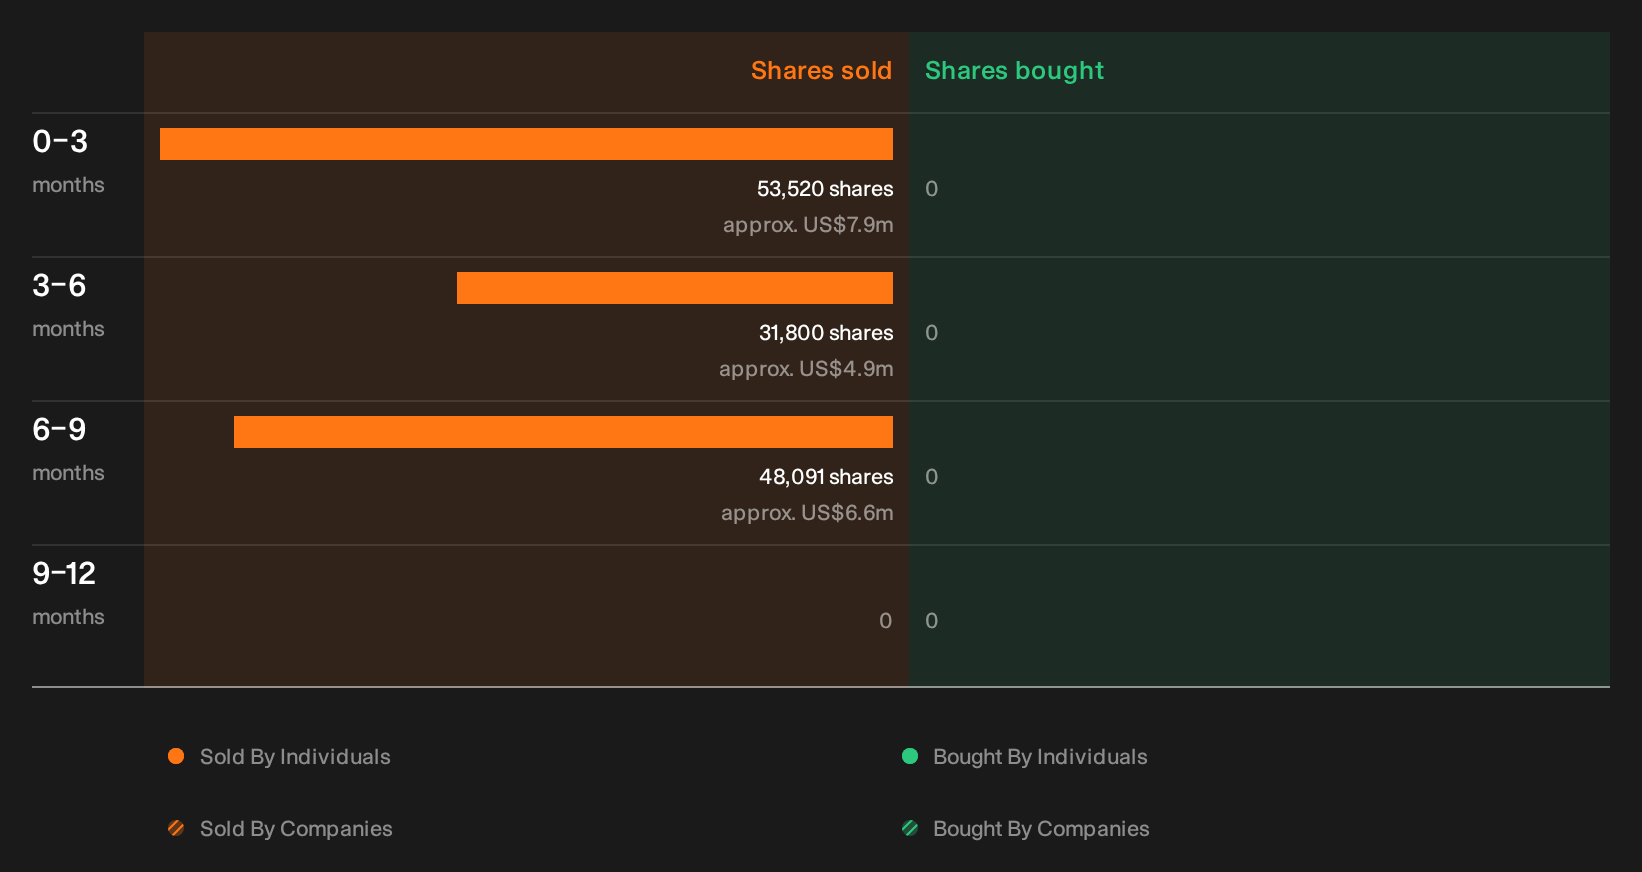
Before closing the file on Bank of New York Mellon Corporation, it is worth knowing that recent activity by company insiders has been flagged by our checks, with the who, how much and why still for you to unpack. See the recent insider selling flagged for Bank of New York Mellon.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com