
Anterix (ATEX) Narrows Its Loss, Is It Still 11% Below Fair Value?
What Anterix’s latest quarter actually showed
Anterix (ATEX) just posted fiscal second quarter results that combined a narrower than anticipated loss per share with slightly softer revenue, while progress on low band spectrum, license exchanges, and device support shaped the longer term story.
Away from the quarter’s headlines, Anterix’s share price has been volatile this year. A 7 day share price return of 11.69% sits against a 30 day decline of 9.83% and a 90 day drop of 16.39%. At the same time, a 1 year total shareholder return of 266.87% and a 3 year total shareholder return of 141.27% highlight how strongly sentiment has already shifted as investors weigh spectrum progress, regulatory momentum, and license exchange gains against the current loss making profile.
Spot similar spectrum and critical-infrastructure plays that could be setting up for the next sharp move by scanning our hand-picked list of 42 power grid technology and infrastructure stocks.Anterix now combines scarce nationwide spectrum, a growing deal pipeline and a stock that has already moved very hard. The real work starts with whether that story still adds up at today’s valuation.
Most Popular Narrative: 11% Undervalued
On the bearish analyst Narrative on Simply Wall St, Anterix screens as undervalued, with a fair value of $86 against a last close of $76.53, and that view leans heavily on how quickly 900 MHz spectrum can be turned into contracts and cash.
Although utilities are showing interest in private broadband networks as they modernize grids, Anterix still has roughly 85% of its spectrum yet to be monetized. Any delay in converting that interest into contracts could slow the realization of expected spectrum value and defer cash inflows and earnings.
See why 2 investors see Anterix as 11% undervalued.
Result: Fair Value of $86 (UNDERVALUED)
Still, the bearish Anterix story can unravel quickly if utilities slow grid modernisation spending or if spectrum clearing and FCC licensing drag and push cash proceeds further out.
Find out about the key risks to this Anterix narrative.
Another View: What Multiples Say About Anterix
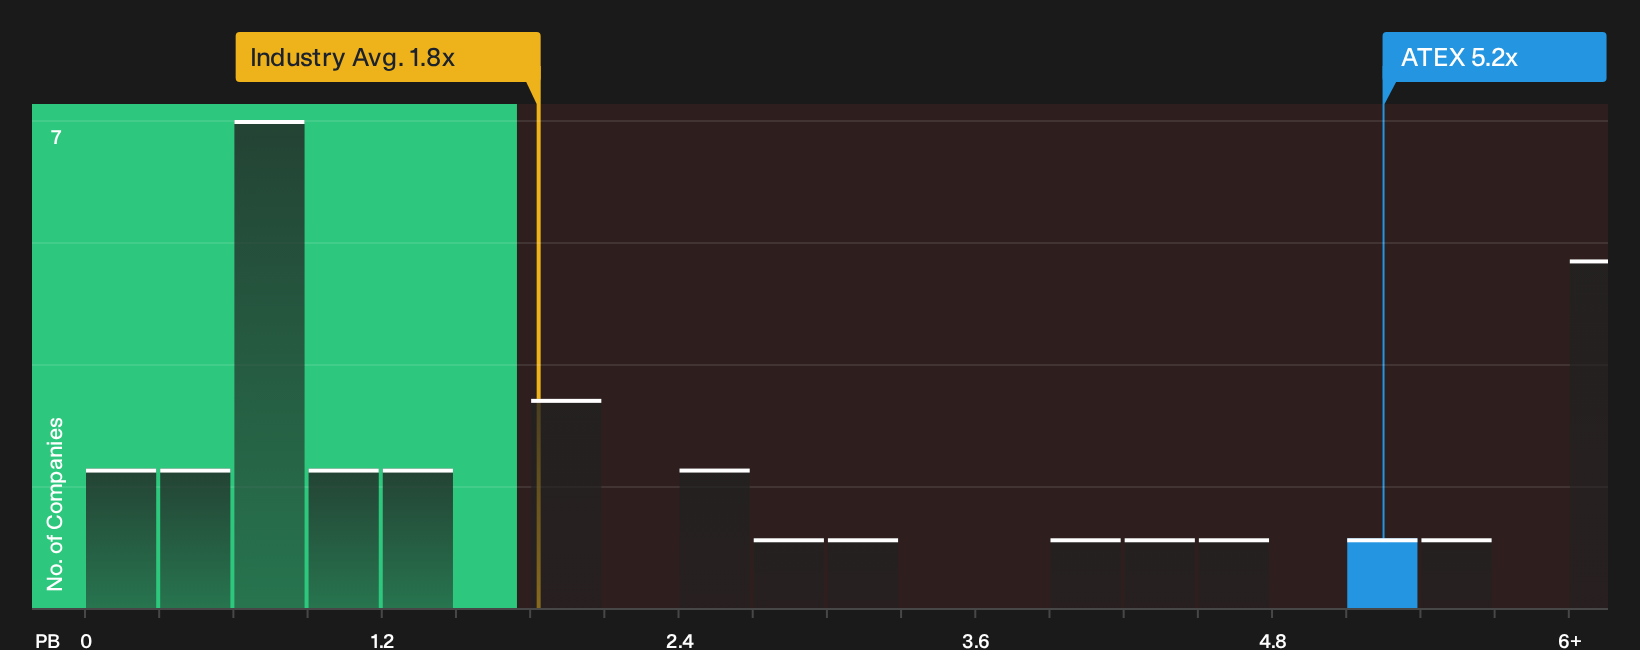
The bearish narrative frames Anterix as 11% undervalued on future spectrum monetization, yet the current P/B ratio of 5.2x tells a tougher story when set against the US Telecom average of 1.8x and a peer average of 3.4x. That premium signals higher valuation risk if the spectrum thesis takes longer to play out than supporters expect.
See what the numbers say about this price with a closer look at our valuation breakdown through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of upside and caution around Anterix leaves you unsure, move quickly from headline takes to the underlying numbers and disclosures, then test your thesis against the 4 important warning signs.
Looking for more investment ideas beyond Anterix?
If Anterix has sharpened your focus on opportunity versus risk, do not stop here. A few targeted screens can surface very different kinds of setups.
- Target potential mispricings by scanning a focused list of stocks that screen as high quality and potentially underpriced through the Simply Wall St screener 32 high quality undervalued stocks.
- Prioritize resilience over excitement by filtering for companies that combine lower risk profiles with steadier characteristics via the curated screener of 30 resilient stocks with low risk scores.
- Hunt for future leaders early by reviewing a hand picked collection of fundamentally strong opportunities in the 19 high quality undiscovered gems.
Consider lining up a few fresh watchlist candidates today so you are prepared rather than trying to react after the next move is already underway.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com