
Is Headwater Exploration (TSX:HWX) Cheap After Fresh Free Cash Flow Value Calls?
Fresh interest in Headwater Exploration (TSX:HWX) has been sparked by recent analysis pointing to sustained free cash flow and a potential gap between the share price and cash flow based intrinsic value.
That renewed interest is landing after a mixed stretch for Headwater Exploration’s share price. The CA$11.89 stock has climbed 24.63% year to date, while the 30 day share price return is down 14.83% and recent gains of 3.12% over one day suggest short term momentum may be rebuilding. Over the longer haul, the picture is stronger, with a 1 year total shareholder return of 53.60% and 5 year total shareholder return of 207.03%. This helps explain why fresh commentary on free cash flow and intrinsic value is drawing attention to whether the current price still reflects that track record.
Scan beyond Headwater Exploration and consider other cash-flow-focused energy plays with the curated 5 high quality undervalued stocks, which might be pricing in a different story relative to their intrinsic value.
Headwater Exploration has built a solid cash generating business, yet the share price just pulled back after a strong multi year run. Is this still quality at a reasonable price, or has it already been fully rewarded?
Preferred P/E of 15.2x for Headwater Exploration: Is it justified?
On a simple earnings yardstick, Headwater Exploration trades on a P/E of 15.2x, which screens as cheaper than both its Canadian oil and gas peers and the wider industry. The last close at CA$11.89 comes alongside a 37.3% discount to the SWS DCF future cash flow estimate, so the market is attaching a lower tag than either earnings or the cash flow model might suggest.
The P/E multiple captures how much investors are paying today for each dollar of Headwater Exploration's reported profit. For an exploration and production business where earnings can swing with commodity prices, that ratio becomes a quick shorthand for how optimistic or cautious the market is about the durability of current profit levels.
Headwater Exploration brings a few ingredients that often support a richer valuation. Earnings have grown by 17.9% per year over the past 5 years, returns on equity are described as high at 22.9%, and earnings quality is assessed as high. Taken together, the current P/E leaves room to ask whether the market is giving full credit to that profitability profile, especially given that the SWS DCF model places future cash flow value at CA$18.95 per share.
Set against that, the latest 0.9% earnings growth over the past year fell well short of the 32.5% figure for the Canadian oil and gas industry and also lagged Headwater Exploration's own 5 year pace. Profit margins are still healthy at 31.4%, although they are below last year's 35.1%. A P/E below both the industry average of 17.2x and the peer average of 17.5x sends a clear signal. The market is pricing Headwater Exploration at a discount to other producers despite stronger multi year earnings growth and high returns on equity.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 15.2x (UNDERVALUED)
Still, the narrative around Headwater Exploration can shift quickly if commodity prices weaken further or if future drilling results fail to support current profitability assumptions.
Find out about the key risks to this Headwater Exploration narrative.
Another view on Headwater Exploration’s value
The P/E story points to Headwater Exploration as inexpensive, but the SWS DCF model goes further. On that cash flow view, the CA$11.89 share price sits 37.3% below an intrinsic value estimate of CA$18.95 per share. This raises a sharper question: is the discount a genuine opening or compensation for risks the model cannot capture?
Look into how the SWS DCF model arrives at its fair value.
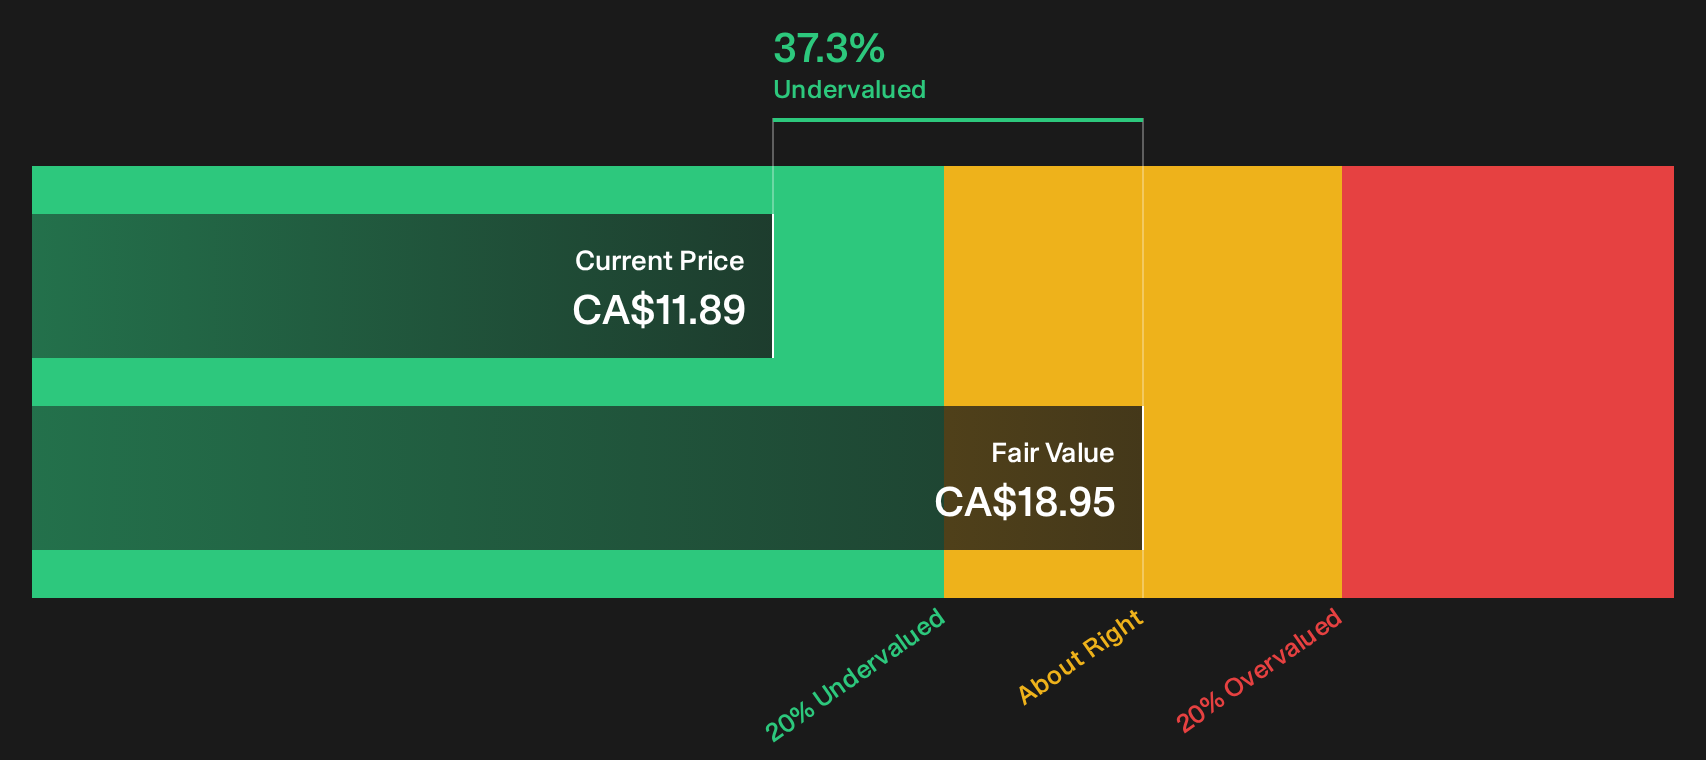
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Headwater Exploration for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Headwater Exploration can leave you torn, so take a moment to review the data yourself and decide where you stand. To balance the picture before you act, weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Headwater Exploration?
If Headwater Exploration has sharpened your focus on value and quality, do not stop here. Line up a few more candidates and compare them side by side.
- Target resilient balance sheets by scanning companies with steady fundamentals through the list of solid balance sheet and fundamentals (5 results).
- Spot potential mispricings by reviewing the 5 high quality undervalued stocks that combine strong business profiles with attractive valuations.
- Get ahead of the crowd by checking the 8 high quality undiscovered gems that pair robust financials with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com