
How Investors Are Reacting To UFP Technologies (UFPT) Strong Quarterly Earnings
- UFP Technologies reported third quarter 2026 sales of US$172.43 million and net income of US$20.62 million, with basic EPS from continuing operations at US$2.66.
- The nine month 2026 results show US$500.6 million in sales and US$58.96 million in net income, which reinforces the recent narrative around resilient margins and MedTech focused execution.
- We will now look at how UFP Technologies' stronger net income performance could influence the existing investment narrative for the business.
UFP Technologies Investment Narrative Recap
For UFP Technologies, the core belief is that a MedTech focused portfolio and a manufacturing shift to lower cost facilities can support disciplined profitability. The latest quarter fits that story. Sales of US$172.43 million and net income of US$20.62 million suggest operations are holding up while mix continues to lean toward higher margin medical programs.
The near term swing factor still sits in execution. Completing AJR transfers to the Dominican Republic and absorbing higher SG&A into current volumes looks important. The analyst consensus Narrative on Simply Wall St highlights these as key to its long term margin framework. The main risk is that cost inflation and integration work keep margins tighter for longer.
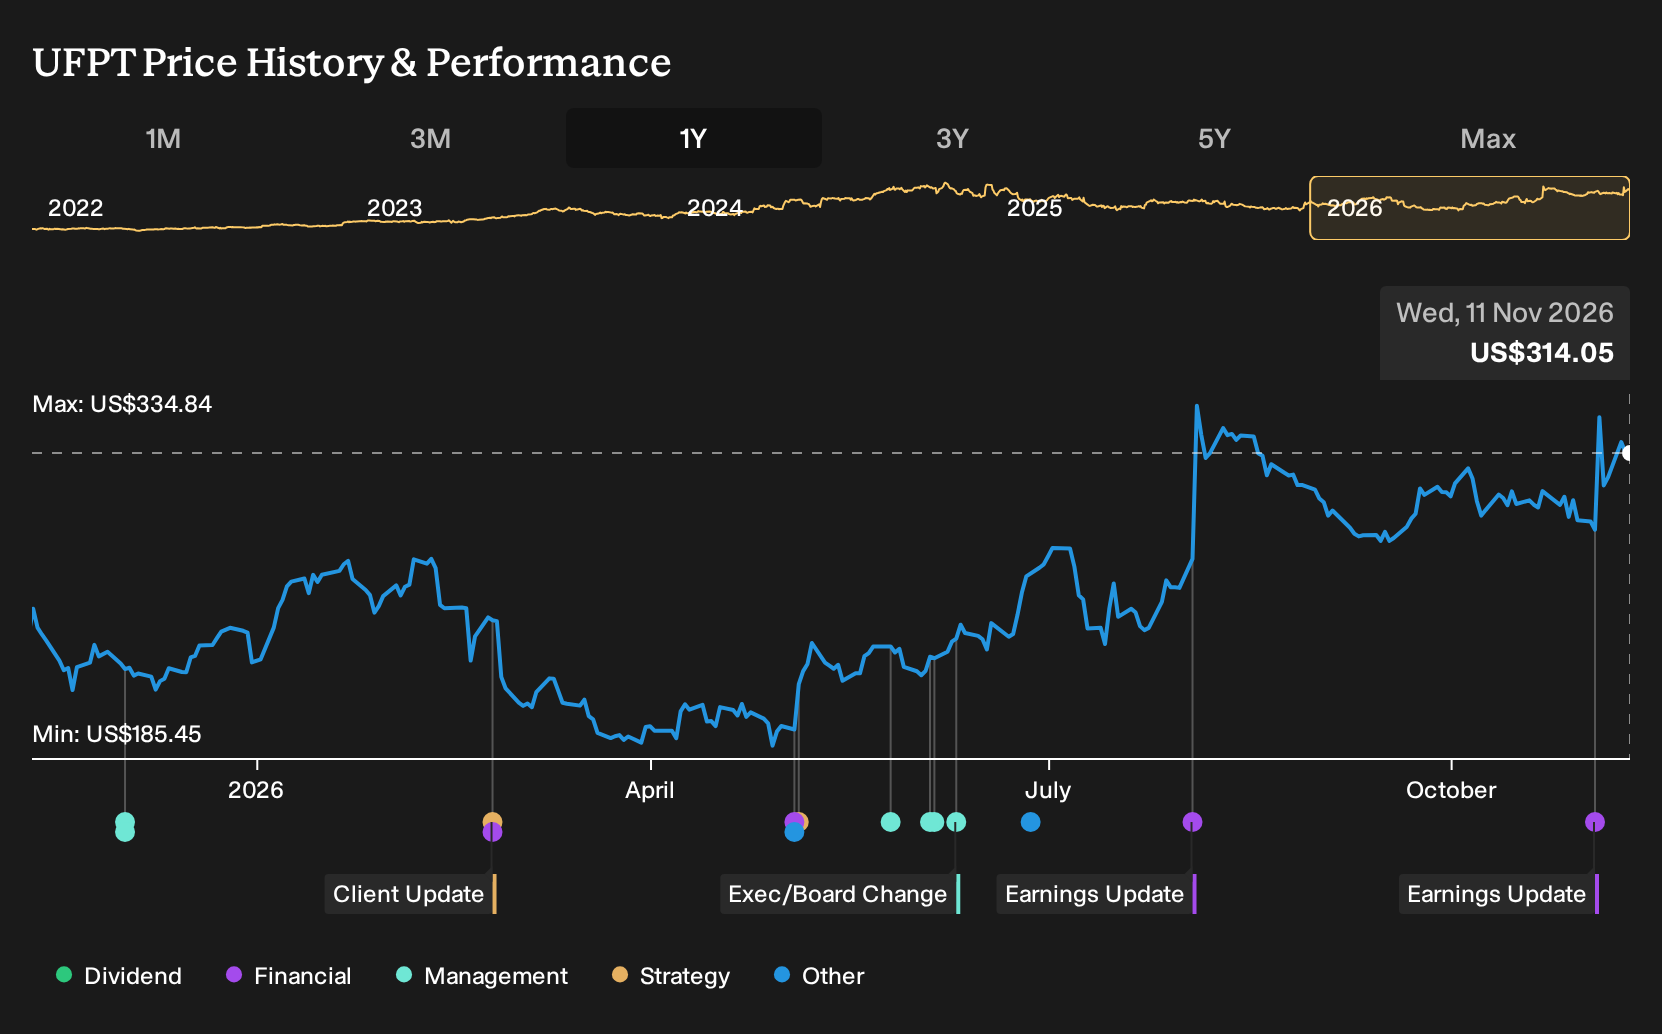
The Q3 2026 earnings release on 3 November is the key update to focus on. Nine month sales of US$500.6 million and net income of US$58.96 million give a clearer read on how the MedTech mix shift is playing out against the heavier overhead base and manufacturing realignment.
In the context of the catalysts flagged in the analyst consensus Narrative on Simply Wall St, the report matters because it shows gross profit translating into higher basic EPS from continuing operations at US$2.66 in the quarter and US$7.62 year to date. For investors tracking risks around delayed AJR transfers, higher SG&A, and future acquisitions, these figures help test whether the thesis on margins and earnings quality is still intact.
UFP Technologies' narrative projects US$782.5 million revenue and US$109.6 million earnings by 2029. This assumes 6.4% yearly revenue growth and an earnings increase of about US$33.1 million from US$76.5 million today.
Uncover why UFP Technologies' fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The most optimistic twist in the alternate UFP Technologies story comes from MedTech program wins. Bullish analysts pencilled in revenue of about US$785.0 million and earnings of roughly US$111.2 million by 2029, before this Q3 report. That is a much brighter path than consensus, and fresh results may push opinions even further apart.
Explore another UFP Technologies fair value estimate, including one that suggests as much as 13% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your UFP Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UFP Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate UFP Technologies' overall financial health at a glance.
Looking for more UFP Technologies investment ideas?
If the UFP Technologies story has sharpened your thinking, it can help to line it up against a wider watchlist built around clear criteria rather than headlines. The Simply Wall St Screener lets you filter for fundamentals first so you can test your thesis across a broader set of businesses that fit your style and risk tolerance.
- Prefer income and staying power over excitement. Screen for companies with robust payouts and balance sheets by starting with a shortlist of 6 dividend fortresses.
- Want resilience to be the anchor of your portfolio. Filter for businesses that pair strong finances with lower risk scores by running a search through 30 resilient stocks with low risk scores.
- Hunting for under followed potential. Build a watchlist of lesser known but fundamentally solid opportunities with a focused pass through 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com