
RATIONAL (XTRA:RAA) Has A Fresh Update, So What Is The Market Missing?
RATIONAL (XTRA:RAA) put fresh numbers on the table with its third quarter 2026 earnings, giving investors new data on sales growth, profitability and demand across its cooking systems portfolio.
Despite the solid third quarter release, RATIONAL’s recent price action has been mixed. The 30-day share price return is 6.14%, the year-to-date share price is down 3.96%, and the 1-year total shareholder return has declined by 1.42%.
Compare RATIONAL’s momentum and valuation reset with a curated 196 high quality undervalued stocks that share solid fundamentals and could be positioned for the next leg of institutional interest.
RATIONAL just reported higher sales and earnings, yet the share price is still lower for the year. That mix of solid operations and softer returns raises the real question: are you paying up or getting a fair deal today?
Most Popular Narrative: 20.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, RATIONAL’s fair value sits at €797.29 against a last close of €630.50. This frames the current share price as meaningfully below that central estimate while using a 6.46% discount rate for its cash flows.
Product innovation and portfolio expansion, with the iVario line growing to €79 million in H1 2026 and the newer iHexagon and iCombi One ovens gaining customer interest in less penetrated segments and markets, creates room for mix improvement towards higher growth and higher value categories. This can lift revenue and operating profit over time.
See why 5 investors see RATIONAL as 21% undervalued.
Result: Fair Value of €797.29 (UNDERVALUED)
Still, weak China demand and higher tariff costs, currently guided at €28 million to €29 million in 2026, could quickly challenge the bullish RATIONAL narrative.
Find out about the key risks to this RATIONAL narrative.
Another Lens On RATIONAL’s Valuation
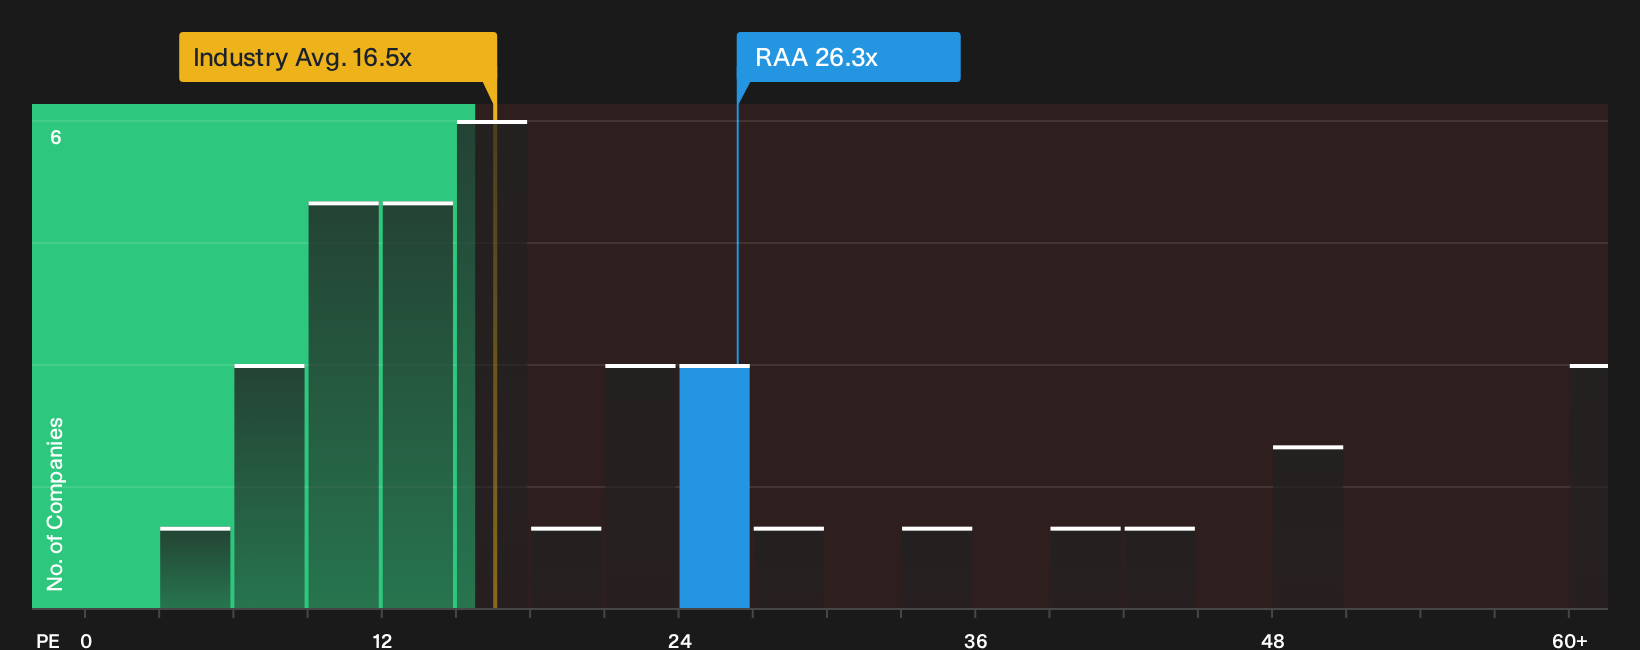
The analyst narrative relies on a cash flow view that flags RATIONAL as undervalued, and the Simply Wall St model also points to a roughly 10% discount to its own future cash flow value. The market, though, is pricing the shares at a P/E of 26.3x compared with a fair ratio of 16.7x and a German Machinery industry average of 16.7x, plus a peer average of 23.8x. That mix of discounted cash flows and rich earnings multiples leaves a simple question for you to answer: Which signal carries more weight in your framework?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on RATIONAL’s value story so far. If you want to move quickly and reach your own verdict, review the 4 key rewards and 1 important warning sign to weigh up the key factors.
Looking for more investment ideas beyond RATIONAL?
If you want a broader watchlist, use the Simply Wall St screener to uncover fresh opportunities that match your style before they move without you.
- Target potential turnaround stories with stronger balance sheets by scanning the 126 elite penny stocks with strong financials that already show improving fundamentals and market interest.
- Prioritise price discipline by reviewing the 196 high quality undervalued stocks that pair solid financial profiles with valuations that remain below their estimated worth.
- Build a steadier core to your portfolio by focusing on the 208 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com