
Did .Name Reprieve Just Shift VeriSign (VRSN) Investment Narrative?
- VeriSign reversed its earlier plan to terminate third-level .name domains and will now grandfather existing registrations, provided at least one registrar continues to support them. This eases operational disruption for long standing users.
- The policy U turn highlights how customer and stakeholder pressure can influence VeriSign's product decisions and reinforces the importance of trust in its core registry franchise.
- Now the focus shifts to how VeriSign's decision to grandfather third level .name domains might shape the broader investment narrative.
Spot how trust sensitive moves such as VeriSign's domain reversal are shaping other potential opportunities by scanning our curated list of 30 resilient stocks with low risk scores.
VeriSign Investment Narrative Recap
To own VeriSign, you need to be comfortable with a concentrated model built around .com and .net, steady registration activity, and contract stability with ICANN. The analyst consensus Narrative on Simply Wall St leans on marketing programs, price changes, and new products to keep earnings growing from a high margin, capital light base. The .name reversal mainly touches reputation and operational continuity rather than these bigger levers.
The more immediate swing factor still sits with domain demand and renewal quality around .com and .net, plus execution on upcoming wholesale price increases. The biggest operational risk is any shift in terms or timing when those registry agreements come up for renewal late next decade, along with ongoing scrutiny of debt levels and negative shareholders equity on the balance sheet.
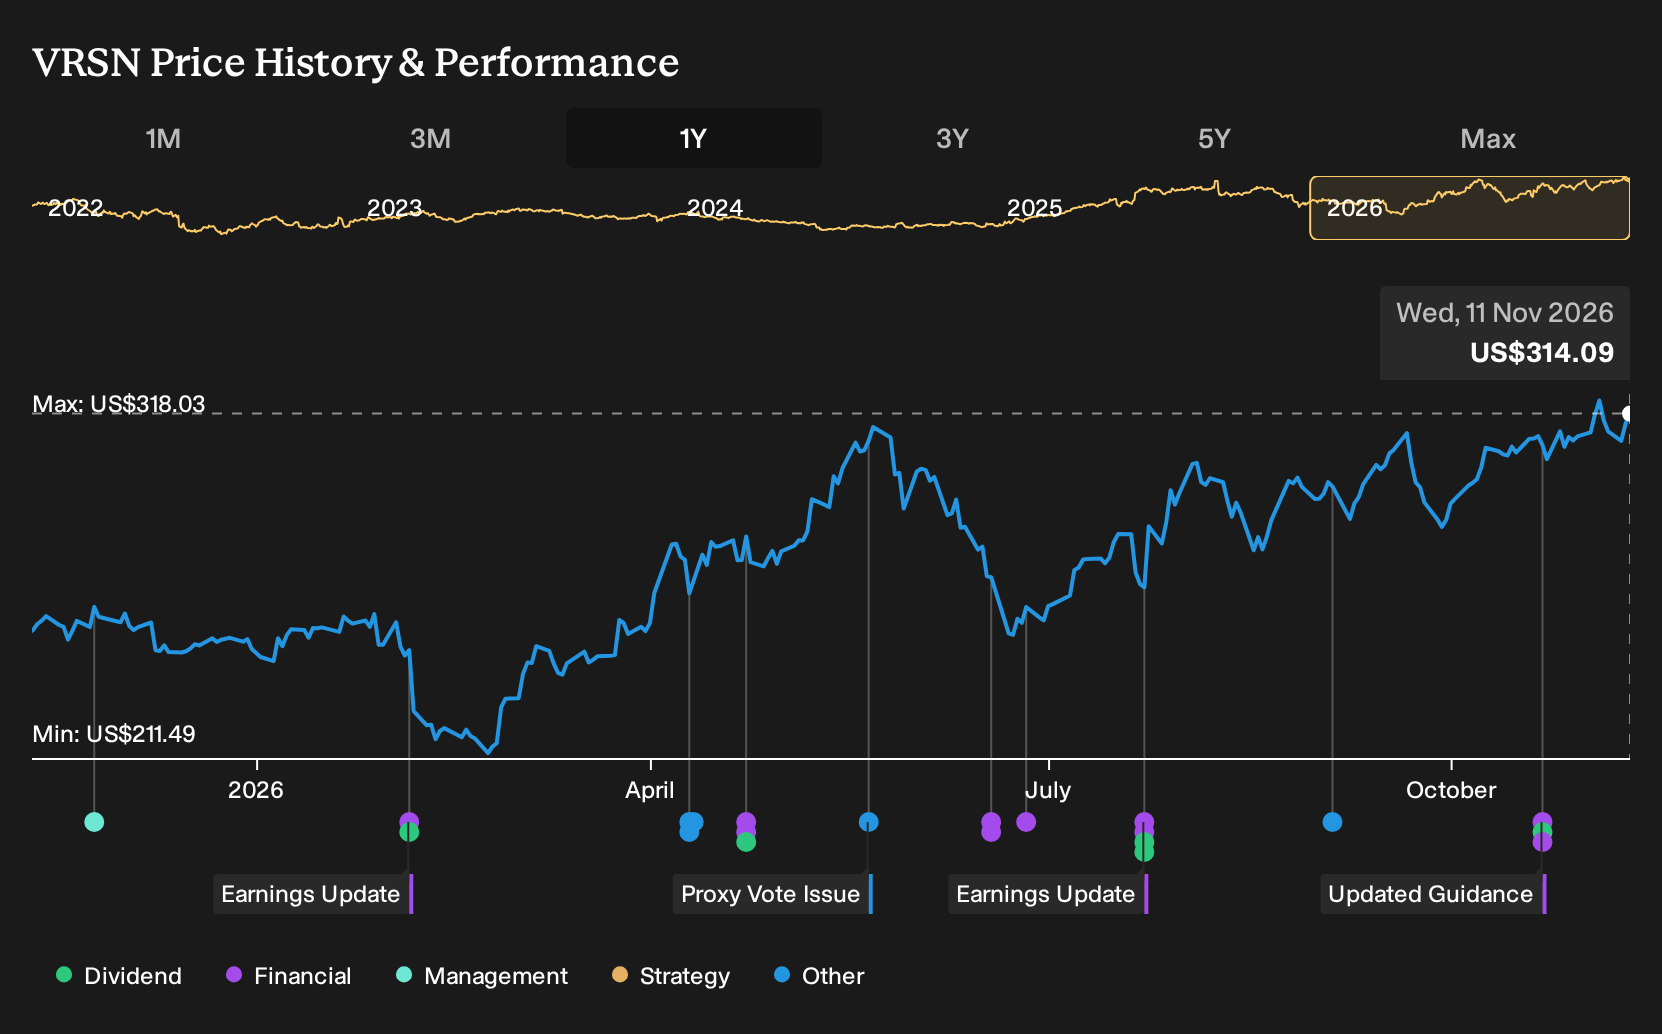
The .name decision connects most clearly to VeriSign's broader registry stewardship at a time when it is preparing wholesale price increases for .com in November 2026 and .net in March 2027. Those changes are estimated to add more than US$120m of annual revenue, and investors will likely watch how customers react to higher fees alongside expectations of reliability and fairness.
Trust sensitive moves such as grandfathering third level .name domains sit in the background of these catalysts. If registrars and end users feel the registry behaves predictably, that can support acceptance of price adjustments and interest in future offerings such as the planned .web launch and security focused products, while the business manages insider selling optics and funding structure concerns.
VeriSign's current earnings of US$849.8m are matched against analyst forecasts of US$1.2b in profit on US$2.3b of revenue by 2029. This implies 9.4% yearly top line growth and an earnings increase of about US$350m by that same year.
Uncover how VeriSign's fair value indicates a 7% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on registry contract risk and more on VeriSign’s potential from new security products and .web. Before this .name decision, the bullish camp was already pencilling in US$2.3b of revenue and US$1.2b of earnings by 2029. You can compare that view with your own interpretation of today’s trust driven news.
Explore 5 other VeriSign fair value estimates, including one that suggests there may be as much as 21% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your VeriSign research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for VeriSign. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VeriSign's overall financial health at a glance.
Looking for more VeriSign-sized investment ideas?
If this VeriSign story has sharpened your thinking about risk, return, and contract quality, you can apply the same lens across a wider watchlist using the Simply Wall St Screener.
- For investors who want potential mispricing with quality underpinning it, filter for sturdier fundamentals and valuation support with a curated set of 19 high quality undiscovered gems.
- If capital preservation ranks high on your checklist, focus on predictable balance sheets and business models by scanning a 30 resilient stocks with low risk scores.
- For those who value income alongside resilience, combine yield with staying power by reviewing a focused 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com