
Has DraftKings (DKNG) Fallen Far Enough to Look Undervalued?
DraftKings has seen a steep reset in its share price this year, and the slide puts a fresh spotlight on a simple question for investors who care about valuation. At around US$19.64 per share, is the current market value of the business still in line with what its sales can reasonably support?
- Over the past 3 years the stock has fallen about 47.4%, which places extra weight on whether the underlying revenue base can justify even the lower price investors are now paying.
- Heavy spending on the Predictions segment and related regulatory scrutiny may affect how quickly DraftKings can convert its top line into sustainable profitability, which matters for how much investors are willing to pay for each dollar of sales.
- Your read on DraftKings is one view; the desks covering it have another. See what analysts think DraftKings's shares could be worth.
The issue now is whether DraftKings' current share price is appropriately aligned with the scale and quality of its sales.
For context on how DraftKings fits into this theme of paying for sales, it can help to compare it with other companies screened for 32 high quality undervalued stocks.
Does DraftKings Look Undervalued on Sales?
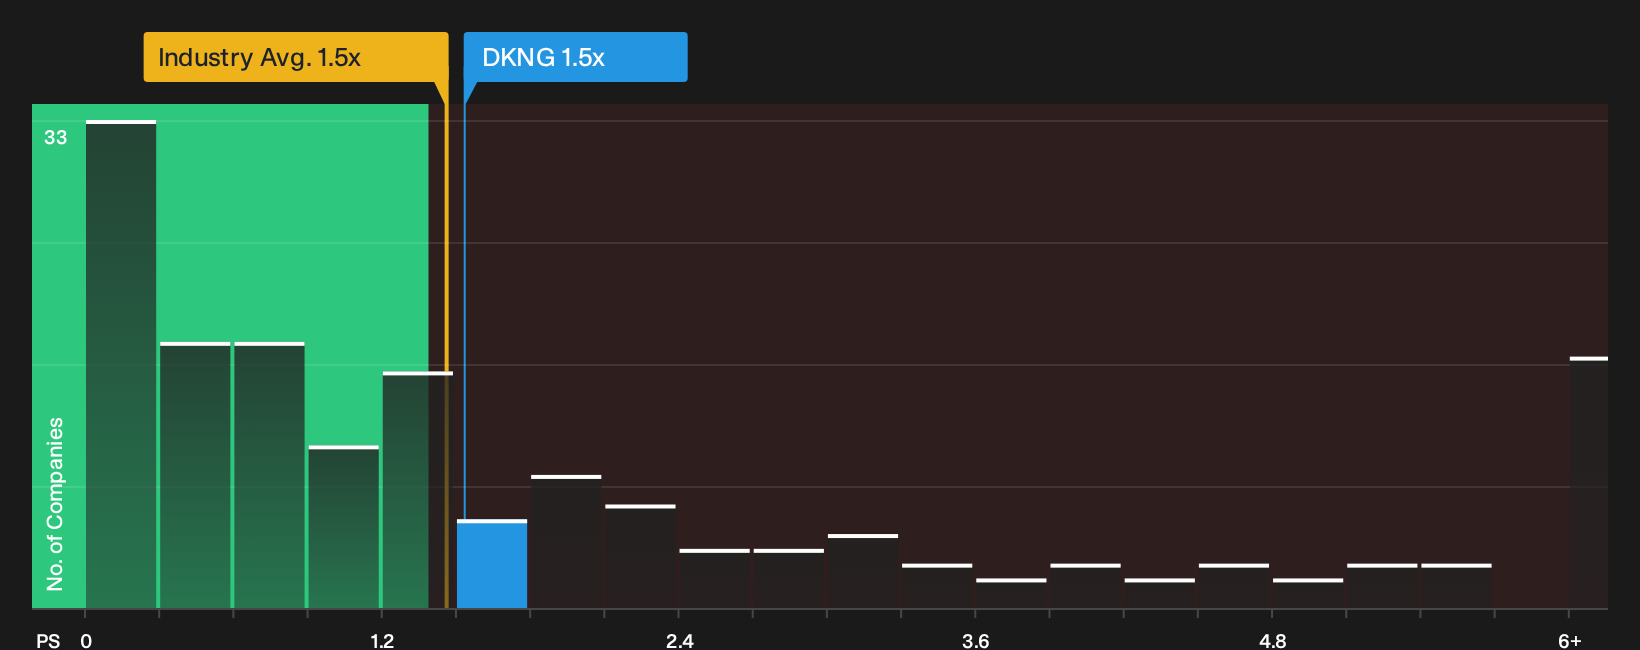
The P/S ratio works well for DraftKings because investors are still focused on how much revenue the platform can generate rather than on consistent earnings. Based on the latest figures, the stock trades at about 1.5x sales, slightly above the Hospitality industry average of roughly 1.5x and above the peer group at about 1.2x. On this simple yardstick, the market is asking you to pay a modest premium to the sector and to comparable businesses for each dollar of DraftKings revenue.
The fair-value model that blends growth expectations, margins, size and risk suggests DraftKings would usually be expected to trade on a higher P/S ratio. In that context, the current 1.5x screens as undervalued on that tailored lens. Because the recent plunge after the Q3 miss reset expectations around the Predictions segment and 2026 guidance, this lower multiple implies the setback is already reflected in the sticker price rather than being treated as a temporary bump. Explore the numbers behind DraftKings's P/S valuation.
The DraftKings Narrative: What Would Justify Today's Price?
Narratives pick up where the P/S debate leaves off for DraftKings' stock and spell out which paths for future growth, profitability and earnings would need to play out for the valuation to sit meaningfully higher or lower than today, based on scenarios shared on Simply Wall St's Community page. Rather than relying on a single ratio or headline model number, each Narrative sets out the key assumptions behind its view of fair value so you can compare them with DraftKings' reported results over time.
DraftKings now splits opinion, with one camp seeing meaningful upside in the current reset and the other arguing recent spending leaves little valuation cushion.
Bull case: 41% undervalued
The analyst consensus Narrative on Simply Wall St sees meaningful upside if DraftKings converts current investment into stickier, higher value customers.
"The main thing that has to go right is that DraftKings converts its heavy 2026 investment in predictions and higher marketing spend into durable cross-vertical customer lifetime value without eroding profitability through governance or regulatory setbacks..."
Discover why this Narrative puts DraftKings at 41% undervalued.
Bear case: 23% overvalued
The bearish analyst Narrative on Simply Wall St argues recent results and spending patterns already bake in the optimistic outcome for DraftKings.
"Although DraftKings is reporting solid adjusted EBITDA in the core business, the 4.6% year-over-year fall in Q2 2026 revenue to US$1.44b and a 4.5% revenue miss against expectations signal that weaker hold and heavier acquisition spending could be symptoms of a business that needs structurally higher marketing and promotional intensity..."
Explore why this Narrative puts DraftKings at 23% overvalued.
With DraftKings, the sticker price is only half the story
Before you decide how to treat DraftKings in your portfolio, it helps to look at who is steering the business, what they are rewarded for and how that shapes the risks you are taking. See who runs DraftKings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com