
Jazz Pharmaceuticals (JAZZ) Faces A Fresh Valuation Test Following Mixed Earnings And Buyback
Why Jazz Pharmaceuticals’ latest earnings matter now
Jazz Pharmaceuticals (NasdaqGS:JAZZ) put out a mixed update on 2 November 2026. Third quarter revenue rose year on year; however, the period swung to a sizeable net loss and arrived alongside a new US$500 million share repurchase plan.
Jazz Pharmaceuticals’ mixed quarter and higher full year revenue guidance landed as the share price has been moving sharply higher. A 17.99% 30 day share price return and a 75.17% 1 year total shareholder return suggest momentum has been building as investors reassess both growth prospects and risk around the story.
Compare Jazz Pharmaceuticals’ sharp move with a curated set of other momentum names using the 32 high quality undervalued stocks, which already pair stronger fundamentals with recent strength.
After a 75% 1 year total return and a fresh buyback announcement, the gap between Jazz Pharmaceuticals’ US$248 share price and various fair value estimates now matters. How wide is it really?
Most Popular Narrative: 16% Undervalued
On the analyst consensus Narrative on Simply Wall St, Jazz Pharmaceuticals’ fair value is estimated at $294.27 per share compared to the recent $248.24 close. This frames the fresh buyback and sharp 1 year move in a very specific way.
Expected expansion of Ziihera across additional HER2 driven tumors, including biliary tract, colorectal, lung and early or metastatic breast cancer, following the raised US$3b to US$5b peak sales outlook, could add new oncology revenue streams and support higher long term earnings power.
See why 36 investors see Jazz Pharmaceuticals as 16% undervalued.
Result: Fair Value of $294.27 (UNDERVALUED)
Still, the Jazz Pharmaceuticals story can change quickly if Ziihera underwhelms against competing cancer drugs or if generic pressure eats into the sleep franchise faster than expected.
Find out about the key risks to this Jazz Pharmaceuticals narrative.
Another View: what Jazz Pharmaceuticals’ multiples are saying
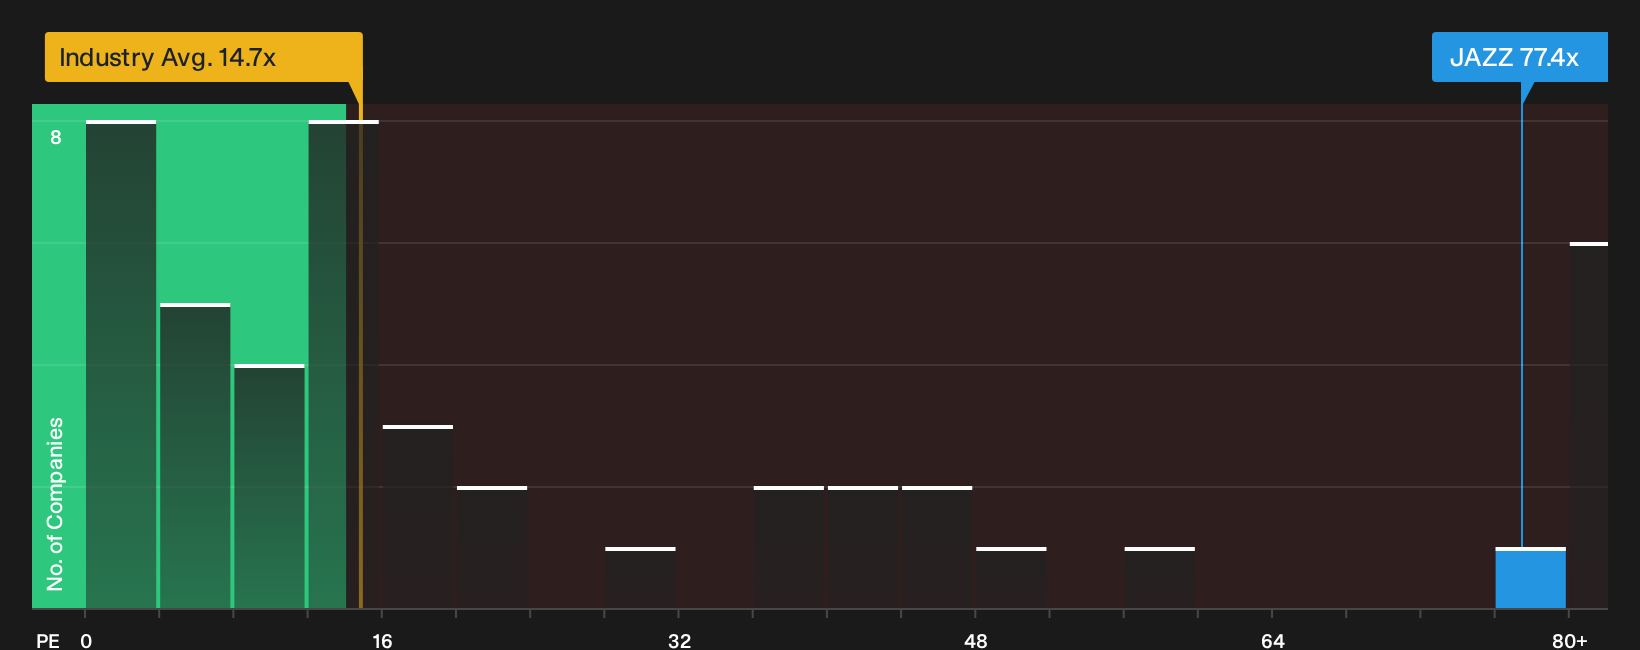
Look past the fair value estimates tied to analyst forecasts and the picture shifts. Jazz Pharmaceuticals trades on a P/E of 77.4x compared with 14.6x for the US Pharmaceuticals group and a peer average of 33.7x. The fair ratio of 36.2x points to a wide gap that could mean valuation risk if sentiment cools or earnings do not build as expected.
If you prefer to anchor on earnings based markers rather than cash flow models, this is a very different signal. Which lens do you trust more when the next data point lands: the bullish fair value, or the rich P/E multiples relative to industry and peers? What would make you change your mind about it, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Jazz Pharmaceuticals is clearly split, with sharp optimism on upside and clear concern on emerging risks. Move quickly and test the numbers yourself before views harden further. For a balanced snapshot that flags both the positives and the pressures around the business, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Jazz Pharmaceuticals?
If Jazz Pharmaceuticals has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist now before other investors crowd into the same opportunities.
- Target resilient balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (23 results).
- Hunt for strong businesses that the market may be overlooking by reviewing the 19 high quality undiscovered gems.
- Zero in on potential cash generators that also pay out today by checking the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com