
Amprius Technologies (AMPX) Raised Guidance And Won A $75 Million Contract, Is It Still Cheap?
Amprius Technologies (AMPX) just posted record third quarter revenue along with a narrower loss, raised its full year 2026 outlook, and secured a US$75 million U.S. Department of War battery contract.
Amprius Technologies’ share price has been volatile around these headlines, with the stock down 6.76% on the day to US$8.55 and showing a 90 day share price decline of 28.39%, even as the 3 year total shareholder return of 137.50% points to a much stronger long term journey.
Scan beyond Amprius Technologies and compare it with 53 AI infrastructure stocks, which is benefiting from rising demand for high performance power and computing support behind drones, aviation, defense, and advanced mobility platforms.
Bulls point to Amprius Technologies’ record sales, upgraded 2026 guidance, and the US$75 million contract. Bears focus on ongoing losses and recent share price weakness. Which story does the current valuation lean toward?
Most Popular Narrative: 61% Undervalued
On the analyst consensus Narrative on Simply Wall St, Amprius Technologies screens as undervalued, with a fair value of $22.10 against the last close of $8.55. That gap sits on top of bullish revenue and earnings forecasts that already bake in heavy execution work.
The main thing that has to go right is that Amprius Technologies delivers NDAA-compliant capacity and contract manufacturing scale on the timelines implied by its IBAS-funded U.S. buildout and multi-year orders from drone and electric motorcycle customers.
The current valuation, including a P/S of about 15.1x alongside short-seller scrutiny and a Strong Sell rating from one service, implies the share price already reflects strong execution on growth, margins, and capital-light scaling. This narrative views that as leaving room for upside if that execution continues.
What is behind 113 investors see Amprius Technologies as 61% undervalued.
Result: Fair Value of $22.10 (UNDERVALUED)
Still, this narrative leans on contested ground, with short seller allegations and a P/S near 15x that could both trigger a sharp reset in sentiment.
Find out about the key risks to this Amprius Technologies narrative.
Another View on Amprius Technologies’ Valuation
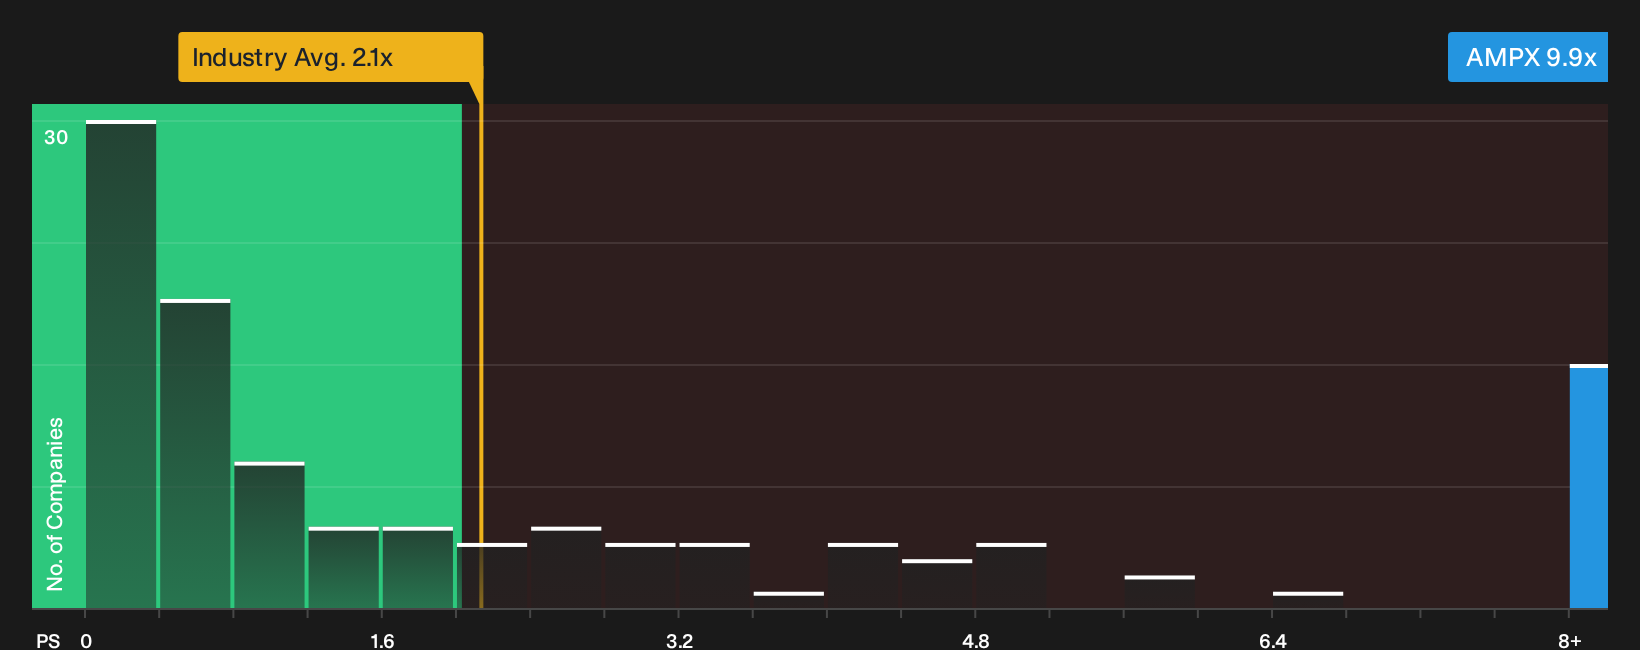
The analyst narrative leans on future earnings power. A simpler cross check uses today’s P/S of 9.9x against a fair ratio of 4.1x and a US Electrical industry average of 2.1x. That gap suggests meaningful valuation risk if expectations cool. Which signal do you trust more?
For a closer look at what the current ratio implies in practice, including how it stacks up against peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of excitement and concern around Amprius Technologies feels familiar, that is the point. You are looking at a real debate playing out in the numbers. Act while sentiment is divided and build your own view using the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Amprius Technologies?
Do not stop your research with Amprius Technologies. Broaden your watchlist with other opportunities so you are not relying on a single high conviction story.
Use the Simply Wall St Screener to quickly surface focused sets of ideas that match the type of opportunity you want to investigate next.
- Target potential mispricings by reviewing the 32 high quality undervalued stocks that combine quality fundamentals with compressed expectations in one place.
- Prioritise resilience first and dig into the 30 resilient stocks with low risk scores that flag businesses with more stable profiles and lower overall risk scores.
- Unearth underfollowed opportunities and scan the 19 high quality undiscovered gems that pair strong financials with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com