
Hasbro (HAS) Lifts 2026 Guidance, Is The Stock Getting Pricey?
Hasbro (HAS) raised its 2026 revenue and margin guidance after reporting strong MAGIC: The Gathering demand, solid licensing activity, and operational gains in cost savings, supply-chain efficiency, and inventory management.
The Hasbro share price has gained 30.9% over the past month and 49.5% year to date, with the latest guidance upgrade adding to that momentum. The 1 year total shareholder return of 61.8% and 3 year total shareholder return of about 3x highlight how sentiment has shifted around the story.
Spot similar surges by scanning hand-picked consumer-focused stocks with strong recent momentum using the 32 high quality undervalued stocks.
After a 3x three year run and a sharp rally into Hasbro’s upgraded 2026 targets, the real question now is whether the current tag still compensates you for the risks that come with it.
Most Popular Narrative: 4% Overvalued
Hasbro last closed at $124.02 compared with an analyst consensus fair value of about $119.08, so the analyst consensus Narrative on Simply Wall St currently views the stock as modestly ahead of its calculated worth based on projected cash flows and earnings.
Long-term industry consolidation and Hasbro's strengthened position as an IP-driven, multi-channel entertainment company increases pricing power and cross-licensing leverage, which should sustain higher gross margins and reduce volatility in earnings.
Cost rationalization, supply chain diversification, and SKU optimization (cutting low-margin or tariff-hit products) post-Entertainment One divestiture are enhancing operational efficiency and offsetting input cost headwinds and are expected to structurally improve net margins and EBITDA over the next several years.
See why 31 investors see Hasbro as 4% overvalued.
Result: Fair Value of $119.08 (OVERVALUED)
Still, Hasbro’s heavy dependence on Magic: The Gathering, along with its exposure to tariff and supply chain costs, could quickly challenge the current optimism if those supports weaken.
Find out about the key risks to this Hasbro narrative.
Another View: Hasbro Through The Cash Flow Lens
Analysts on Simply Wall St see Hasbro as about 4% above their $119.08 fair value, yet the SWS DCF model presents a different picture. On that framework, Hasbro at $124.02 sits roughly 13.7% below an estimated future cash flow value of $143.76, which may indicate that the stock is priced more cautiously than it appears. Which perspective do you think better reflects the risks around Magic: The Gathering and the balance sheet?
For a closer look at the assumptions behind that cash flow view, including discount rates and terminal values, Look into how the SWS DCF model arrives at its fair value.
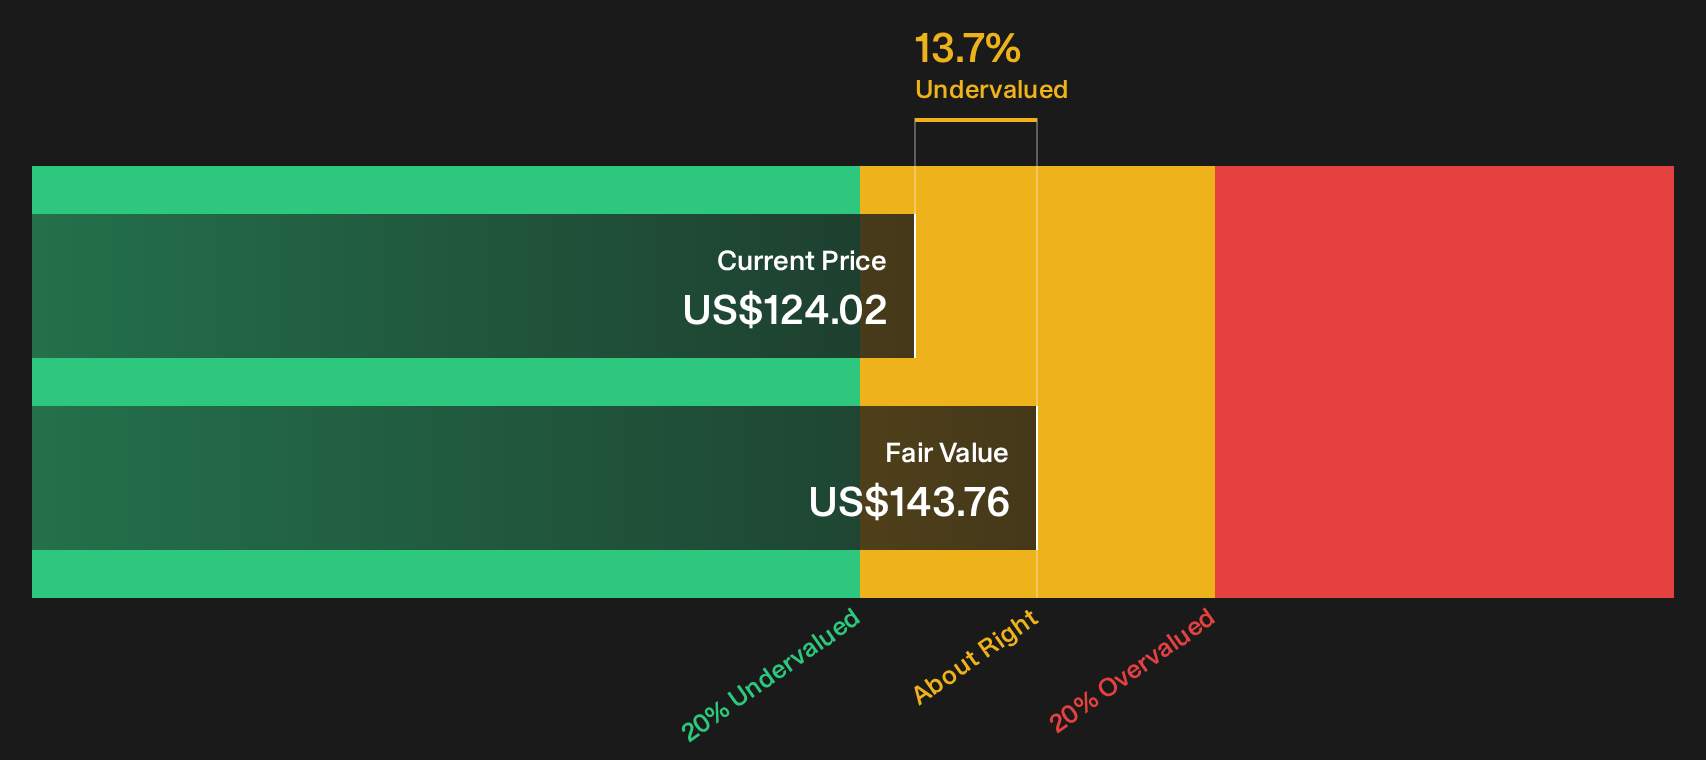
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hasbro for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed on Hasbro after all that. If you want to move quickly from story to evidence and weigh both the upside and the downside yourself, start with the 4 key rewards and 2 important warning signs.
Looking for more Hasbro-sized opportunities?
If Hasbro has sharpened your appetite for quality ideas, do not stop here. Your next strong candidate could already be sitting in the screener waiting for you.
- Target resilient balance sheets and cleaner fundamentals by running companies through the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality businesses that screens suggest may trade below their estimated worth using the 32 high quality undervalued stocks.
- Zero in on lesser-known prospects with stronger underlying metrics before the crowd spots them via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com