
Tasmea (ASX:TEA) Draws Fresh Attention As Cash Flow Narrative Points To Value
Tasmea (ASX:TEA) is back in focus after fresh analysis suggested a gap between its current share price and the cash the business is expected to produce over time.
Recent moves show momentum has cooled slightly after a strong run, with a 7.05% 7 day share price return and a 1 month share price decline of 9.95%. Yet Tasmea still carries a year to date share price gain of 135.56% and a 1 year total shareholder return of 92.82%, keeping attention fixed on whether the A$9.87 level lines up with the cash flow story.
Compare Tasmea's cash flow story with other potential value opportunities by scanning the hand picked 3 high quality undervalued stocks that share strong fundamentals and attractive pricing gaps.
Bulls point to Tasmea's cash flow estimates and acquisition track record, while bears question how much of that is already priced in after the surge. The valuation work shows which side the numbers currently back.
Most Popular Narrative: 8.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, Tasmea's fair value sits at A$10.83 compared with the latest A$9.87 close, which points to a modest discount while hinging heavily on how recurring work and acquisitions translate into future cash flows.
The build out of data centers in Australia is creating a growing pool of work in transmission, substations and connections. Tasmea already has one of the largest remote specialist electrical workforces, which can support revenue and EBITA if contract wins continue.
See why 11 investors see Tasmea as 9% undervalued.
At the core of that valuation is a discount rate of 8.77% applied to analyst forecasts for Tasmea's earnings and margins, which pulls those future cash streams back into today's dollars. That approach ties the A$10.83 figure to assumptions about sizeable revenue expansion, slightly higher profit margins and a future P/E of 23.4x, all of which investors can compare with their own expectations and risk tolerance.
Result: Fair Value of A$10.83 (UNDERVALUED)
Still, the Tasmea narrative could be challenged if data center power projects or mining maintenance workloads fall short of expectations, or if acquisitions deliver weaker earnings than analysts model.
Find out about the key risks to this Tasmea narrative.
Another View: Tasmea Looks Expensive On Earnings
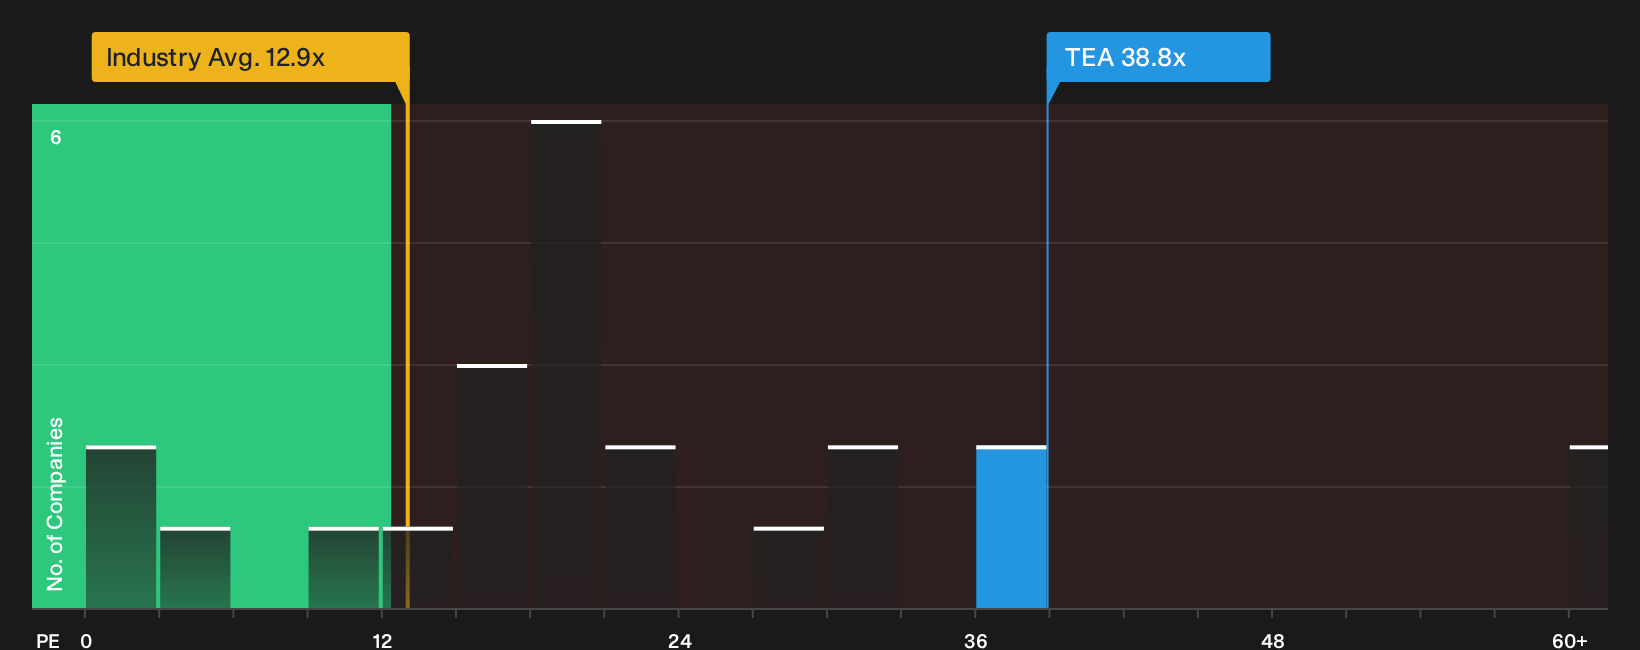
The DCF work suggests upside for Tasmea, yet the earnings multiple sends a much tougher message. At a P/E of 38.8x versus 29.1x for peers and 12.9x for the global Construction group, and above a fair ratio of 30.1x, the stock carries clear valuation risk. Which signal do you back?
Our earnings multiple view points to a rich entry price, so it helps to see how that stacks up in a structured comparison before making any move. See what the numbers say about this price — find out in our valuation breakdown.
Here is how Tasmea's P/E ratio compares with the broader sector over time.
Next Steps
Mixed signals on Tasmea's value case make this a good time to look through the numbers yourself and decide where you stand. To quickly weigh the upside against the threats, review the 3 key rewards and 1 important warning sign.
Looking for more Tasmea-sized ideas?
If Tasmea has your attention, do not stop at a single opportunity. Use focused screeners to surface other stocks that match your risk, income, and quality goals before the market gets there first.
- Target income first by scanning a curated pool of companies offering resilient cash returns through the 4 dividend fortresses.
- Hunt for quality at a discount by tracking companies with strong fundamentals that still trade below implied worth using the 3 high quality undervalued stocks.
- Protect your downside by filtering for sturdier businesses and steadier balance sheets with the 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com