
How Dividend Backed Growth Projects Will Impact BHP Stock Investors
- BHP Group has recently been highlighted for its diversified operations, where iron ore and metallurgical coal supply strong cash flow, while copper and potash projects contribute to its position in decarbonization and electrification supply chains.
- The focus on dividend strength backed by established assets, along with capital intensive copper and potash growth projects that carry execution risk, has sharpened attention on how BHP balances income today with funding future production.
- Attention now turns to how BHP Group’s dividend backed growth projects may reshape the investment narrative, given rising interest in its copper exposure.
Scan income-heavy resource stocks positioned for electrification themes alongside BHP Group by zeroing in on our curated list of 4 dividend fortresses.
BHP Group Investment Narrative Recap
BHP Group appeals to shareholders who want a diversified miner where iron ore and steelmaking coal fund a sizeable dividend while copper and potash projects tie into decarbonization and electrification trends. According to Jamesiskindacool, an investor in the Simply Wall St Community who wrote the Narrative, the current share price already leans on established operations more than on blue sky expansion.
The key short term swing factor is how reliably existing assets convert production guidance into cash flow, especially with recent copper output softness at Escondida. That same weakness also highlights the main risk right now. Project heavy copper and potash growth needs disciplined execution so dividends remain supported despite operational bumps.
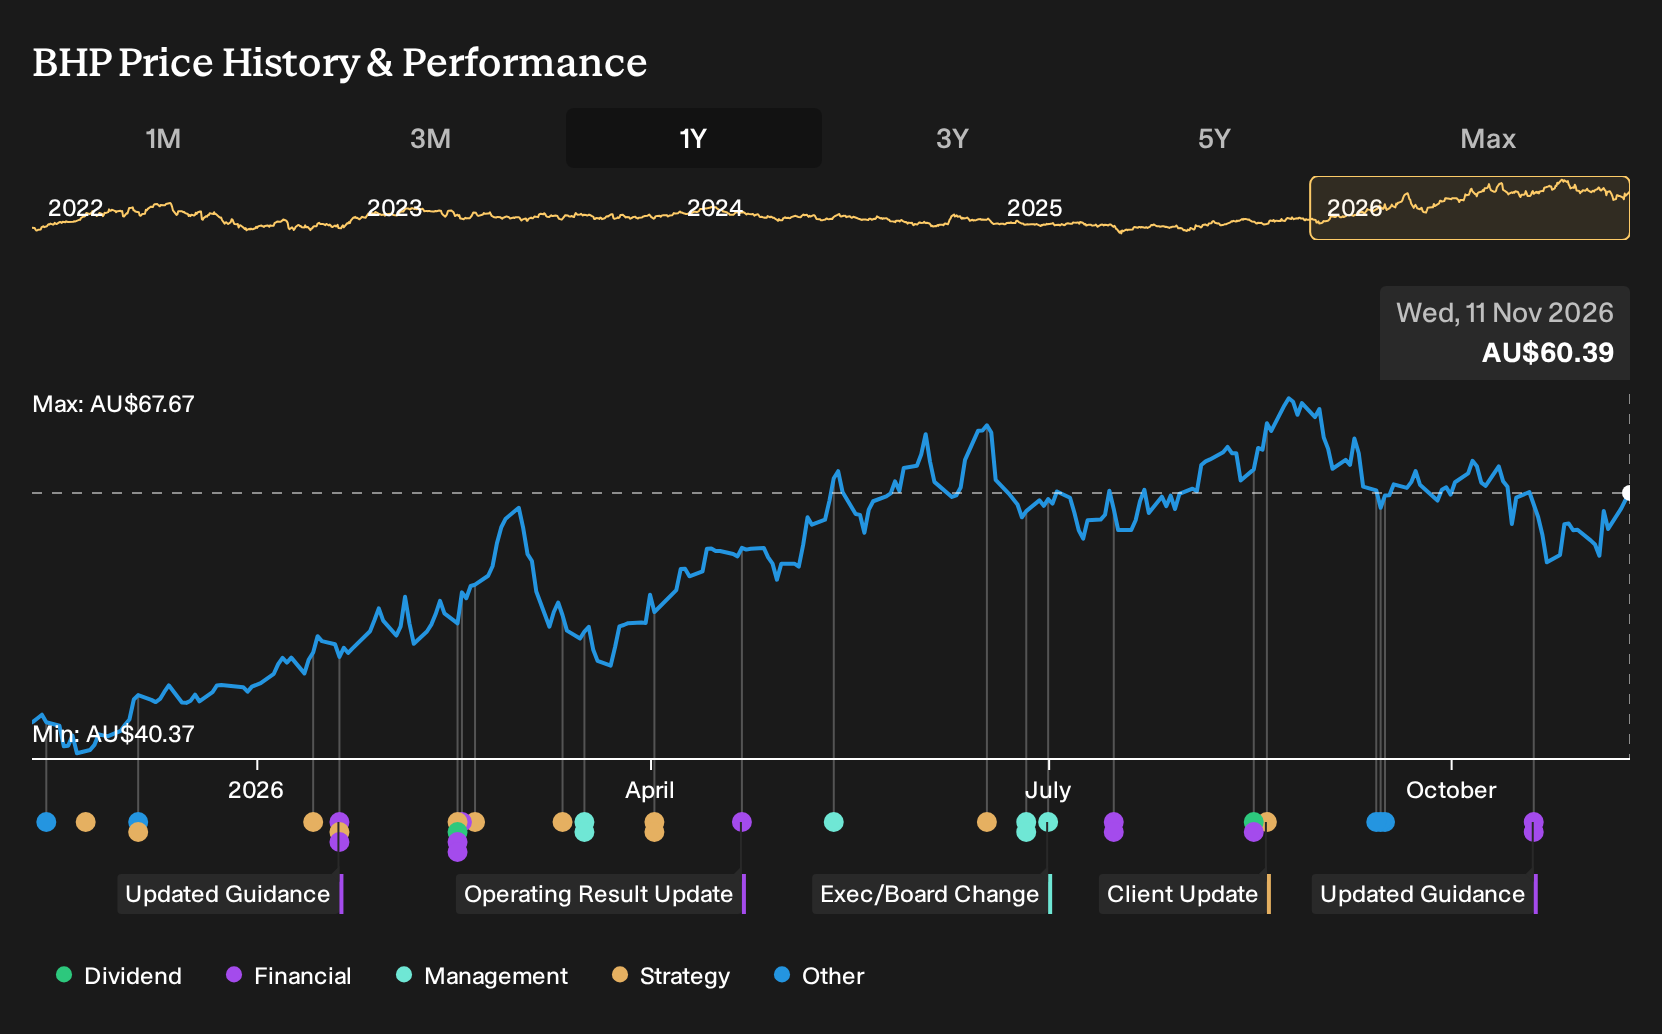
The recent disclosure that Escondida copper production fell 21% year on year in September puts a spotlight on BHP Group’s copper guidance, which previously pointed to output in the upper half of the 1.9 to 2.0 million tonne FY26 range. Investors are effectively watching whether temporary supply issues stay contained or begin to challenge that range.
Jamesiskindacool argues that little value is being ascribed to future copper expansions and Jansen potash in current assessments. Escondida’s weaker volumes make those longer dated projects feel more important as eventual offsets, yet they also bring capital and execution risk. The near term test is whether established iron ore and coal cash flow still comfortably covers dividends while copper and potash delivery plays out over time.
Using a revenue growth assumption of 4.6% a year and a future profit margin of 19.0%, the Narrative from Jamesiskindacool points to a fair value of A$47.93 per BHP Group share. This aligns with recent earnings, dividend cash flows and a P/E of around 13.6 times on annualised underlying earnings.
Uncover why BHP Group's fair value indicates a 21% potential downside to its current price, a premium that may not be sustainable.
Exploring Other Perspectives
Some readers will see the Escondida production drop and worry most about capital stretch at BHP Group. The lowest analysts were already assuming revenue would fall about 4% a year and only reach around $52.1b by 2029, with earnings near $11.8b. That is a far more cautious script. Use this news as a cue to compare those expectations with your own and explore how both narratives might evolve.
Explore 16 other BHP Group fair value estimates, including one that suggests as much as 47% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your BHP Group research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BHP Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BHP Group's overall financial health at a glance.
Looking for more investment ideas beyond BHP Group?
If you want to put BHP Group in context and round out your watchlist, it can help to scan other stocks with different income, quality, and risk profiles using the Simply Wall St Screener.
- For investors who want a cash flow focus with income resilience, start by reviewing companies in our 4 dividend fortresses.
- If you are hunting for quality at a reasonable price, check out the 3 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- When capital preservation sits high on your priority list, narrow your research to the 6 resilient stocks with low risk scores that may help smooth out portfolio volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com