
NEXON (TSE:3659) Shares Climbed, What Is Driving Attention Today?
NEXON (TSE:3659) has put fresh 2026 guidance on the table, flagging record full year revenue and operating income targets, while fourth quarter expectations show mixed trends across revenue, profit and net income ranges.
Recent trading suggests sentiment around NEXON is improving. The share price has climbed 20.48% over the past 90 days and delivered a 15.12% 1 month share price return, even though the year to date share price performance is still down 23.99% and the 1 year total shareholder return is slightly negative at 3.12%. This compares with a much stronger 47.18% total shareholder return over five years, which indicates that long term holders remain ahead while shorter term investors are reassessing risk and growth potential following the 2026 guidance and special dividend announcement.
Spot emerging peers riding similar gaming and IP momentum by scanning the hand-picked 72 high quality undiscovered gems that share traits with NEXON’s latest guidance story.After a sharp rebound but a weak year to date record, NEXON now sits close to analyst targets and its own record profit guidance. Is the real upside still to come, or was most of it in the recent swing?
Most Popular Narrative: 2% Overvalued
NEXON last closed at ¥3,038 against a narrative fair value of ¥2,971, which the analyst consensus Narrative on Simply Wall St treats as a small premium built on a changing mix of franchises, tools and capital returns.
AI enabled tools and the Monolake initiative, which focus on using decades of player data to improve content creation efficiency and decision making, are intended to raise content output without a matching rise in headcount. This could support higher operating margins and profit per title over time.
See why 1 investors see NEXON as 2% overvalued.
Result: Fair Value of ¥2,971 (OVERVALUED)
Still, the narrative can break if NEXON’s newer titles fail to draw lasting engagement or if cost controls fall short, further squeezing operating margins.
Find out about the key risks to this NEXON narrative.
Another View on NEXON’s Valuation
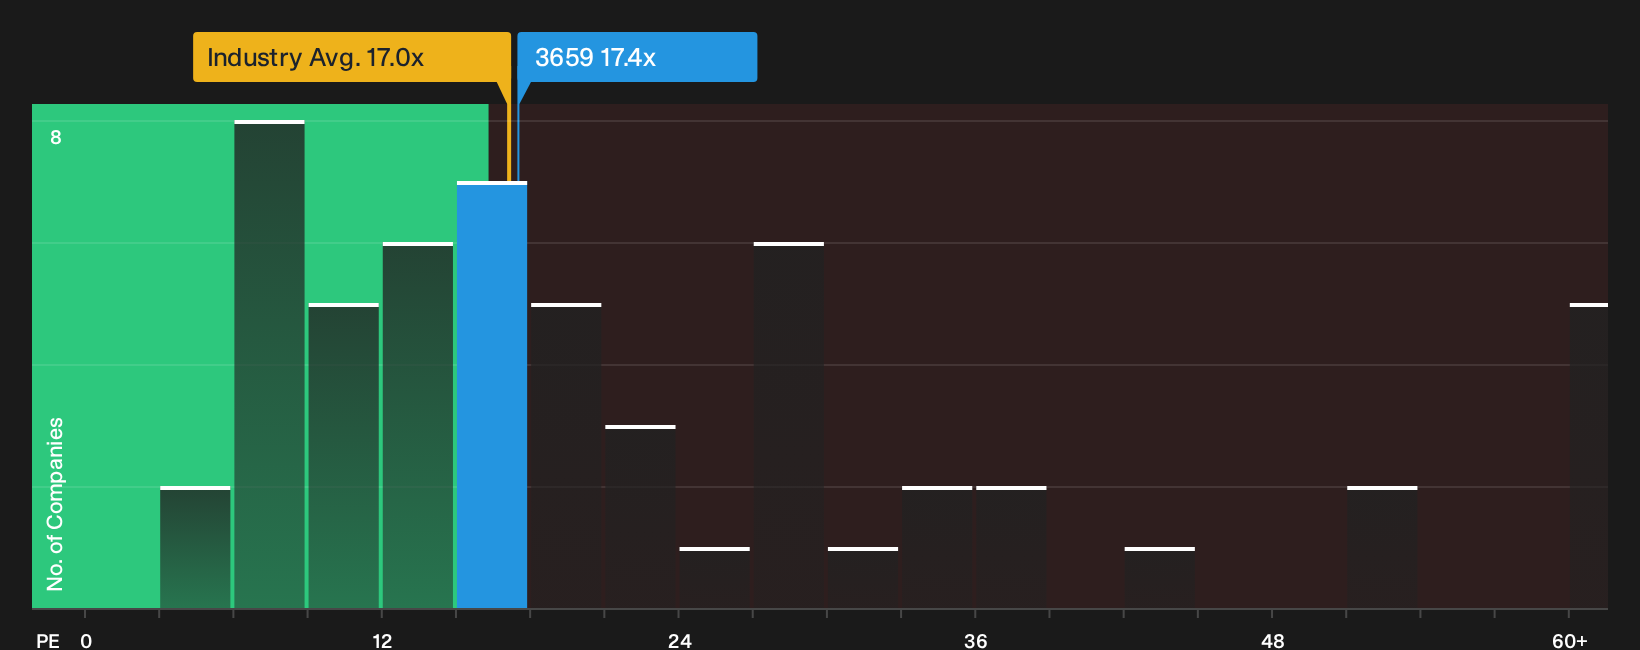
The first fair value story around NEXON leans on a narrative model. A simpler yardstick tells a slightly different story. On 17.4x P/E, the stock trades above the JP Entertainment industry at 16.8x, yet below a fair ratio of 20.4x that the market could move toward over time.
That mix of slightly richer pricing than the sector and a discount to the fair ratio suggests valuation risk is not one sided. There is room for sentiment to shift either way as earnings forecasts and franchise performance are updated. Which side of that gap do you think matters more right now: the peer premium or the fair ratio anchor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on NEXON’s value will always split opinion, so consider acting while sentiment is still forming and test the data against your own thesis. To weigh the balance between risks and potential upside directly, start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond NEXON?
If NEXON’s story has you rethinking your watchlist, do not stop here. The next opportunity could be sitting just outside your usual search box.
- Target resilience by reviewing companies with stronger balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by scanning the 24 high quality undervalued stocks before valuations move away from you.
- Stack potential income streams by checking out the 29 dividend fortresses that focus on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com