
Archer-Daniels-Midland Stock: Is Wall Street Bullish or Bearish?
With a market cap. of around $33 billion, Archer-Daniels-Midland Company (ADM) is a leading global agricultural supply chain manager and processor, connecting local markets with global capabilities to strengthen food security and deliver essential agricultural products. The company is also a major provider of human and animal nutrition, health and wellness solutions, and innovative bio-based products, while advancing sustainability across agriculture and global supply chains.
Shares of the agricultural giant have surpassed the broader market over the past 52 weeks. ADM stock has soared 23.1% over this time frame, while the broader S&P 500 Index ($SPX) has gained 11.3%. Moreover, shares of the company are up 23.4% on a YTD Basis, compared to SPX’s 11.3% rise.
Narrowing the focus, shares of the Chicago, Illinois-based company have also exceeded the State Street Consumer Staples Select Sector SPDR ETF’s (XLP) 18.1% return over the past 52 weeks.
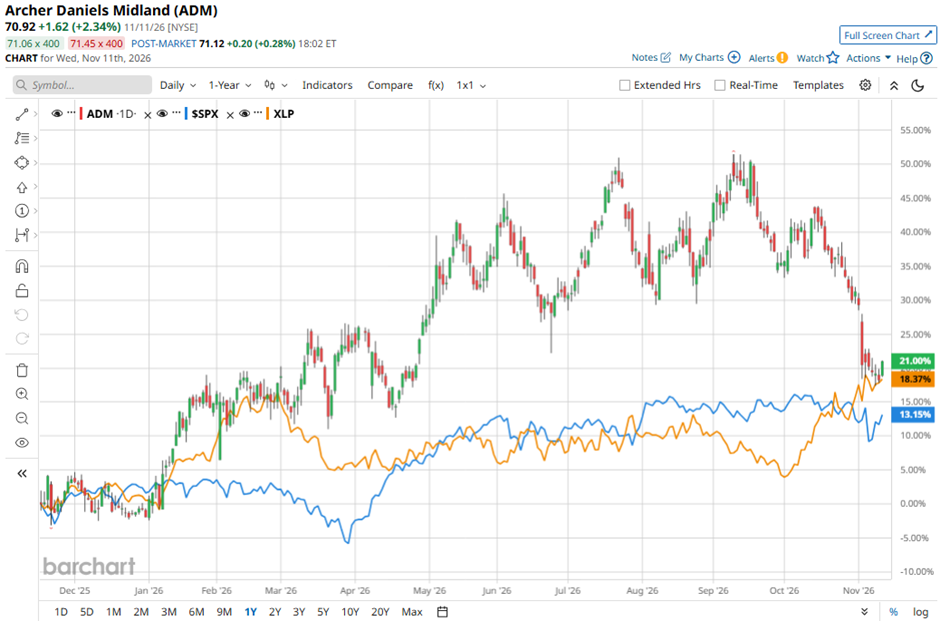
Archer-Daniels-Midland shares fell 6.8% on Nov. 3 despite Q3 2026 adjusted EPS rising to $1.77 and beating the consensus, as revenue of $22.34 billion, up 9.6% year-over-year, missed the estimate. Investor concerns were driven by mixed segment performance: Ag Services & Oilseeds operating profit more than doubled to $778 million but missed the estimate, Nutrition profit of $134 million fell short of the estimate, and Ag Services profit declined 9% to $172 million.
Although ADM raised its 2026 adjusted EPS guidance to $5.65 at the midpoint and lowered its capital expenditure outlook to $1.25 billion, weaker-than-expected results in key segments and the revenue miss likely outweighed the earnings beat and improved guidance.
For the fiscal year ending in December 2026, analysts expect ADM’s adjusted EPS to surge 65.9% year-over-year to $5.69. The company’s earnings surprise history is promising. It beat the consensus estimates in each of the last four quarters.
Among the 10 analysts covering the stock, the consensus rating is a “Hold.” That’s based on one “Strong Buy,” eight “Hold” ratings, and one “Moderate Sell.”
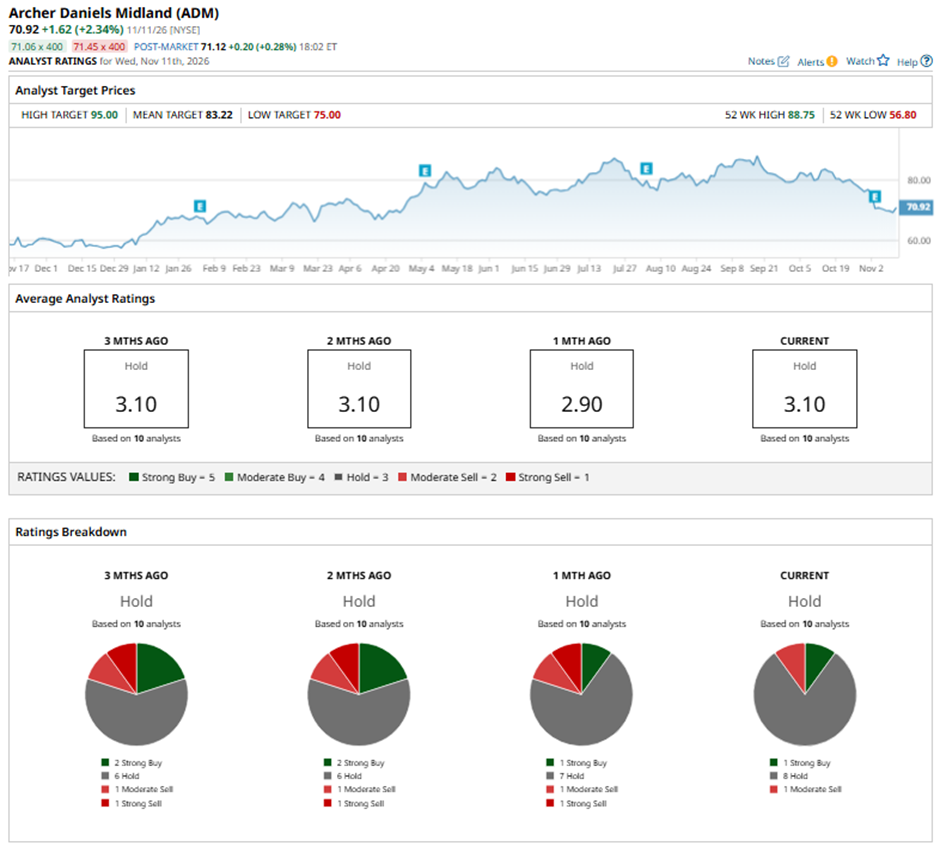
This configuration is slightly less bullish than three months ago, with two analysts suggesting a "Strong Buy."
On Nov. 10, Morgan Stanley analyst Steven Haynes maintained a "Hold" rating on Archer-Daniels-Midland, with a price target of $79.
The mean price target of $83.22 represents a premium of 17.3% to ADM's current levels. The Street-high price target of $95, implying a potential upside of 34% from the current price levels.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.