
How Earnings Beat Will Impact Expeditors Shares Investors
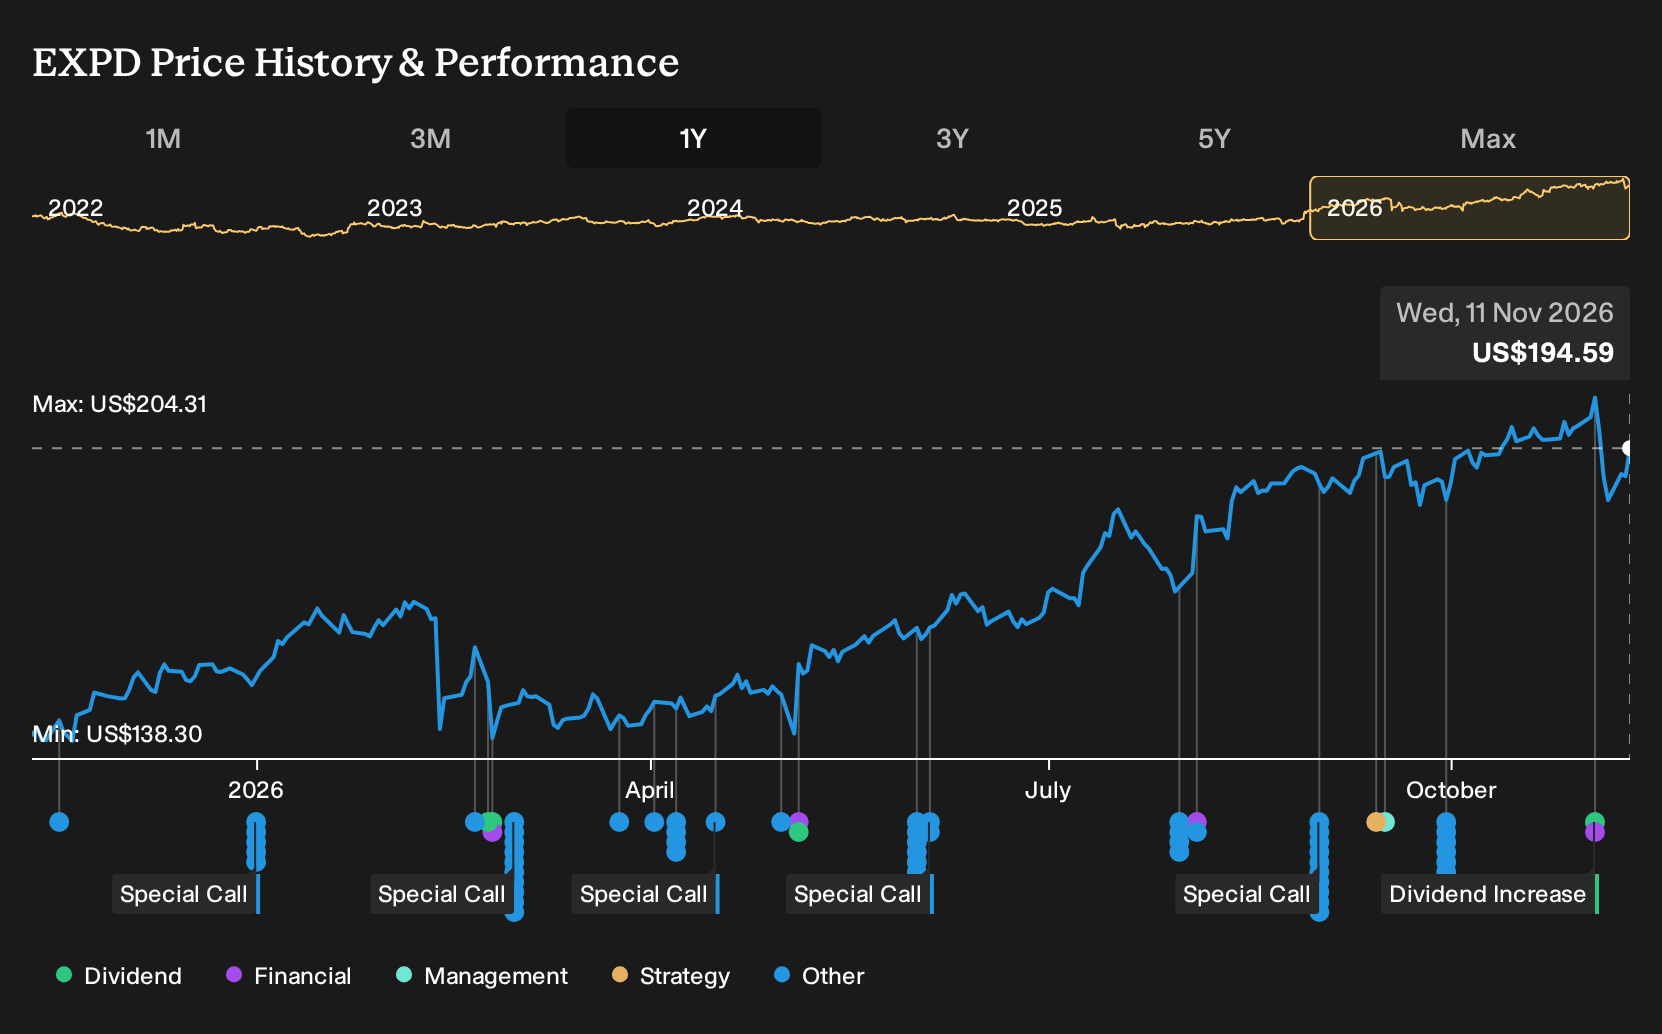
- Expeditors International of Washington reported third quarter 2026 revenue of US$4,107.65 million and net income of US$344.51 million, alongside a semi annual cash dividend of US$0.81 per share declared in November and payable on December 15, 2026.
- Broad strength in airfreight, ocean freight and customs related services, supported by capacity constraints that keep freight rates elevated, underpins the latest jump in earnings at Expeditors International of Washington.
- We will now assess how Expeditors International of Washington’s broad based third quarter earnings beat shapes its longer term investment narrative.
Scan logistics and infrastructure peers that show similar earnings momentum and capital returns using our hand picked 19 high quality undiscovered gems for ideas beyond Expeditors International of Washington.
Expeditors International of Washington Investment Narrative Recap
To own Expeditors International of Washington, you need to be comfortable with a logistics specialist that leans heavily on airfreight, ocean forwarding and customs brokerage, while also pushing productivity through AI and automation. The analyst consensus Narrative on Simply Wall St focuses on execution in higher value services such as Critical Logistics and Aircraft on Ground. The latest quarter confirms strong demand, but the big near term swing factor remains freight capacity and pricing.
The sharp earnings beat supports that near term story, yet it does not fully remove risk. Elevated freight rates and tight capacity still cut both ways. Any cooling in airfreight volumes or customs activity after recent strength could affect revenue and profits, especially as the stock screens as expensive on P/E compared with global logistics peers.
The most relevant update for this earnings release is the semi annual dividend of US$0.81 per share, declared on November 2, 2026 and payable on December 15, 2026. For an investor, that links directly to the core thesis that Expeditors International of Washington can convert fee based logistics work into consistent cash generation.
Reliable capital returns only remain intact if operations support them. Freight forwarding, customs brokerage and time critical services need to continue contributing, and AI and automation need to deliver the planned efficiency gains. If restructuring or softer freight conditions reduce margins, both the dividend and share repurchases may have less room to grow from here.
Expeditors International of Washington’s current earnings are about US$918.8 million, and analysts on Simply Wall St expect earnings to reach roughly US$1.1b by 2029. This implies an earnings increase of about US$181 million alongside forecast revenue of US$13.5b in the same year, based on an assumed 4.0% yearly revenue growth rate.
Uncover why Expeditors International of Washington's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternative view highlights margin risk instead of freight strength. In that storyline, Expeditors International of Washington struggles to lift structurally low 13.5% gross margins, with bearish analysts previously modeling only 1.6% yearly revenue growth to about US$12.6b and earnings of US$1.0b by 2029. That is a much more cautious setup than consensus. The latest dividend hike and earnings beat may prompt those forecasts to shift. As a result, it can be useful to compare multiple narratives before deciding how this stock fits your portfolio.
Explore 2 other Expeditors International of Washington fair value estimates, including one that suggests it could be worth just $187.93.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Expeditors International of Washington research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Expeditors International of Washington. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expeditors International of Washington's overall financial health at a glance.
Looking for more investment ideas beyond Expeditors International of Washington?
If Expeditors International of Washington is only one piece of your watchlist, it can help to line it up against other opportunities that share similar qualities or offer something different. Use the Simply Wall St Screener to scan for stocks that match the mix of quality, value and resilience you want in your portfolio.
- If you want a wider field of candidates that look undervalued on fundamentals, line up potential ideas with our 32 high quality undervalued stocks.
- For investors who care most about balance sheet strength and financial resilience, start by filtering companies using the list of solid balance sheet and fundamentals (23 results).
- If capital preservation and steadier profiles matter more to you than headline growth, narrow the universe with our 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com