
Kraft Heinz (KHC) Stock May Be Reasonable Despite Its $650M Coffee Sale
Kraft Heinz has seen a mixed share-price path over the past few years, and the latest portfolio reshuffle has put fresh attention on whether today's valuation is really supported by its sales base. With the stock now reflecting years of uneven returns, the key issue is how the current price lines up against what the business actually generates in revenue.
- Over the past 5 years the Kraft Heinz share price has fallen 14.6%, which puts extra weight on whether the current market value still lines up sensibly with the scale of its sales.
- The planned US$650m sale of the North American coffee business, with most of the after tax proceeds earmarked for debt reduction, can reshape future interest costs and may support how investors think about the value of the remaining revenue base.
- There is a second opinion on Kraft Heinz worth weighing. See what analysts think Kraft Heinz's shares could be worth.
The issue now is whether Kraft Heinz's current share price is justified by the level and quality of its sales.
If you want a broader starting point for research alongside Kraft Heinz, you can filter for other companies using the 32 high quality undervalued stocks.
Is Kraft Heinz a Bargain on Sales?
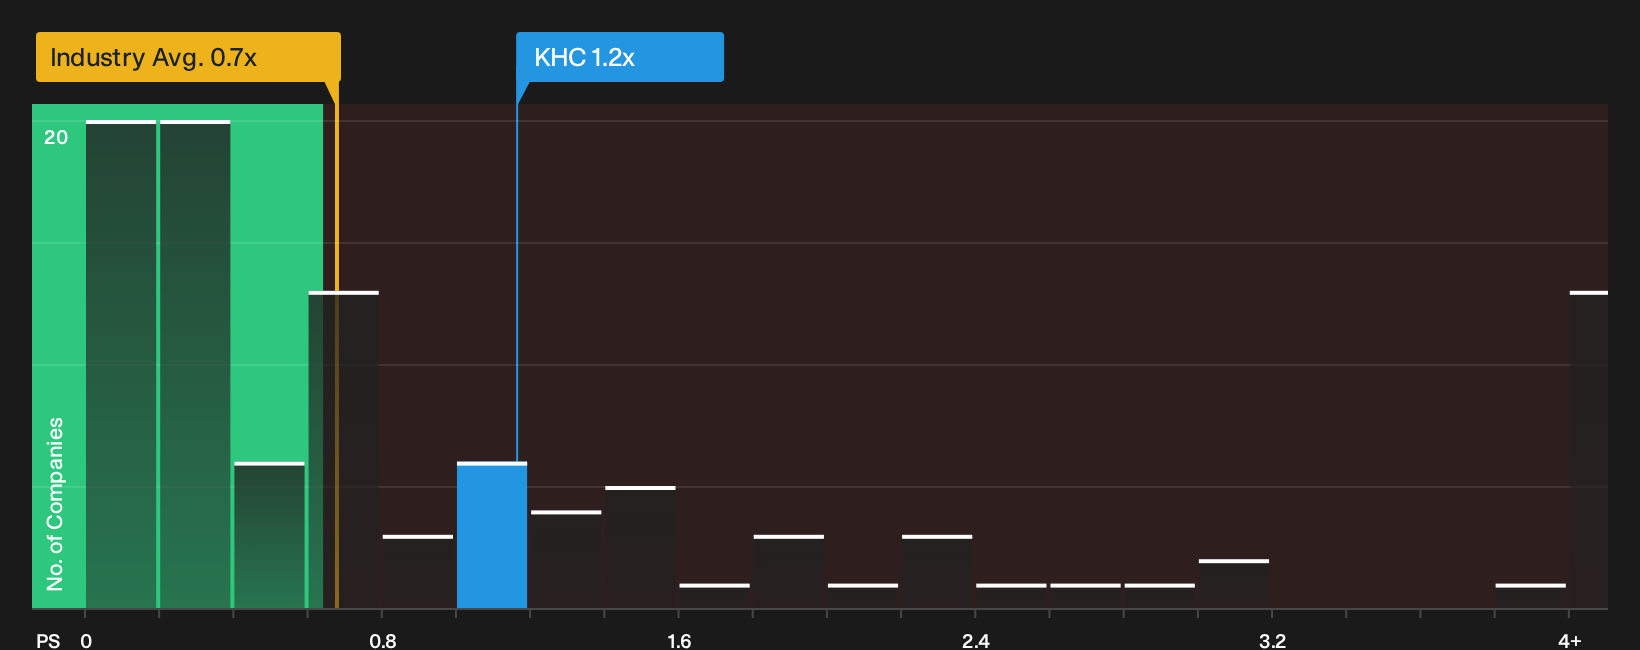
P/S fits Kraft Heinz because this is a mature branded food producer where investors often judge value against the revenue base rather than headline earnings swings. On that yardstick, the stock trades on a P/S of about 1.2x, below the peer group average of roughly 1.5x and above the broader food industry level of around 0.7x.
Because the current P/S is lower than what a tailored fair multiple would suggest for Kraft Heinz, the valuation appears lower on this measure. Despite the planned US$650m sale of the North American coffee unit and the focus on higher growth core labels, the market is still pricing the shares at a discount to the revenue multiple implied by that fair-value framework. Explore the numbers behind Kraft Heinz's P/S valuation.
The Kraft Heinz Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Kraft Heinz's valuation puzzle leaves off by spelling out the mix of future growth, margins and earnings that would need to play out for the stock to be worth materially more or less than it is today on the market. They sit on Simply Wall St's Community page and turn a single P/S or model output into a set of real world assumptions, so you can monitor whether the story that underpins that number still holds over time.
Bulls and bears are looking at the same Kraft Heinz update and reaching very different conclusions about what the recent moves really signal.
Bull case: 31% undervalued
According to woodworthfund, an investor in the Simply Wall St Community, Kraft Heinz looks like a repair story with cash flow and brand spend doing the heavy lifting.
"This is not what a dying brand portfolio looks like; it is what a neglected one looks like when somebody starts feeding it again..."
Discover why this Narrative puts Kraft Heinz at 31% undervalued.
Bear case: 21% overvalued
The bearish analyst Narrative on Simply Wall St sees the same spending plans and category pressures as reasons to question how much is already baked into Kraft Heinz shares.
"The numbers imply the share price already reflects successful execution on higher marketing spend, productivity savings, and emerging market expansion..."
Explore why this Narrative puts Kraft Heinz at 21% overvalued.
Kraft Heinz valuation is only part of the story
Price tags and revenue multiples only go so far, because Kraft Heinz also carries specific risk checks that flag issues investors may want to weigh before getting comfortable with the shares. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com