
How Strong Earnings Results Will Impact Primerica (PRI) Investors
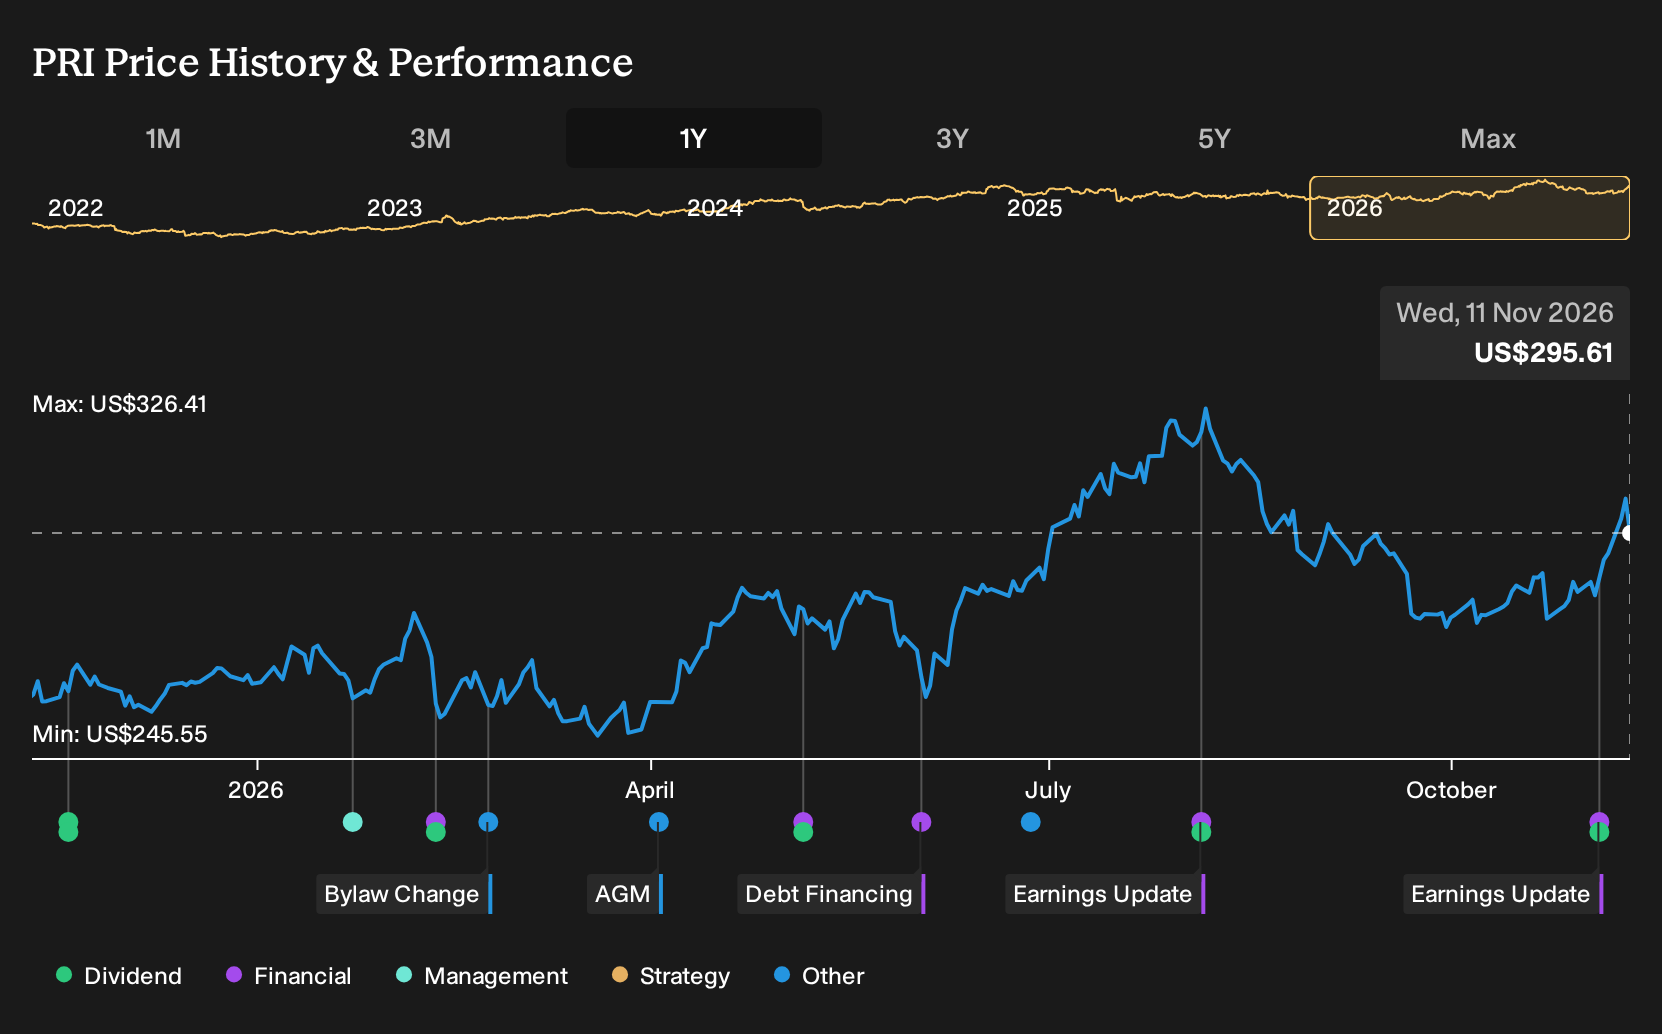
- Primerica reported third quarter 2026 revenue of US$901.65 million and net income of US$209.13 million, with earnings per share from continuing operations modestly higher than the same period a year earlier, and also released stronger year-to-date figures through September.
- The combination of higher earnings, US$392.22 million of completed share repurchases through September 2026, and an affirmed US$1.20 quarterly dividend highlights Primerica's focus on returning capital while operating a capital-light model.
- We will look at how Primerica's investment narrative is affected by these stronger earnings figures and sustained buybacks and dividends.
Primerica Investment Narrative Recap
To own Primerica, you need to be comfortable with a middle income focused insurer that leans on a large in-force term life book while steadily building fee based Investment & Savings Products. The analyst consensus narrative on Simply Wall St assumes that stabilising distribution productivity and getting more out of recent technology spending are key. The latest quarter shows higher revenue and earnings per share, which supports that operating thesis rather than shifting it.
The more immediate swing factor still sits in term life new business and the health of the licensed representative base, given earlier pressure on policies and force size. Rising insurance and other operating expenses linked to technology projects also remain a live risk. The fresh Q3 numbers do not remove those issues but suggest the business is absorbing them for now.
The most relevant update here is the earnings release for the quarter and nine months to 30 September 2026. Primerica reported Q3 revenue of US$901.65 million and net income of US$209.13 million, with diluted earnings per share from continuing operations at US$6.76. Over nine months, revenue reached US$2.64 billion and net income US$601.5 million.
Those figures sit alongside catalysts such as the shift toward fee based Investment & Savings Products and ongoing technology investment intended to support productivity. They also intersect with the risks around higher operating costs and pressure on new term life policies. For you as a shareholder, the question is how convincingly Primerica converts this earnings profile into sustained cash generation while managing those operational headwinds.
Primerica's narrative projects US$4.1b revenue and US$871.5m earnings by 2029. This leans on analysts assuming 5.4% yearly revenue growth and about a US$77.9m earnings increase from US$793.6m today.
Uncover why Primerica's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$324.50 to US$746.93, which signals that views on Primerica differ sharply. Those retail perspectives sit beside fresh considerations around term life pressure, rising technology spend, and the completed US$392.22 million buyback. All of these factors are worth weighing before settling on your own view.
Explore another Primerica fair value estimate, including one that suggests up to 153% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Primerica research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Primerica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Primerica's overall financial health at a glance.
Looking For More Ideas Beyond Primerica?
Once you have a handle on Primerica's story, it can help to set it alongside other opportunities that share similar traits or offer a very different risk and reward profile. The Simply Wall St Screener lets you do that quickly by filtering for the kind of balance sheets, income profiles, or payout characteristics that match what you want to own.
- If resilience matters most to you, start with companies that combine sturdier finances and lower volatility by checking out 30 resilient stocks with low risk scores.
- If you prefer businesses that already generate cash and trade on restrained expectations, narrow your search using the 32 high quality undervalued stocks.
- If steady income is a priority, focus on companies with higher yields and consistent payments through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com