
Northern Trust (NTRS) Expands Microsoft AI Tie Up On Questions Of Valuation
Northern Trust (NTRS) is in focus after extending its work with Microsoft to roll out an AI client onboarding agent on its Asset Servicing Front Office Solutions platform, targeting faster and more standardized data processing.
Against this backdrop, Northern Trust shares trade at US$178.71, with a 30-day share price return of 5.61% but a 90-day share price move that is down 6.18%. Meanwhile, the 1-year total shareholder return of 37.84% and 3-year total shareholder return of about 1.6x point to strong longer term momentum.
Scan how Northern Trust’s AI push compares with peers by reviewing a curated set of financially solid opportunities in our list of solid balance sheet and fundamentals (23 results).
Northern Trust shares have already delivered a strong 1 year run, yet the stock still trades below one internal estimate of intrinsic value. Is the recent AI push a sign that more upside is being priced in, or is it already reflected?
Most Popular Narrative: 3% Undervalued
On the analyst consensus Narrative on Simply Wall St, Northern Trust screens as slightly undervalued, with a fair value of $184.27 against the last close at $178.71. That small gap, combined with detailed revenue and earnings assumptions, frames how the recent AI onboarding move fits into a broader efficiency story.
Technology and AI programs, including AI assisted code development and a plan for tech spend growth to moderate toward mid single digit rates, point to a multi year effort to raise productivity and support margin expansion, helping explain why current valuation already reflects improved net margins.
See why 13 investors see Northern Trust as 3% undervalued.
Result: Fair Value of $184.27 (UNDERVALUED)
Still, the story can change if AI projects end up costing more than they save, or if fee pressure in liquidity products squeezes Northern Trust’s operating leverage.
Find out about the key risks to this Northern Trust narrative.
Another View: Northern Trust Through The Earnings Multiple
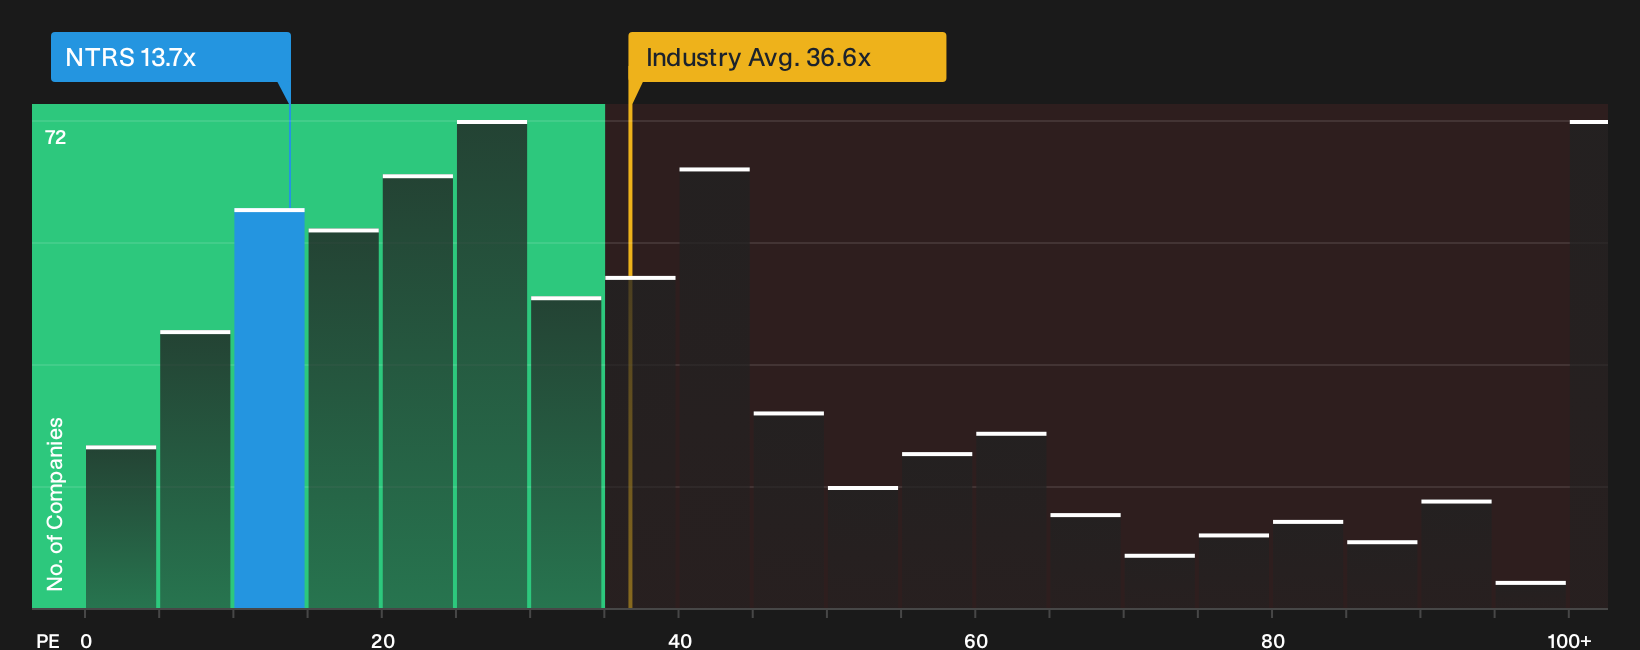
The SWS DCF model points to Northern Trust trading about 9.6% below an internal future cash flow value, yet the P/E picture is more nuanced. The stock sits at 13.7x earnings, slightly above a 13.5x fair ratio and peer average, but well below the 36.3x industry level. Is that a margin of safety or a signal of limited re rating potential?
To see how this earnings based snapshot lines up with a full valuation breakdown, including where the fair ratio might drift over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Does the Northern Trust story sound cautiously optimistic to you or too generous on AI execution risk? Put the numbers side by side, then weigh those 3 key rewards.
Looking for more investment ideas beyond Northern Trust?
Northern Trust might fit your watchlist, but your next opportunity could be in a very different corner of the market.
- Target potential mispricing by scanning a curated pool of quality stocks that screens for value and resilience through the 32 high quality undervalued stocks.
- Lock in income potential by reviewing companies with robust cash generation and yields screened as 6 dividend fortresses.
- Reduce portfolio stress by focusing on stability and financial strength through a 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com