
Travelers Companies (TRV), What Is Drawing Fresh Attention Now?
Board refresh and what it could mean for Travelers Companies
Travelers Companies (TRV) has expanded its board to ten directors and added Lesley Goldwasser, linking the insurer more closely to capital markets and governance expertise that investors now need to weigh.
Recent trading paints a mixed picture. Travelers Companies’ share price is down over the past week but has a 30 day share price return of 7.47% and a year to date share price return of 40.07%, while the 5 year total shareholder return of 180.83% reflects a strong longer term payoff. As a result, recent board changes arrive as momentum has already been building and may now be reassessed through a capital markets lens.
Scan for other insurers with similar momentum and boardroom shifts by jumping into our curated list of 30 resilient stocks with low risk scores while Travelers Companies reshapes its governance profile.
Bulls see Travelers Companies pairing boardroom firepower with a strong multi year shareholder payoff. Bears point to recent revenue and net income pressure. Which case does the current valuation strength support?
Most Popular Narrative: 5.1% Overvalued
Travelers Companies last closed at $399.46 against a narrative fair value of $380, and according to LunaRodas, a Simply Wall St Community investor who wrote the narrative, that gap comes down to how management talks about results versus what the numbers actually show.
The doctrine always had an exit, and management is now framing that exit as the primary strategy. That is a shift in emphasis, not evidence that Travelers is cutting price across the book.
Price competition is no longer described as a mistake but as an option.
See why 1 investors see Travelers Companies as 5% overvalued.
Result: Fair Value of $380 (OVERVALUED)
Still, Travelers Companies faces narrative risk if expense guidance drifts higher again or if reserve assumptions on asbestos and liability prove less resilient than currently implied.
Find out about the key risks to this Travelers Companies narrative.
Another View on Travelers Companies Valuation
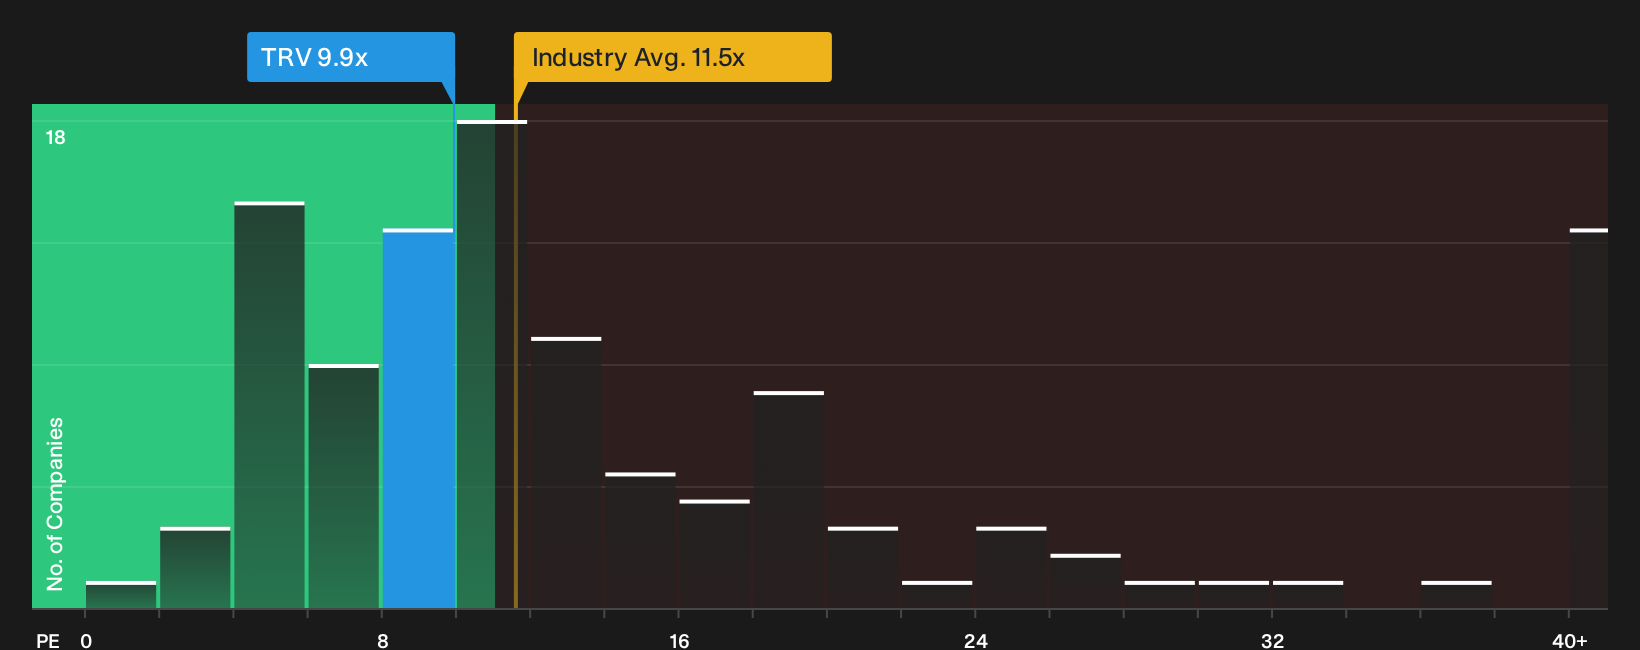
The first community narrative pegs Travelers Companies at about 5.1% above its $380 fair value, yet the market is also pricing the insurer on a P/E of 9.9x. That sits below the US Insurance industry on 11.5x and only just above the peer group on 9.6x.
The fair ratio here is 10.2x, which is close to where Travelers Companies trades already. For readers, that means the share price leaves limited room for clear mispricing on earnings alone and keeps the focus on how much narrative and forecast risk you are willing to accept at this level.
For a closer look at how this earnings-based view stacks up against peers, and where valuation risk might cluster if sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Travelers Companies so far. If you want to move quickly and base your own call on the numbers, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Travelers Companies?
If Travelers Companies has sharpened your focus on price, quality, and risk, broaden your watchlist now so you are not relying on a single story.
- Target higher quality at a sensible entry point by scanning our curated pool of 32 high quality undervalued stocks that pair fundamentals with disciplined pricing.
- Strengthen portfolio resilience by hunting through a list of solid balance sheet and fundamentals (23 results) that can better absorb shocks when conditions turn.
- Get ahead of the crowd by tracking a 19 high quality undiscovered gems before they attract wider attention and potential re-rating.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com