
Lucid (LCID) Stock Still Looks Above Fair Value On Its 99% Fall
Lucid Group has seen its share price move sharply over recent years. The real question for anyone looking at the stock today is how well that market value lines up with the revenue the electric vehicle maker is currently generating. After such a volatile ride, the key issue is whether Lucid Group's sales base is solid enough to support the latest rebound in the price.
- Over the past 5 years, Lucid Group's share price has fallen 99.2%, which puts the focus squarely on what investors are now paying for each dollar of the company's sales.
- Fresh funding support from Saudi Arabia's Public Investment Fund and reduced cash burn can ease near term funding pressure, which may influence how much value the market assigns to Lucid Group's existing and future revenue stream.
- Your read on Lucid Group is one view; the desks covering it have another. See what analysts think Lucid Group's shares could be worth.
For investors, the debate is whether Lucid Group's current share price is appropriately supported by its sales performance today and the revenue the business is working toward over time.
If you want to stress test the valuation of Lucid Group against a wider set of electric vehicle and growth stories, compare it with 32 high quality undervalued stocks.
Does Lucid Group Look Pricey on Sales?
P/S fits Lucid Group because the company is still loss making on free cash flow, so sales give you a cleaner anchor than earnings.
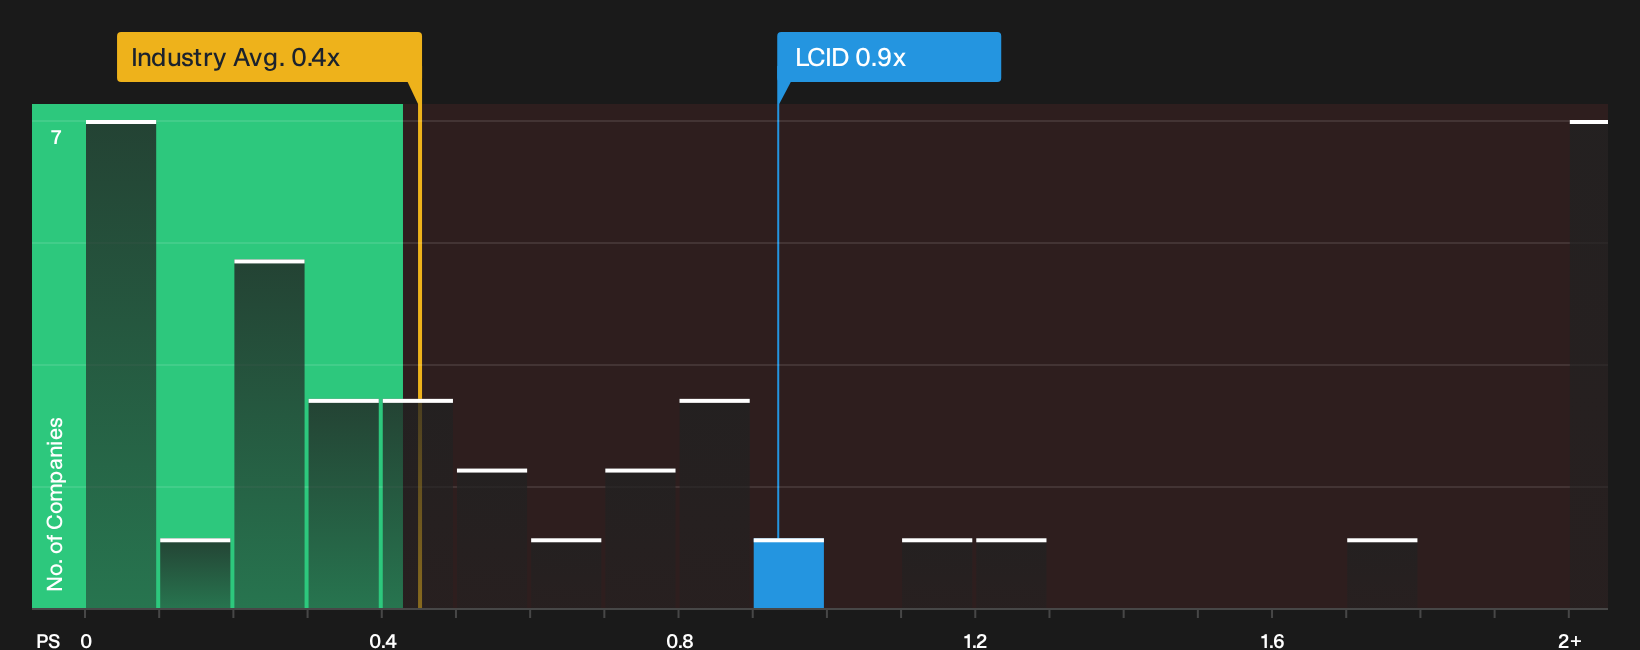
On this yardstick, Lucid trades on a P/S of 0.9x, compared with an auto industry average around 0.4x and a peer group closer to 0.4x as well. The tailored fair multiple that adjusts for Lucid Group's size, margins and risk profile comes in much lower, so the current valuation screens overvalued on this framework and the gap is wide enough that it is better read as a warning than a precise target. Despite the expanded credit line from Saudi Arabia's Public Investment Fund easing liquidity worries into 2027, the stock still prices each dollar of revenue well above sector norms.
For readers, that means the recent optimism around lower cash burn and new funding support is already reflected in the P/S, so you would need strong conviction about Lucid Group's ability to convert its sales base into a healthier business over time to be comfortable paying this kind of revenue multiple. Explore the numbers behind Lucid Group's P/S valuation.
The Lucid Group Narrative: What Would Justify Today's Price?
Narratives for Lucid Group pick up where the P/S puzzle leaves off, by spelling out which future paths for growth, margins and earnings would need to play out for the stock to end up worth meaningfully more or less than today’s market price, and they sit on Simply Wall St’s Community page. Instead of just giving a single valuation number, these scenarios lay out the future that number leans on so you can watch over time whether those conditions actually show up.
Bullish and bearish Lucid Group views are split on whether new platforms and fleet deals can overcome weak unit economics and recent execution issues.
Bull case: 50% undervalued
The analyst consensus Narrative on Simply Wall St frames the upside case around execution on costs, new models and software heavy revenue.
"The upcoming midsize EV platform, with targeted 60 to 70% unit cost reductions versus Gravity levels and high parts commonality between Cosmos and Earth, is designed to lower Lucid Group’s cost of goods sold and broaden its customer base…"
Discover why this Narrative puts Lucid Group at 50% undervalued.
Bear case: 22% overvalued
According to DanielOliveira, an investor in the Simply Wall St Community, recent quarterly results underline pressure on pricing and demand.
"The miss held. Revenue was $350.3 million on the 3,806 deliveries Lucid had already reported, against my $376.6 million and the $399.1 million consensus…"
Explore why this Narrative puts Lucid Group at 22% overvalued.
One more Lucid Group angle worth checking before you move on
Before you stop researching Lucid Group, it is worth looking at who is steering the business and how their incentives line up with yours. That alignment can shape what happens next. See who runs Lucid Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com