
Is Group 1 Automotive (GPI) Reasonably Priced on Future Cash Flow?
Group 1 Automotive has seen its share price move sharply over different time frames, which puts fresh attention on what investors are really paying for its cash flows. With the stock now around US$270, the key issue is how that price lines up with the stream of cash the dealership group can generate over time.
- Over the past 5 years, Group 1 Automotive has returned 47.8%, which raises the question of how much long term cash flow strength is already reflected in the current valuation.
- The business relies heavily on converting vehicle sales, parts, service, and financing activity into steady free cash flow, so any change in margins or capital intensity can materially shift what those future cash flows are worth today.
- What if you looked at Group 1 Automotive through its earnings instead? See what Group 1 Automotive's 8.5x P/E says about the price.
The issue now is whether Group 1 Automotive's present share price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
If you are evaluating Group 1 Automotive based on its cash flows and want a broader starting point for research, compare it with companies in the 32 high quality undervalued stocks.
Is Group 1 Automotive Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on the cash that Group 1 Automotive can return to shareholders over time. The model starts from last twelve month free cash flow of about $277.4 million and then assumes that future free cash generation grows from that base rather than shrinking. That framing matters for a dealer network where a lot of value hinges on how reliably day to day operations translate into surplus cash.
Analyst and model estimates point to higher annual free cash flows by the late 2020s and early 2030s, with projected figures rising into the mid to high $400 million range and beyond in later years. When those future streams are discounted back, the combined value comes out substantially above the current share price of $270.27. For anyone assessing Group 1 Automotive on cash generation rather than just reported earnings, the DCF output indicates that the market price is not fully reflecting the projected cash flow profile. Find out what Group 1 Automotive could be worth using our Discounted Cash Flow (DCF) estimate.
The Group 1 Automotive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle for Group 1 Automotive leaves off and explain which paths for growth, profitability and earnings would need to occur for the stock to be worth meaningfully more or materially less than the current share price. Each scenario links its figures to a clear view on how Group 1 Automotive's expansion, margins and risk profile could change over time, giving you a reference point you can revisit as new information becomes available.
Group 1 Automotive splits opinion, with one view seeing meaningful upside from the current setup and the other flagging tight room for error.
Bull case: 17% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on pooled forecasts and targets.
"The current valuation suggests that the market is not fully pricing in Group 1 Automotive's planned mix shift toward higher margin dealerships, an expanding contribution from aftersales and F&I, and progress on its cost reduction and capital allocation plans…"
Discover why this Narrative puts Group 1 Automotive at 17% undervalued.
Bear case: 8% overvalued
This angle is drawn from the bearish analyst Narrative on Simply Wall St, which leans into the most cautious forecasts and price target.
"Despite management targeting denser clusters of premium dealerships through acquisitions like the pending Hennessy deal, the US$1.25b of new senior unsecured notes tied to that transaction raises interest expense and temporarily elevates rent adjusted leverage…"
Explore why this Narrative puts Group 1 Automotive at 8% overvalued.
Group 1 Automotive has one more signal worth checking before you decide
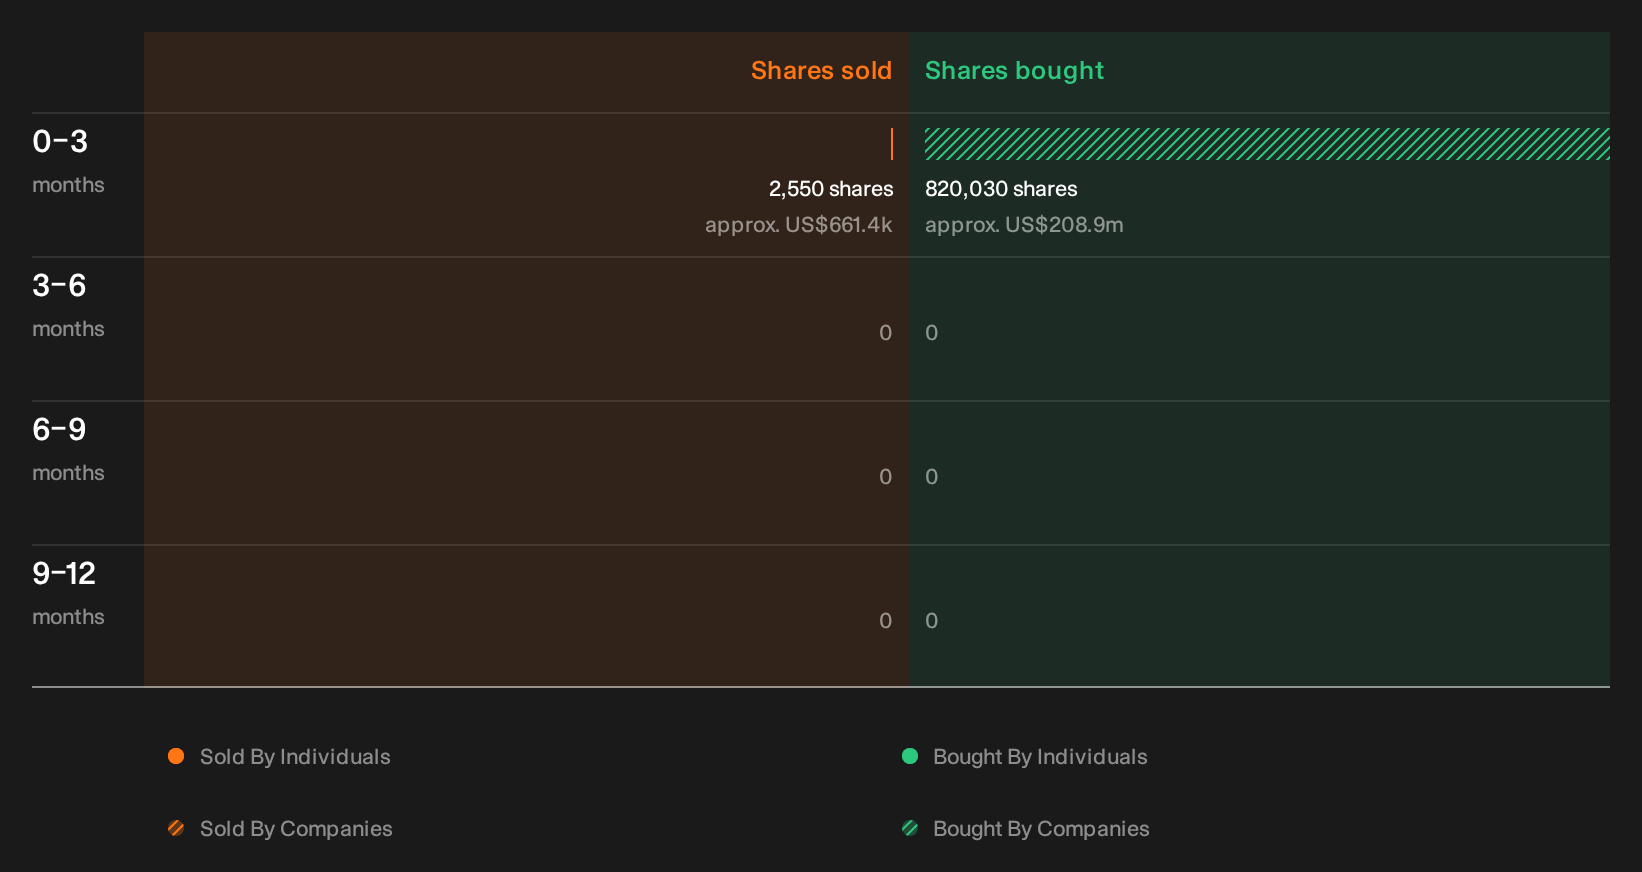
Price, cash flows and narratives tell only part of the story for Group 1 Automotive, because recent director and executive share sales have been picked up by our checks and the who, how much and why are still for you to unpack. See the recent insider selling flagged for Group 1 Automotive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com