
Learn Why The Bull Case For Coeur Mining Stock Could Change Following Earnings Estimate Cuts
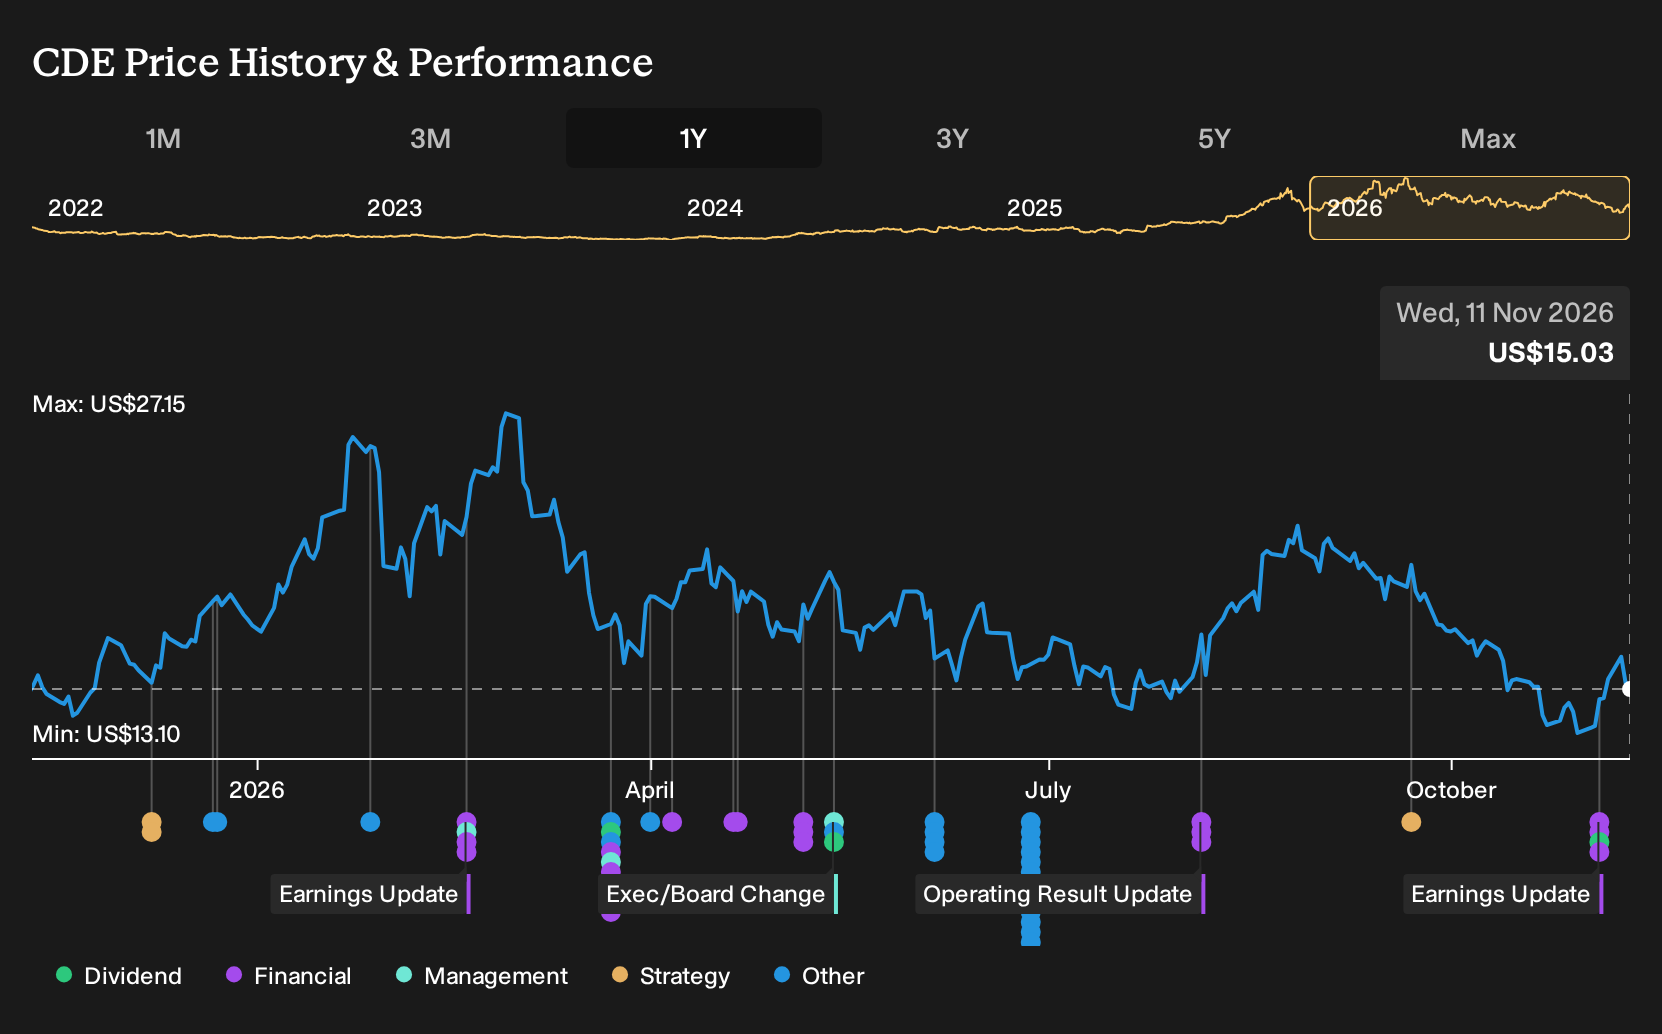
- Coeur Mining reported third quarter 2026 sales of US$983.62 million and net income of US$109.38 million, alongside higher gold output and lower silver volumes. The company also declared a US$0.02 per share dividend and completed a US$221.03 million share repurchase program.
- The company paired stronger year to date net income of US$478 million and increased gold production with lower earnings per share and reduced silver output, presenting a mixed operating picture that coincides with more cautious analyst earnings estimates.
- This article examines how Coeur Mining's investment narrative is affected by weaker earnings estimates despite higher gold production.
Scan beyond Coeur Mining's latest earnings and guidance and compare its profile with other precious metal producers using our curated list of 33 elite gold producer stocks.
Coeur Mining Investment Narrative Recap
To own Coeur Mining, you need to be comfortable with a precious metals producer that is currently leaning on higher gold output while silver volumes soften and earnings per share come under pressure. The analyst consensus Narrative on Simply Wall St focuses on production growth and efficiency gains. Recent results show strong year to date net income and revenue paired with lower quarterly EPS, so the near term catalyst is operational delivery on current guidance rather than financial optics.
The biggest near term risk sits in operational and regulatory execution. Coeur Mining depends on existing reserves, new drilling and large projects that can face permitting delays, all of which can affect mine life and production. In the short term, weaker earnings metrics and more cautious analyst estimates create less room for missteps, even if revenue and output remain solid.
The most relevant update for that backdrop is Coeur Mining's 2026 production guidance. Management outlined expected ranges of 630,000 oz to 750,000 oz of gold, 18.68 million oz to 21.93 million oz of silver and 40 million lbs to 50 million lbs of copper. For you as a shareholder, the practical question is how closely actual quarterly production tracks those bands.
Guidance now anchors the key catalyst, which is efficient ramp up and stable output across the mine portfolio after a period of heavy investment and past dilution. Any persistent shortfall against the stated ranges, especially in silver where volumes already eased, would test the growth story that underpins the analyst consensus Narrative on Simply Wall St and could amplify existing concerns around costs, permitting and mine life replacement.
Coeur Mining's outlook forecasts US$7.9b in revenue and US$2.5b in earnings by 2029. This corresponds to 35.8% annual revenue growth and an earnings increase of about US$1.65b from current earnings of US$850.4m.
Uncover why Coeur Mining's fair value indicates a 50% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Coeur Mining focuses on its capital return plan rather than the production risk that worries consensus analysts. Before this earnings release, the most optimistic forecasts were built around earnings reaching about US$3.0b and revenue near US$8.3b by 2029. Those higher expectations, plus the US$750m buyback and dividend framework, create a far more upbeat story than the recent Zacks Rank downgrade. The fresh Q3 results and the upcoming London conference could push those viewpoints further apart.
Explore 6 other Coeur Mining fair value estimates, including one that suggests as much as 100% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Coeur Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coeur Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coeur Mining's overall financial health at a glance.
Looking for more Coeur Mining style investment ideas?
If the mixed story around Coeur Mining has you thinking about portfolio balance, it can help to line it up against other opportunities with different risk and return profiles. The Simply Wall St Screener lets you filter for specific traits instead of trawling through tickers one by one.
- If you want potential mispricings with solid fundamentals, start by scanning our 32 high quality undervalued stocks that match strict quality and valuation filters.
- For income focused investing, narrow your research to companies that pay meaningful yields and have the balance sheet to support them by reviewing our 6 dividend fortresses.
- To tilt toward resilience and capital preservation, concentrate on companies with stronger financial footing than the broader market using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com