
W. P. Carey (WPC) Stock Trades At A Discount To Fair Value
W. P. Carey has delivered a 36.8% share price gain over the past three years, so the obvious question for you today is whether that performance is still backed by the real estate investment trust's earnings power. With the stock recently closing at US$64.84, the current valuation puts a spotlight on how much profit the underlying portfolio is expected to generate and how reliable that income stream looks.
- A 36.8% return over three years puts real money on the line for holders. That makes it important to ask whether W. P. Carey's earnings can support that kind of share price progress.
- The business model is built around long term, lease backed cash flows, so the level and stability of earnings can shape how investors judge what they are willing to pay for each dollar of profit.
- The analysts covering W. P. Carey have run their own numbers. See what analysts think W. P. Carey's shares could be worth.
The stock's next move may depend on whether W. P. Carey's current price is well supported by the earnings it is generating today and is expected to produce over time.
If you want a broader yardstick for judging W. P. Carey's earnings profile, you can compare it with companies in our 32 high quality undervalued stocks
Is W. P. Carey a Bargain on Earnings?
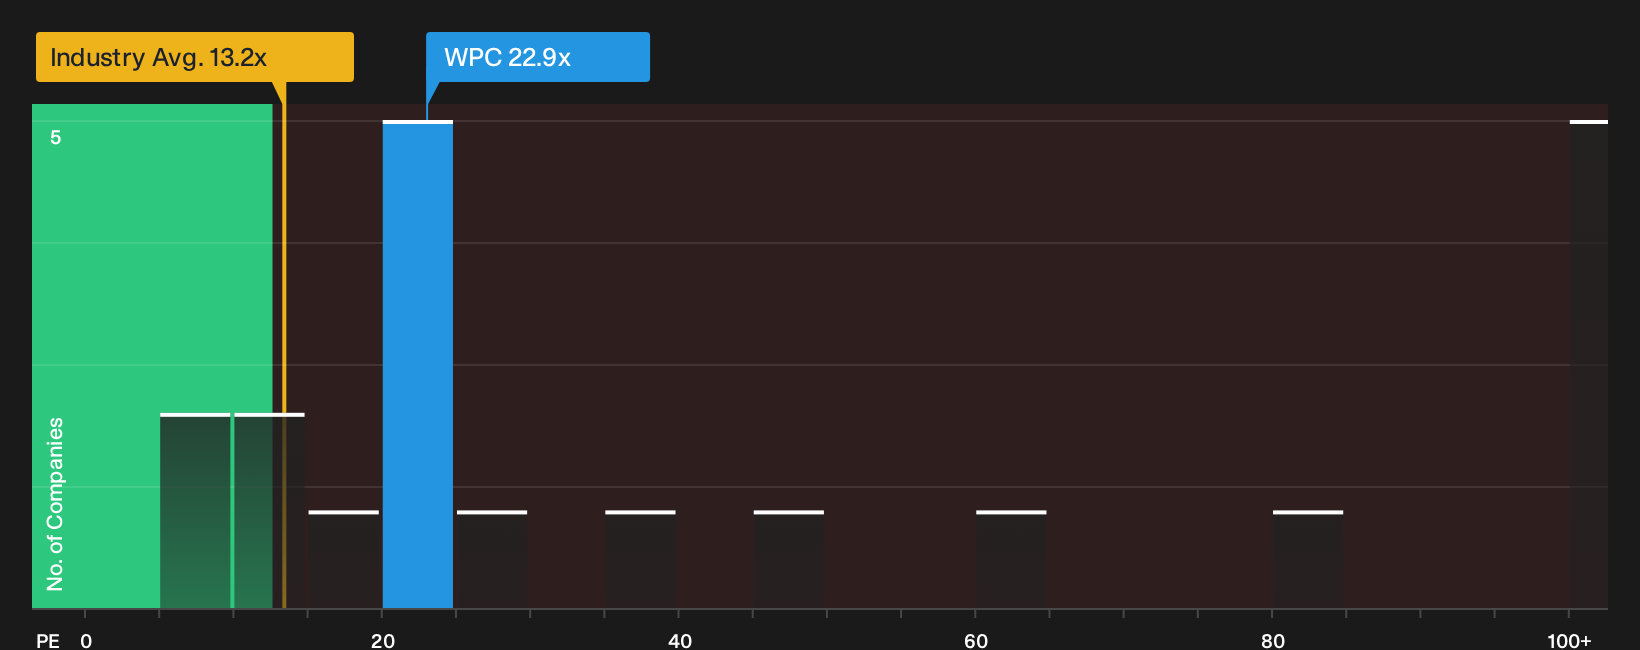
The P/E ratio fits W. P. Carey because investors often look at earnings relative to price when judging income focused real estate trusts. On that score, W. P. Carey trades on a P/E of 22.9x, which is well above the REITs sector average of 13.2x. Against its direct peer group, where the typical P/E sits around 71.0x, the stock carries a lower earnings multiple than many comparable landlords.
A model that blends W. P. Carey’s earnings profile, size and sector into a tailored reference multiple points to a higher P/E than where the shares currently change hands. That places the stock below the level suggested by this fair value yardstick, even though it screens richer than the broader REIT industry. For you as a holder or potential buyer, the key question is whether the quality and reliability of W. P. Carey’s earnings justify a P/E that is below this company specific benchmark but above the wider sector average. Explore the numbers behind W. P. Carey's P/E valuation.
The W. P. Carey Narrative: What Would Justify Today's Price?
Narratives for W. P. Carey pick up where the valuation puzzle leaves off and spell out which earnings, growth and margin paths would need to play out for the stock to look meaningfully cheaper or more expensive than its current price. Each one links its number to a specific view on how W. P. Carey’s growth, profitability and risk profile might evolve and gives you a reference point you can return to as new information comes through on the Community page.
Views on W. P. Carey split between one side seeing meaningful upside and another arguing the price already reflects the story.
Bull case: 12% undervalued
According to the analyst consensus Narrative on Simply Wall St, the optimistic view leans heavily on W. P. Carey’s investment pipeline and lease structure.
"Current valuation implies the share price does not fully reflect the raised 2026 AFFO guidance, the prefunded investment pipeline of up to $2.1b, and the company’s shift toward long-lease industrial, warehouse and retail properties…"
Discover why this Narrative puts W. P. Carey at 12% undervalued.
Bear case: 26% overvalued
TradingClimbers, a Simply Wall St Community investor who wrote the Narrative, focuses on price and a thin margin of safety for W. P. Carey.
"What holds me back is price: the stock trades above fair value and above my entry filters, so the buy signal stays Risky…"
Explore why this Narrative puts W. P. Carey at 26% overvalued.
One more W. P. Carey angle worth checking
There is a second lens that can help you stress test W. P. Carey’s current share price, which is how professional analysts currently map out the business a few years from now. Explore where analysts expect W. P. Carey to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com