
Robert Half (RHI) Promotes New Search Chief, Is The Stock Already Pricey?
Robert Half (RHI) just reshaped its leadership bench by promoting David King to President of Executive Search for the Americas and Europe, a move that puts senior hiring and C-suite recruitment squarely in focus.
Recent trading tells a mixed story for Robert Half. The share price has climbed 22.7% over the past month and is up 54.4% year to date. However, the 3 year total shareholder return has declined 38.3% and the 5 year total shareholder return has fallen 55.7%. This points to improving short term momentum against a weaker long term record as investors weigh the latest leadership changes and the recent dividend affirmation against that history.
Spot fresh leadership-driven stories like Robert Half by scanning our hand picked 19 high quality undiscovered gems with strong fundamentals that may be flying under most investors' radar.Bulls see Robert Half as a reset story after fresh leadership moves and a sharp rebound in recent returns. Bears point to the weak 3 and 5 year record. Which side does the current valuation support?
Most Popular Narrative: 7% Overvalued
Robert Half closed at $42.22, which sits above the analyst consensus Narrative fair value of about $39.56 and sets up a valuation debate around how much early-cycle recovery is already reflected in the price. The analyst consensus Narrative on Simply Wall St ties that fair value to specific assumptions on revenue, margins and discount rates, rather than a simple multiple.
The valuation implies that Robert Half is fairly valued with a bullish skew, assuming current expectations for revenue recovery, cost savings and margin improvement are broadly met over time.
The main thing that has to go right is that tight professional labour markets, AI driven hiring complexity and Protiviti’s mix shift toward technology consulting continue to support demand despite recent revenue and margin pressure.
See why 20 investors see Robert Half as 7% overvalued.
Result: Fair Value of $39.56 (OVERVALUED)
Still, the Robert Half story can break if Protiviti margins remain under pressure and if weak contract staffing volumes keep earnings recovery slower than analysts expect.
Find out about the key risks to this Robert Half narrative.
Another View: Cash Flows Paint a Different Picture
The analyst Narrative pegs Robert Half as about 7% overvalued at a fair value of $39.56, based on earnings forecasts and multiples. Our DCF model tells a very different story. On that approach, RHI at $42.22 trades roughly 44% below an estimated future cash flow value of $75.92. Which lens do you trust more for a long term decision?
Look into how the SWS DCF model arrives at its fair value.
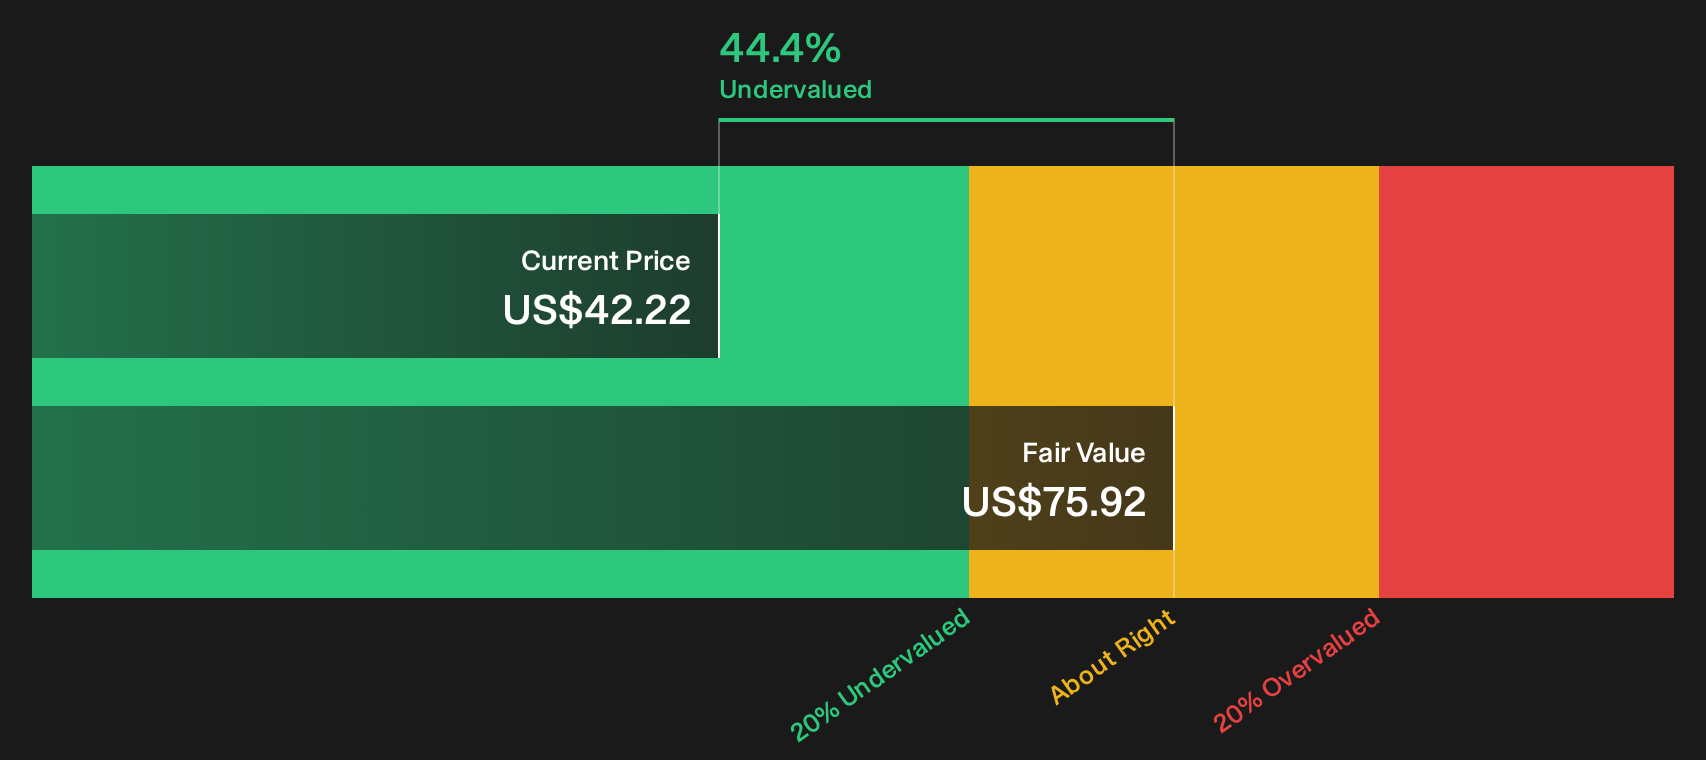
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Robert Half for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
This mix of optimism and concern around Robert Half puts the ball firmly in your court. Weigh the data, pressure test the narratives, and then check the 2 key rewards and 1 important warning sign.
Ready To Hunt For More Ideas Beyond Robert Half?
If Robert Half raised new questions about value, income, and resilience, do not stop here. Put those same filters to work across a wider opportunity set using the Simply Wall St screener.
- Target resilient compounding potential by scanning companies flagged as 32 high quality undervalued stocks and see which ones fit your own margin of safety rules.
- Build a steadier income stream by reviewing our 6 dividend fortresses and focus on businesses that aim to support higher yields with robust cash flows.
- Prioritise defence first by checking the 30 resilient stocks with low risk scores and avoid missing businesses that pair healthier balance sheets with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com