
Brady (BRC) Stock Could Be A Bargain As Its 66% Run Continues
Brady has delivered a strong multi year share price performance, which puts a spotlight on whether the current US$82.40 price is still in line with what its earnings can support. For an investor looking at the stock today, the key issue is how that past return stacks up against the profit engine of the business right now.
- Brady shares are up 65.9% over the past 5 years, which makes it important to test whether that journey is matched by the earnings behind the stock.
- The company relies heavily on the durability and quality of its profit margins and cash conversion, which can shape how much value investors choose to place on each dollar of earnings.
- Your read on Brady is one view; the desks covering it have another. See what analysts think Brady's shares could be worth.
The stock's next move may depend on whether Brady's current earnings level is enough to justify the price investors are paying today.
If you are questioning whether Brady's 65.9% five year return is fully backed by its earnings, it can help to compare that earnings story with a curated set of 32 high quality undervalued stocks.
Is Brady Still Cheap on Earnings?
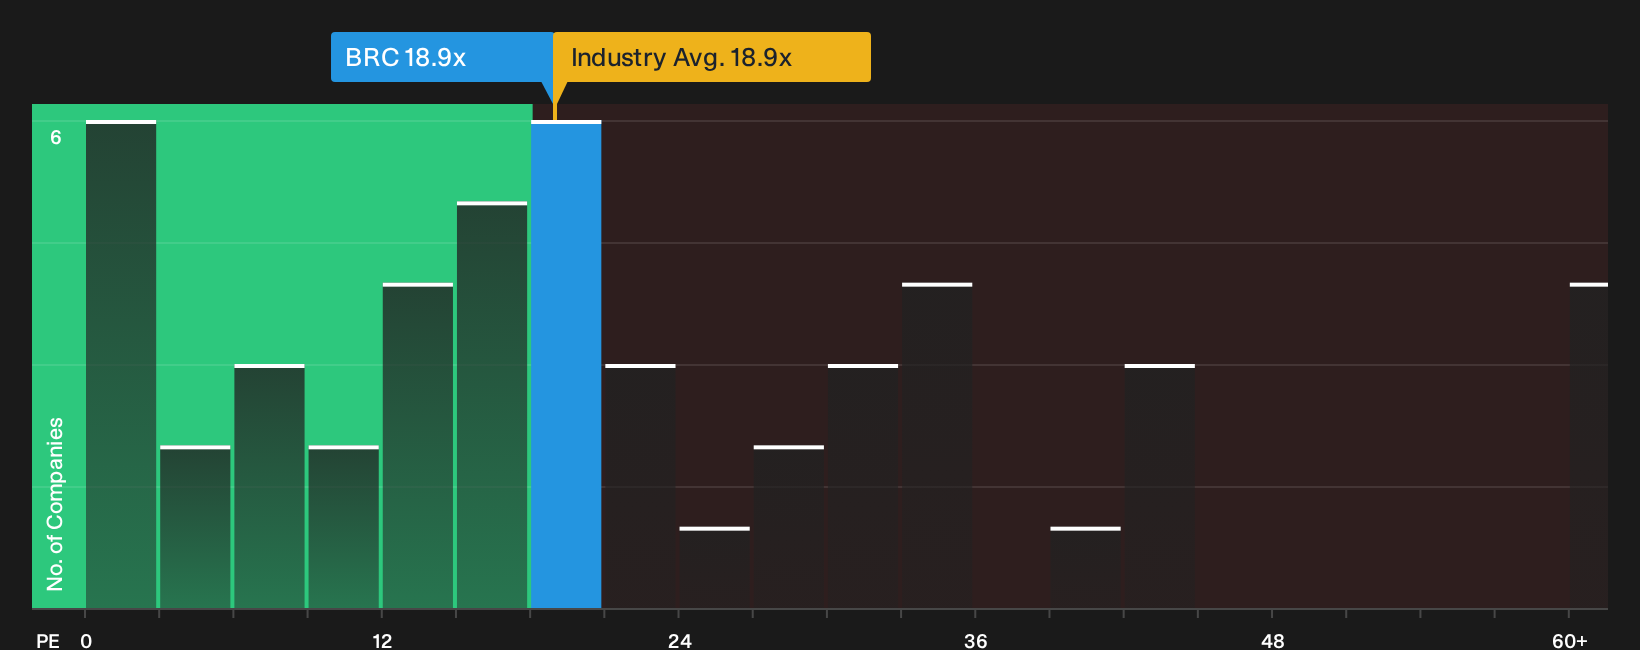
The P/E ratio suits Brady because earnings sit at the centre of how investors judge the business. At the current price, the stock trades on about 18.9x earnings. That is almost identical to the Commercial Services sector average of roughly 18.9x, so the market is valuing each dollar of Brady profit in line with the wider industry rather than giving it a steep premium or discount.
Against more direct peers, though, the picture shifts. Comparable companies average about 14.9x, which means Brady trades on a higher multiple than that peer group. The Fair Ratio model, which looks at factors such as profitability, scale and risk to estimate what a tailored P/E could look like, suggests the present 18.9x level sits below what might be justified on those inputs. For an investor weighing whether the 65.9% five year share price gain is grounded in the earnings power of the business, this gap between the current P/E and the Fair Ratio is worth a closer look. Explore the numbers behind Brady's P/E valuation.
The Brady Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St give you a direct link between Brady's current valuation puzzle and the underlying assumptions that would need to hold on future earnings, margins and growth for the share price to be worth materially more or less than today. Each scenario connects its number to a clear view on how Brady's growth, profitability and risk profile might evolve, which you can revisit as new information and results come through on the Community page.
One of the top narratives on Brady: 25% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is successful integration of IPS so that R&D driven printers and materials growth, recurring software and service revenue, and disciplined capital allocation translate into sustainable margins and cash generation despite cost pressures..."
Discover why this Narrative puts Brady at 25% undervalued.
One more Brady cross check investors often overlook
Price multiples and profit history tell only part of the story. Another useful lens is to compare where professional forecasts see Brady a few years from now with what the current valuation already implies. Explore where analysts expect Brady to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com