
Xencor (XNCR) Is Drawing Fresh Attention, But What Is The Market Weighing?
Xencor (XNCR) drew fresh attention after releasing early Phase 1b data on subcutaneous plamotamab in rheumatoid arthritis, as well as a progress update on autoimmune candidate XmAb657 at a major rheumatology conference.
Against that backdrop, Xencor’s momentum has clearly picked up, with a 30 day share price return of 59.62% and a 90 day move of 73.86%. This has contributed to a 167.90% year to date share price gain and a 177.76% 1 year total shareholder return as traders react to the autoimmune data and the recent swing to quarterly profitability.
Scan Xencor’s autoimmune surge against a wider field by reviewing 37 healthcare AI stocks, which are also pushing hard into antibody engineering and next generation immune therapies.
Bulls view Xencor’s autoimmune data and swing to quarterly profit as the beginning of a reset in how this pipeline is priced. Bears see a sharp sentiment spike that outpaced fundamentals. Which story does the valuation support next?
Most Popular Narrative: 6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Xencor’s fair value sits at $42.50 compared with a last close of $39.97. That framework ties the recent autoimmune and oncology updates directly to a modest implied upside, while still incorporating fairly conservative earnings assumptions.
The robust and flexible XmAb platform allows for modular drug development and the creation of differentiated assets, expected to reduce development costs and timelines. This is described as directly benefiting future operating margins and net profitability.
Clinical trial strategy emphasizes efficient dose ranging and selection, ongoing biomarker efforts, and combination therapy optionality. This is presented as positioning the company to respond rapidly to evolving standards of care and to seek to maximize the commercial potential of its pipeline, with positive implications for recurring revenue and ultimate earnings leverage.
See why 8 investors see Xencor as 6% undervalued.
Result: Fair Value of $42.50 (UNDERVALUED)
Still, if Xencor stumbles on trial execution or XmAb942 and XmAb819 fail to show clear differentiation, the current undervaluation story could quickly unwind.
Find out about the key risks to this Xencor narrative.
Another View: What Xencor’s P/S Ratio Is Signalling
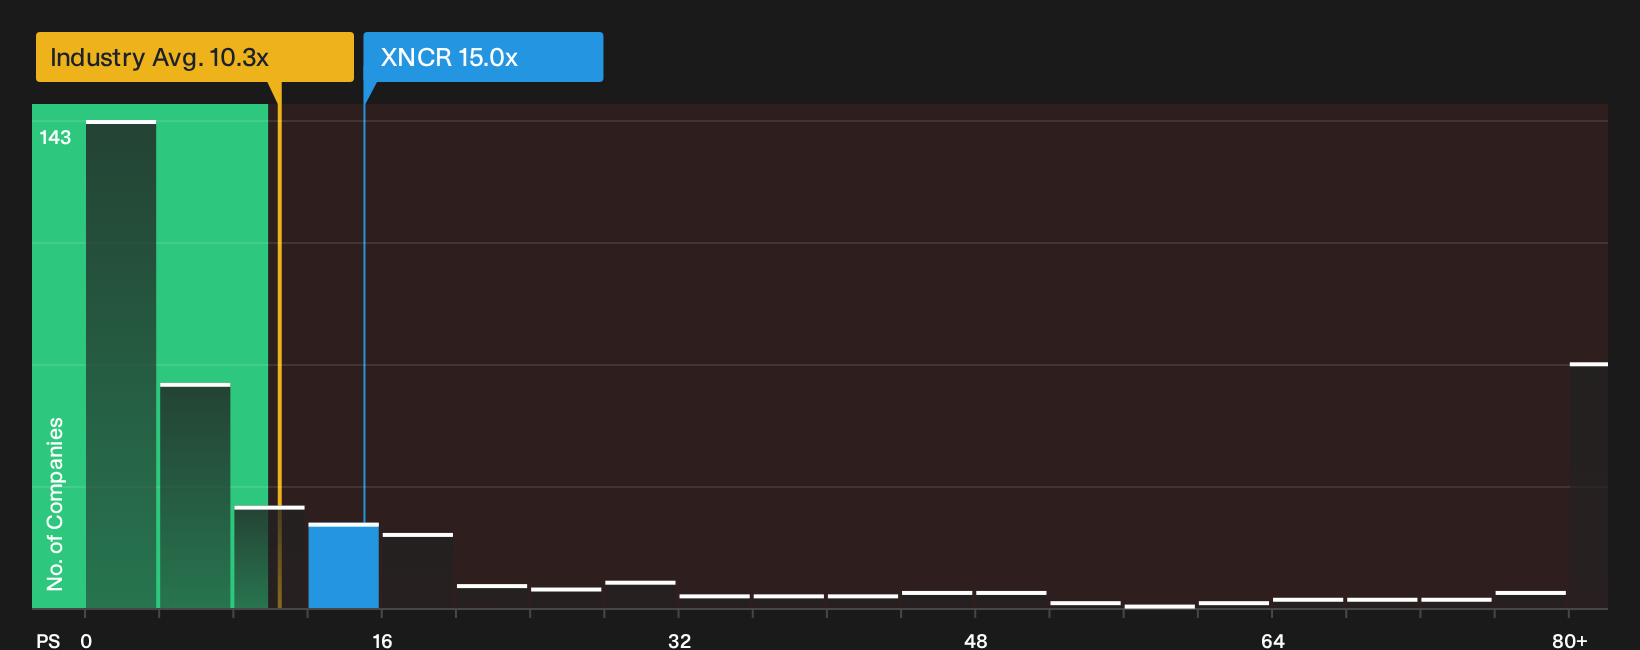
The first take frames Xencor as 6% undervalued on analyst fair value. A different lens tells a tougher story. On a P/S of 15x, the stock trades richer than the US Biotechs industry at 9.7x and far above its own fair ratio of 1.8x, which points to meaningful valuation risk if sentiment cools.
For a closer look at how that pricing gap stacks up against peers and what the numbers imply if the market leans back toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Xencor’s recent swing in sentiment highlights a clear divide between risk and reward. Move quickly, review the full data, and carefully weigh both sides through 1 key reward and 2 important warning signs
Looking for more investing ideas beyond Xencor?
If Xencor has caught your attention, broaden your watchlist now with a few focused stock ideas that match different risk and return preferences.
- Target potential mispricings by scanning a curated set of under-the-radar opportunities with the 19 high quality undiscovered gems.
- Prioritize resilience and capital preservation by reviewing a 30 resilient stocks with low risk scores that scores strongly on financial and volatility checks.
- Strengthen your core holdings by assessing a list of solid balance sheet and fundamentals (23 results) that combines cleaner debt profiles with steady fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com