
What Toyo Suisan Kaisha Shares Earnings Outlook Means For Shareholders
- Toyo Suisan Kaisha reported half year results for the period ended September 30, 2026, with sales of ¥274,064 million, net income of ¥37,151 million and basic earnings per share from continuing operations of ¥385.99.
- The company paired these figures with full year forecasts for higher net sales and profit and kept its second quarter dividend at ¥80 per share, which signals a focus on both earnings progression and cash returns to shareholders.
- We will now look at how Toyo Suisan Kaisha's investment narrative is shaped by stronger half year earnings and upgraded full year guidance.
See how Toyo Suisan Kaisha's latest earnings and dividend profile compare with other resilient operators with low risk scores by reviewing our hand picked 19 resilient stocks with low risk scores in the market.
What Is Toyo Suisan Kaisha's Investment Narrative?
Toyo Suisan Kaisha appeals to shareholders who want a relatively mature food producer with broad segment exposure and measured execution rather than a high growth story. The latest half year update, with higher sales, net income and basic EPS than a year earlier, points to solid demand across instant noodles and processed foods. New full year guidance that points to ¥560,000 million in net sales and ¥82,000 million in operating profit keeps the near term focus on steady operations, disciplined costs and the capital intensity needed to support overseas noodles and cold storage.
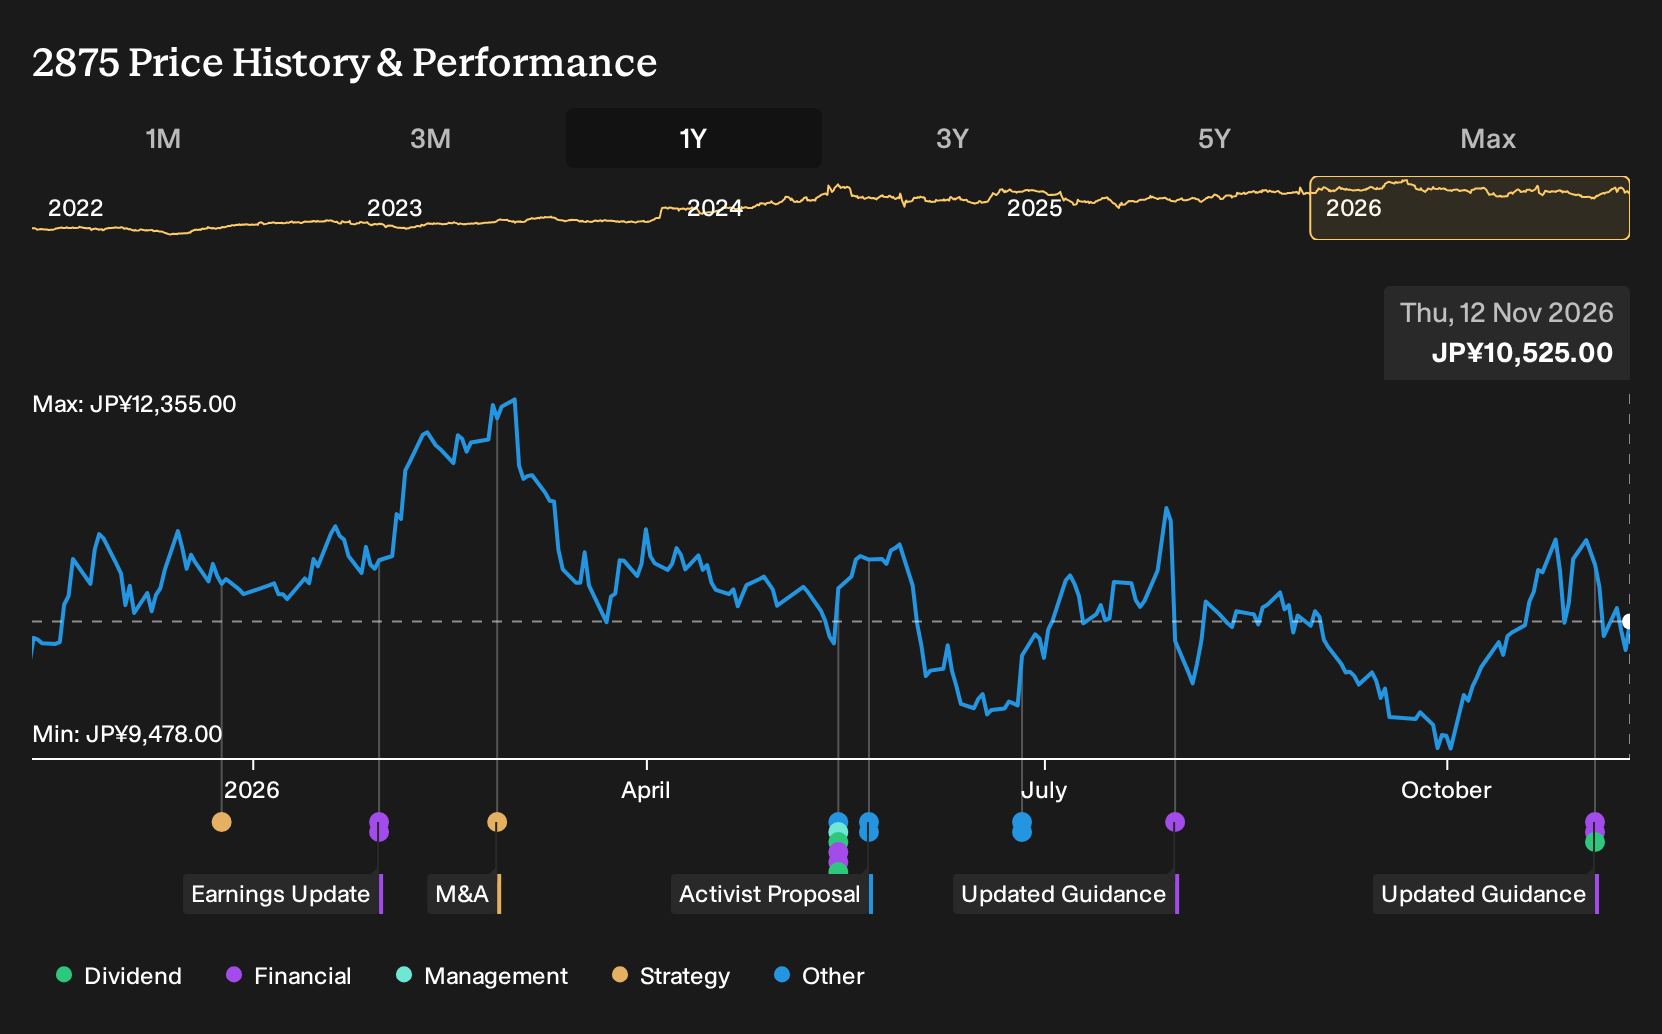
In the short term, the main swing factors look operational rather than related to financial engineering. Management reaffirmed a ¥80 interim dividend per share, which matters if you care about income predictability and cash returns. The recent share price has been a bit soft over the past 7 days but higher over 1 year, so this earnings beat and guidance may not reset the story dramatically. It adds evidence around execution quality and profit mix, while bigger questions now cluster around how Toyo Suisan Kaisha balances modest growth expectations with funding, board structure and capital allocation choices.
That said, tucked inside this otherwise steady picture is one structural issue that could matter more than it first appears...
There's only one way to know the right time to buy, sell or hold Toyo Suisan Kaisha. Head to Simply Wall St's company report for the latest analysis of Toyo Suisan Kaisha's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Toyo Suisan Kaisha research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Toyo Suisan Kaisha. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toyo Suisan Kaisha's overall financial health at a glance.
Looking For More Investment Ideas Beyond Toyo Suisan Kaisha?
If you want to stress test what Toyo Suisan Kaisha offers against other opportunities, the Simply Wall St Screener can help you filter the market down to a focused shortlist that actually fits your goals.
- For investors hunting for mispriced opportunities with solid fundamentals, take a look at our hand picked 20 high quality undervalued stocks that fit a value driven approach.
- If reliable income is a priority, compare Toyo Suisan Kaisha's payout profile with our curated 26 dividend fortresses and see which yields line up with your targets.
- For a focus on robust balance sheets and business quality, scan through the list of solid balance sheet and fundamentals (24 results) and see how they stack up against your current holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com