
Adecoagro (AGRO) Earnings Beat Keeps Its Undervalued Narrative In Play
Adecoagro (AGRO) has drawn fresh attention after reporting quarterly revenue growth of 39% and a 55.6% jump in earnings per share, along with a 2.72% dividend yield funded by a 93% payout ratio.
Adecoagro’s recent earnings surprise has landed on a stock that has already been active this year. The share price is $9.05, with a 1-day share price return of 1.34% and a year-to-date share price gain of 16.62%. However, the 30-day share price return is down 12.14% and the 3-year total shareholder return is down 5.68%. This leaves the 5-year total shareholder return of 13.80% as the stronger reference point for investors weighing whether momentum is rebuilding after a weaker spell.
Scan other agriculture and food producers moving on similar earnings and dividend stories by reviewing the hand-picked 19 high quality undiscovered gems alongside Adecoagro.
Adecoagro has posted strong quarterly numbers and a solid year-to-date gain, yet the recent pullback and relatively high P/E ratio compared with the Food sector raise a simple puzzle: Is most of the easy upside already gone or not?
Most Popular Narrative: 50.5% Undervalued
Adecoagro’s most followed narrative on Simply Wall St sets a Fair Value of $18.28 per share against the last close of $9.05. This frames the current debate around how much upside that narrative is baking in. According to Talos, an investor in the Simply Wall St Community who wrote the narrative, the key point is how Adecoagro’s assets and cash flows are wired to global food and fertilizer supply shocks under an 8% discount rate.
The Causality: Why Agribusiness, and Why Now? To understand AGRO’s value proposition, we must look at the intersection of climate models and global supply chains. Meteorological projections indicate a high probability of a "Super El Nino" (Oceanic Nino Index > +2.0) peaking around November 2026. This is not just a weather event; it is a systemic "threat multiplier" that reshuffles global economics:
See why 6 investors see Adecoagro as 50% undervalued.
Talos sets out a Fair Value of $18.28 using revenue of $3.0b, a 12% profit margin, a 15x P/E exit multiple and an 8% discount rate. Together, these assumptions imply Adecoagro could be worth roughly double the current share price if those inputs materialize. That approach hinges on Adecoagro’s vertically integrated footprint in sugar, ethanol, fertilizers and farming, the Profertil acquisition and what that might mean for future cash generation rather than today’s reported net income of $49.5m and 3% net margin.
The same narrative leans on Adecoagro’s recent jump in adjusted EBITDA and a focus on deleveraging after taking net debt to $1.63b for the Profertil deal. It argues that lower leverage and ongoing capital returns could support that higher valuation over time. Readers weighing this view against Adecoagro’s low reported 3.2% return on equity, one off gains of $31.1m in the last twelve months and a high payout ratio on an unstable dividend track record may want to stress test how sensitive that $18.28 figure is to changes in margins, fertilizer pricing and interest costs.
Result: Fair Value of $18.28 (UNDERVALUED)
Still, two things could quickly undercut that Adecoagro thesis: weaker than expected fertilizer pricing from Profertil and a slower pace of deleveraging than investors anticipate.
Find out about the key risks to this Adecoagro narrative.
Another View: Adecoagro Through The Market’s Lens
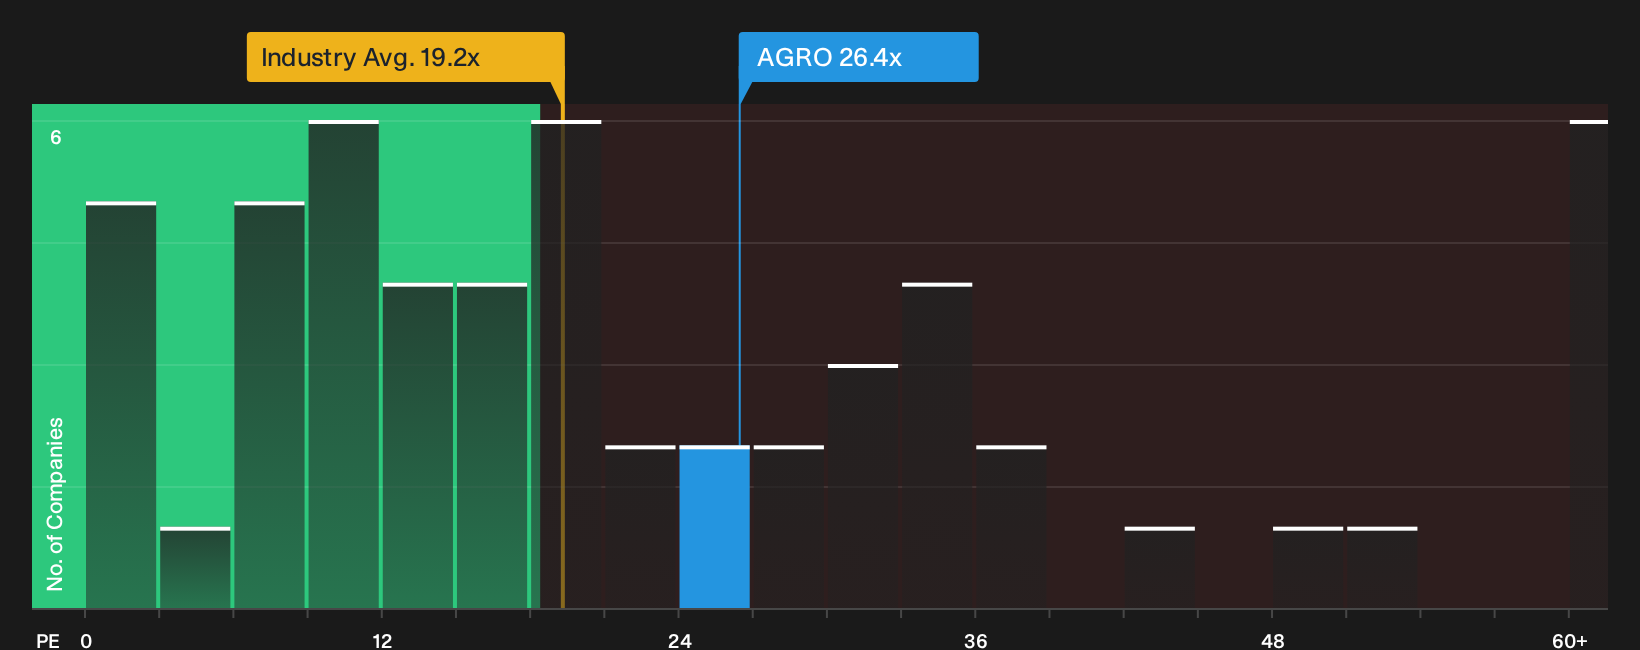
Adecoagro looks cheap in Talos’s narrative, yet the market is pricing the stock very differently. The shares trade on a P/E of 26.4x, compared with 19.1x for the US Food industry and 20.5x for peers, while the fair ratio sits lower again at 18.8x.
That gap means investors are already paying a richer multiple than both direct comparators and the level the market could move towards. This raises a simple question: if earnings or sentiment wobble, how much room is there before that premium multiple compresses?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Adecoagro can feel confusing, so move quickly, pull up the data for yourself, and weigh both the 3 key rewards and 4 important warning signs.
Looking for more Adecoagro style investment ideas?
If Adecoagro has sharpened your curiosity, do not stop here. Use focused stock lists to spot fresh ideas before they move and keep your watchlist evolving.
- Chase value opportunities that pair quality with attractive pricing by scanning our curated list of 32 high quality undervalued stocks that match strict fundamental filters.
- Strengthen the income side of your portfolio and review companies offering resilient payouts through the 6 dividend fortresses tailored for yield focused investors.
- Protect your downside first and hunt for resilient businesses screened by the 30 resilient stocks with low risk scores designed to highlight steadier balance sheets and risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com