
Texas Data Center Ban Risk Tests Dell Stock As AI Products Roll Out
- The University of Alabama, CrowdStrike, Spectro Cloud, AMD, KIOXIA and Dell Technologies have disclosed new deployments and products built on Dell PowerEdge servers, high density storage and AI focused infrastructure for research, security and coding workloads.
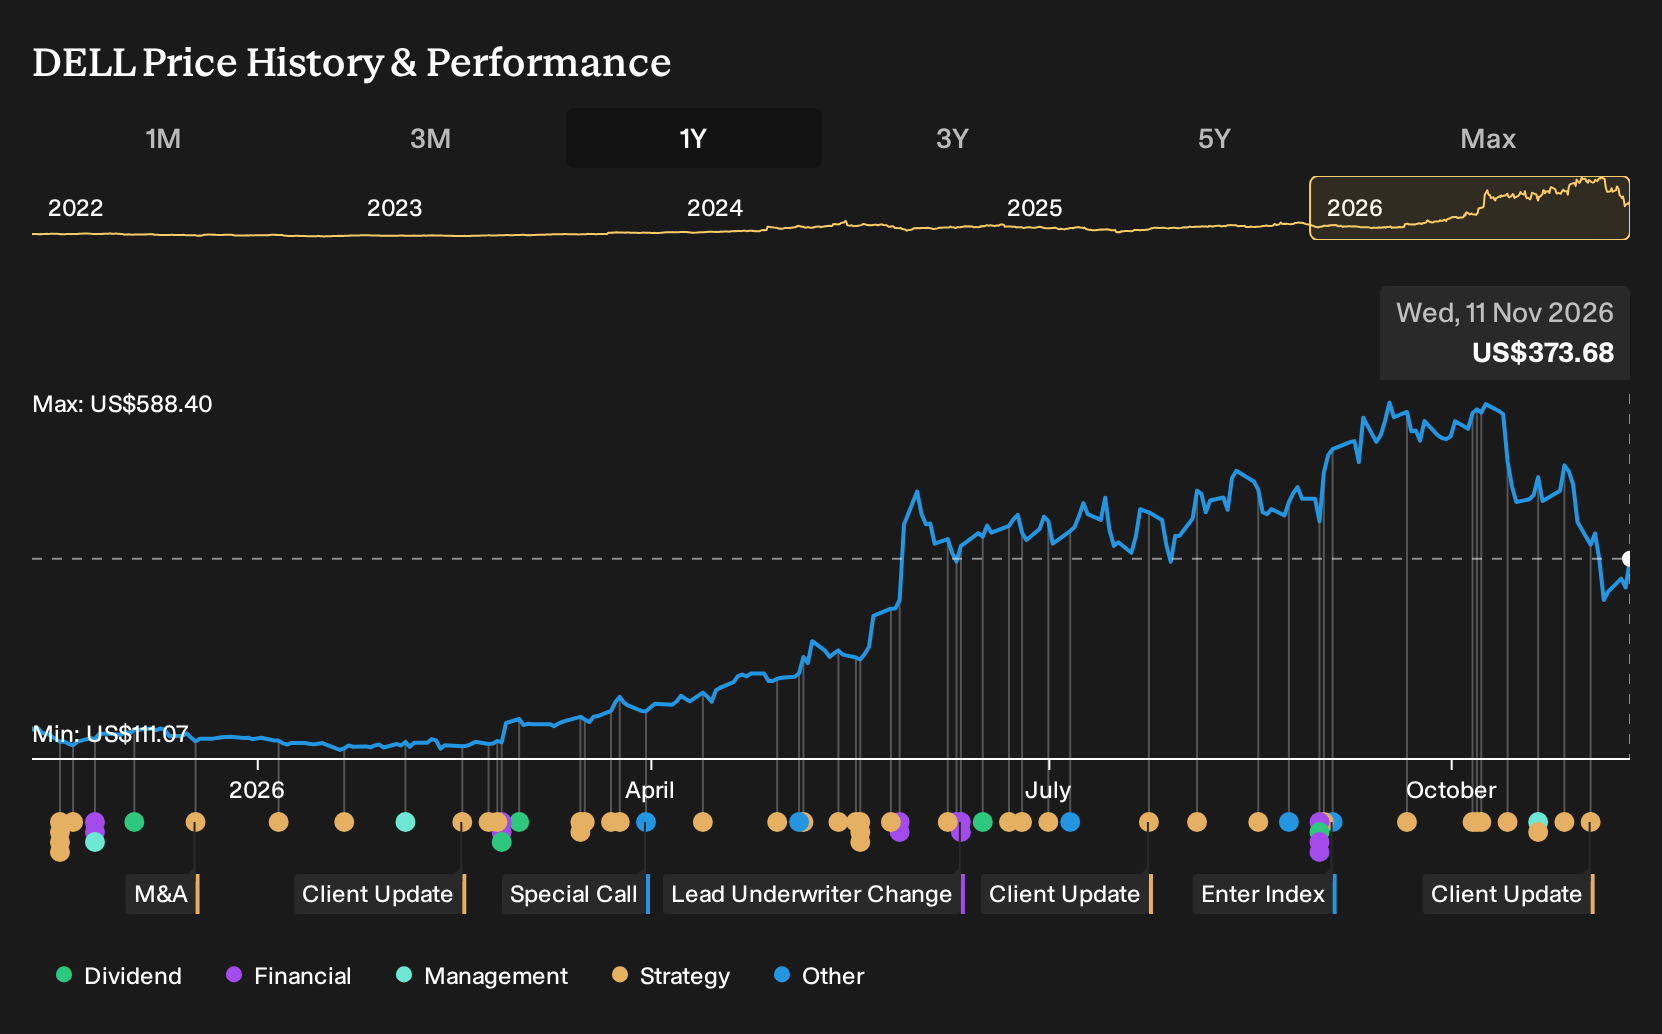
- The same period brings concern over a pledged Texas ban on new data center permits, which directly tests how resilient Dell Technologies' large AI hardware backlog and future order pipeline really are.
- We will now look at how Dell Technologies' AI driven investment narrative holds up against Texas data center risks and new product launches.
Scan how other AI heavyweights are priced by jumping into our hand picked list of 53 AI infrastructure stocks alongside Dell Technologies in the data center build out story.
Dell Technologies Investment Narrative Recap
To own Dell Technologies on the current story, you need to buy into the analyst consensus Narrative on Simply Wall St that the AI server backlog, storage growth and commercial PC refresh together can support future earnings while margins gradually improve. The Texas data center permit threat goes straight at that thesis, since it questions how quickly a US$95b AI backlog and pipeline can convert into infrastructure revenue.
Right now, the short term catalyst is execution on AI infrastructure orders and proof that ISG margins hold up as AI servers remain rate dilutive. The main operational risk is that hardware pricing, supply constraints and policy surprises such as the proposed Texas moratorium slow backlog conversion and leave Dell carrying lower margin AI hardware mix for longer.
The announcement that looks most tied to this debate is the University of Alabama High Performance Computing Center built on Dell PowerEdge, PowerScale and NVIDIA infrastructure. It highlights that even while investors worry about Texas data center permits, Dell Technologies continues to win AI heavy deployments in education and research that rely on dense compute and storage.
For you as a shareholder, that kind of reference site matters because it shows Dell’s AI Factory and data platforms in a real multiyear workload, not just a benchmark slide. It also reinforces a key part of the current catalyst story, that higher margin storage, software and services, including Dell HPC Deployment Services around these systems, can offset thinner AI server margins if execution stays consistent.
Dell Technologies Forecasts Behind The AI Story
Dell Technologies' narrative projects forecast revenues of US$266.7b and consensus earnings of US$20.8b by 2029. Analysts are incorporating revenue growth of 20.8% per year and an earnings increase of about US$9.4b from current earnings of US$11.4b to reach that target.
Uncover why Dell Technologies' fair value indicates a 59% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
Texas data center delays are the flashpoint, yet the more cautious analysts were already building in slower AI conversion at Dell Technologies. Before this news, the lowest forecasts only had revenue reaching about US$238.3b and earnings around US$19.0b by 2029. That is a much tougher story than the consensus. Use this new Alabama win as a reason to compare those differing expectations and decide which version of the future feels closer to your own view.
Explore 4 other Dell Technologies fair value estimates, including one that suggests it could be worth just $490.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dell Technologies research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dell Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dell Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Dell Technologies?
Once you have formed a view on Dell Technologies, it often helps to put that opinion in context by lining it up against other possible opportunities using the Simply Wall St Screener.
- If you want potential upside with a margin of safety, scan a curated set of companies that look mispriced on fundamentals through the 32 high quality undervalued stocks.
- If income is a priority for your portfolio, filter for reliable payout candidates using our hand picked group of 6 dividend fortresses to see which ones fit your risk profile.
- If balance sheet strength matters most to you, start with a list of solid balance sheet and fundamentals (23 results) and compare those businesses against Dell Technologies on debt, liquidity and earnings quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com