
Is National Vision Holdings (EYE) Stock Fully Priced After A 63% Fall?
National Vision Holdings has seen its share price move around over the years, and today investors are asking whether the current US$18.09 level is properly backed by the earnings the business generates. The question is not just where the chart has been, but whether the current P/E makes sense given how the optometry chain converts sales into profit.
- Over the past 5 years the stock has fallen 62.6%, which puts the focus squarely on whether the present earnings multiple still matches what the business can deliver.
- The company relies on an optometry retail model that can be sensitive to store productivity and operating costs, so any change in margins may support a different view of what investors are willing to pay for its earnings stream.
- Your read on National Vision Holdings is one view; the desks covering it have another. See what analysts think National Vision Holdings's shares could be worth.
The issue now is whether National Vision Holdings' current share price is adequately supported by its earnings power when judged against the Fair Ratio benchmark.
If you are weighing whether National Vision Holdings' current P/E still makes sense after a 62.6% share price decline over 5 years, it can help to compare that lens with 32 high quality undervalued stocks.
Does National Vision Holdings Look Pricey on Earnings?
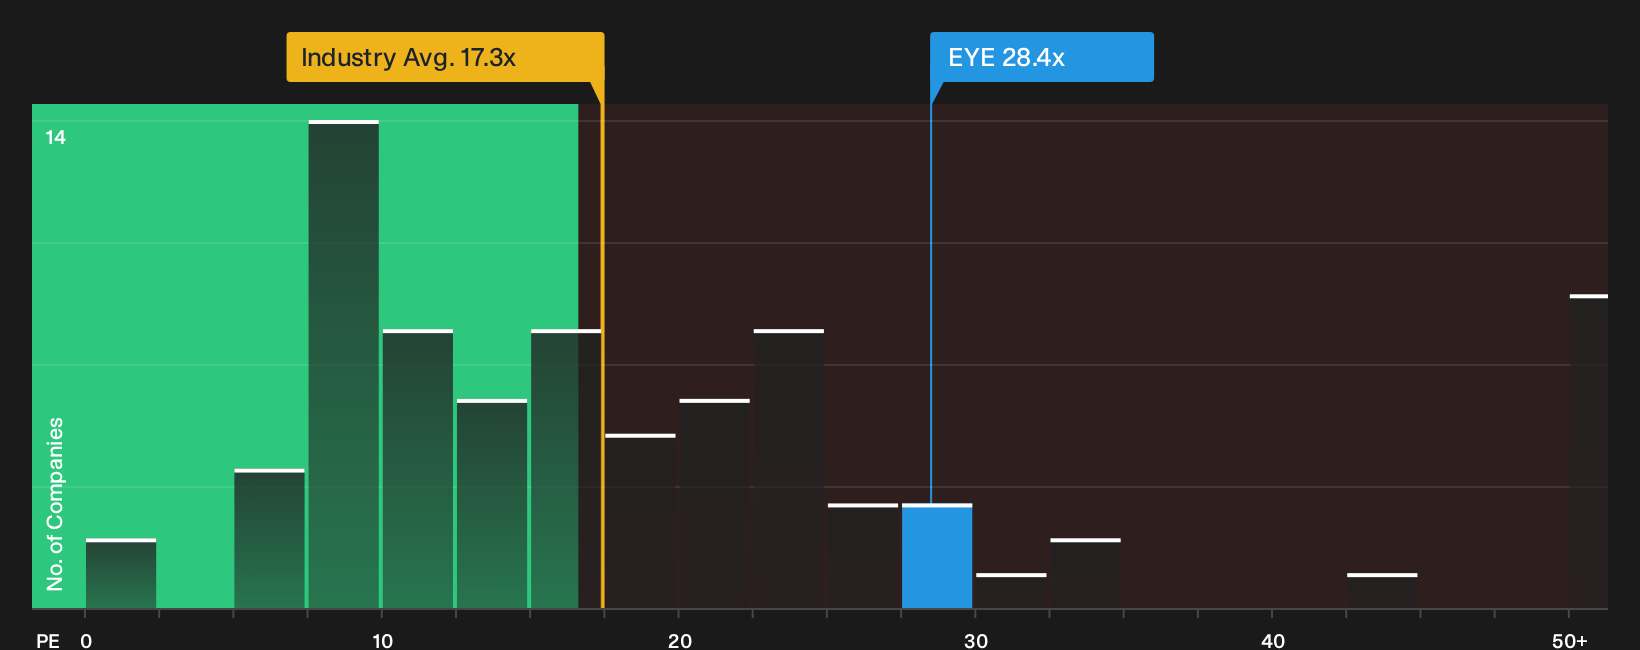
The P/E lens suits National Vision Holdings because profit is a key filter for how investors weigh a retailer with fixed store costs and variable traffic. At roughly 28.4x earnings, National Vision trades at a clear premium to the Specialty Retail sector, where the average is about 17.3x, and also above a peer group closer to 18.2x. That gap indicates the market is attaching a richer price tag to each dollar of reported profit at National Vision than to many comparable retailers.
The Fair Ratio, which blends in the company’s own growth profile, margins, size and risk, points to a lower multiple than where the stock currently trades. On this framework, National Vision screens as overvalued relative to what its earnings power would justify on a more tailored basis rather than just against broad sector averages. For anyone looking at the recent share price decline and wondering if the stock is now cheap on earnings, that premium P/E and the Fair Ratio signal argue for a closer look at what has to go right to support it. Explore the numbers behind National Vision Holdings's P/E valuation.
The National Vision Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for National Vision Holdings pick up where the valuation puzzle leaves off by spelling out which combinations of growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each one treats fair value as a thesis about the business that can be revisited over time rather than a single frozen snapshot.
One of the top narratives on National Vision Holdings: 34% undervalued
This is the analyst consensus Narrative on Simply Wall St, which compiles analysts' price targets plus their revenue and earnings forecasts into one view.
"The current valuation implies that the market is underestimating National Vision Holdings' potential earnings power if mix-led ticket gains, SG&A leverage, and ongoing premium assortment investments continue..."
Discover why this Narrative puts National Vision Holdings at 34% undervalued.
For National Vision Holdings, price is only one piece of the investment puzzle
Valuation frames what you pay today, but the analyst models for where National Vision Holdings might be a few years from now offer a separate storyline that can sharpen or challenge your view. Explore where analysts expect National Vision Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com