
3 British Nuclear Stocks To Own In November 2026
Global power grid construction recently increased 50%, and that kind of build out needs round the clock electricity that is not tied to weather. Reliable nuclear power sits squarely in that conversation, which puts selected UK nuclear energy stocks on many watchlists. This article walks through three picks from our nuclear screen and highlights what each offers if you are weighing long term exposure to this theme.
The three stocks highlighted here offer a compelling starting point if you want exposure to uranium producers, fuel cycle specialists, and nuclear plant operators powering reliable and sustainable electricity. However, if you want the names that matter most, these 16 nuclear renaissance stocks are the strongest companies we've found.
Rolls-Royce Holdings (LSE:RR.)
Rolls-Royce Holdings is best known for aero engines, yet for this nuclear screen the interest lies in its submarine reactor systems and broader power expertise. The analyst consensus Narrative on Simply Wall St captures how that nuclear link could sit alongside its larger aviation and power activities over time.
"Rolls-Royce SMR has secured multi-country selections and is already in execution for units in the UK, Sweden and the Czech Republic while aiming to commission up to 2 small modular reactors per year in the mid 2030s and up to 8 per year at maturity. This could create a potential new source of high margin revenue and profit growth."
What happens if a single assumption about long term cash generation in these complex projects shifts even slightly away from current expectations?
When small shifts in those long term cash assumptions matter this much, the full narrative for Rolls-Royce Holdings maps how Rolls-Royce could turn nuclear ambitions into accelerating value or fresh risk.

National Atomic Company Kazatomprom JSC (LSE:KAP)
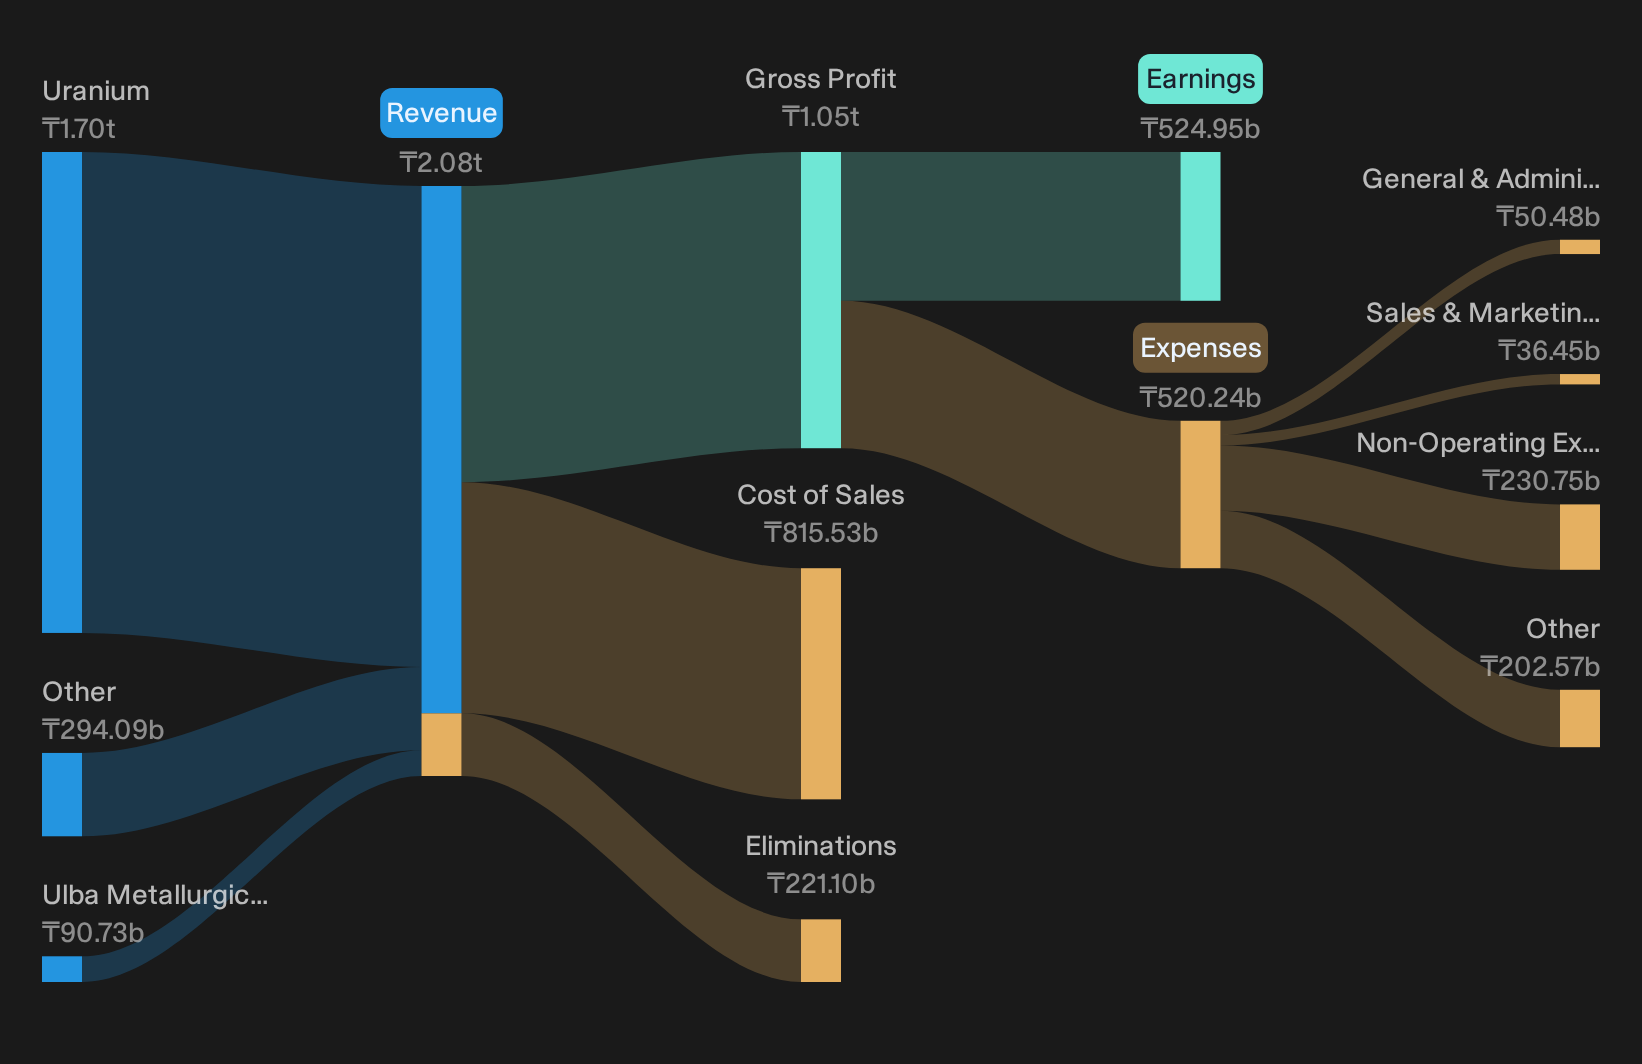
National Atomic Company Kazatomprom JSC is a uranium focused miner and processor. Its Uranium segment generates about KZT 1,697 billion of revenue, alongside smaller Ulba Metallurgical Plant and Other activities, giving a roughly KZT 1,645 billion total. The group has a market value near US$16.5b.
The bullish analyst Narrative on Simply Wall St presents Kazatomprom as a relatively direct way to gain exposure to uranium supply, arguing that its mining footprint, contract book and value over volume approach provide significant leverage to a nuclear buildout that is still unfolding.
"Global moves to expand nuclear power capacity, including plans by many countries to triple nuclear use by 2050 and more than 70 reactors under construction, can keep utilities focused on securing uranium for future fuel needs and support longer term revenue opportunities for National Atomic Company Kazatomprom JSC."
A key consideration is what happens if one rising cost line quietly reshapes how much of that potential uranium revenue flow reaches Kazatomprom’s bottom line.
That pressure on profitability is exactly where the full narrative for National Atomic Company Kazatomprom JSC shows how Kazatomprom’s uranium position could accelerate or be quietly constrained by cost trends and contract choices.
Centrica (LSE:CNA)
Centrica links into the Nuclear Energy Stocks theme through its nuclear power generation and the trading of nuclear-sourced electricity, layered onto a broad retail and infrastructure platform that generated about £16.3b from Retail, £6b from Optimisation and £1.6b from Infrastructure, with a market cap near £7b.
Centrica provides exposure to nuclear-linked power within a much wider energy business. The analyst consensus Narrative on Simply Wall St highlights one important shift in how that income mix could evolve.
"Expanding investment in regulated and contracted infrastructure such as Sizewell C, Grain LNG and the Meter Asset Provider, which together contributed about £80m of EBITDA in H1 2026 and are expected to reach roughly £175m in 2026, points to a growing base of long-duration earnings that can raise the share of predictable EBITDA and support more stable net margins."
What happens to those margins if a single pressure on that emerging infrastructure earnings base proves stickier than analysts currently build in?
If that pressure does not ease, the full narrative for Centrica shows how Centrica’s nuclear and infrastructure mix could still compound value, while also indicating where earnings risk might be quietly building.

Seeking Alternatives Before The Crowd?
Fresh themes can gain momentum quickly, and early attention often goes to the investors who spot breakout stories while they are still under the radar. For now, this may be a good time to explore ideas and refine your watchlist.
- Scan for resilient income plays and review ideas from the 4 dividend fortresses that could help anchor a portfolio when growth stories are in focus.
- Look for potential future enablers of AI and see which businesses in the 53 AI infrastructure stocks are building the underlying tools and services for that trend.
- Monitor resource-related opportunities and review the 33 elite gold producer stocks that might be relevant if attention shifts toward hard assets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com